In a nutshell:
Major US benchmarks finished lower and close to worst levels after US S&P PMI flagged US business activity surging to a five-year high, pushing 10-year yields to two-decade peaks and increasing October rate hike bets to 69.7%
Brent rallied 5% to US$103.45 a barrel, snapping a five day losing streak, on Hormuz risk and diesel supply fears, with European diesel at a record and the White House denying a report it is drafting an export ban
Trump hosts Xi Jinping at the White House today, with the tariff truce, rare earth flows and AI safeguards all on the table
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,706 | -0.75% |
Dow Jones | 51,512 | -0.68% |
NASDAQ Comp | 26,936 | -1.13% |
Russell 2000 | 2,839 | -1.77% |
Global Indices | ||
 S&P/TSX | 35,751 | -1.61% |
 Shanghai Composite | 3,937 | -0.34% |
 DAX | 25,411 | -0.66% |
 Hang Seng | 24,834 | -1.01% |
 Nifty 50 | 74,828 | +0.40% |
 Nikkei 225 | 65,019 | +1.38% |
 FTSE 100 | 10,705 | -0.03% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,287.39 | -1.76% |
 Copper | 6.71 | -0.70% |
 WTI Oil | 92.71 | +2.42% |
Currency | ||
 AUD/USD | 0.704 | 0.00% |
Cryptocurrency | ||
 Bitcoin (USD) | 84,380 | -2.02% |
 Ethereum (AUD) | 3,805 | -2.57% |
Miscellaneous | ||
US 10 Yr T-bond | 5.114 | +2.94% |
VIX | 15.18 | +6.83% |
US Sectors
Sector | % Chg |
|---|---|
| Energy | +1.04% |
| Industrials | -0.11% |
| Consumer Staples | -0.17% |
| Financials | -0.44% |
| Materials | -0.65% |
| Health Care | -0.65% |
Sector | % Chg |
|---|---|
| Information Technology | -0.66% |
| Real Estate | -1.49% |
| Consumer Discretionary | -1.63% |
| Utilities | -1.87% |
| Communication Services | -1.89% |
S&P 500 Session Chart
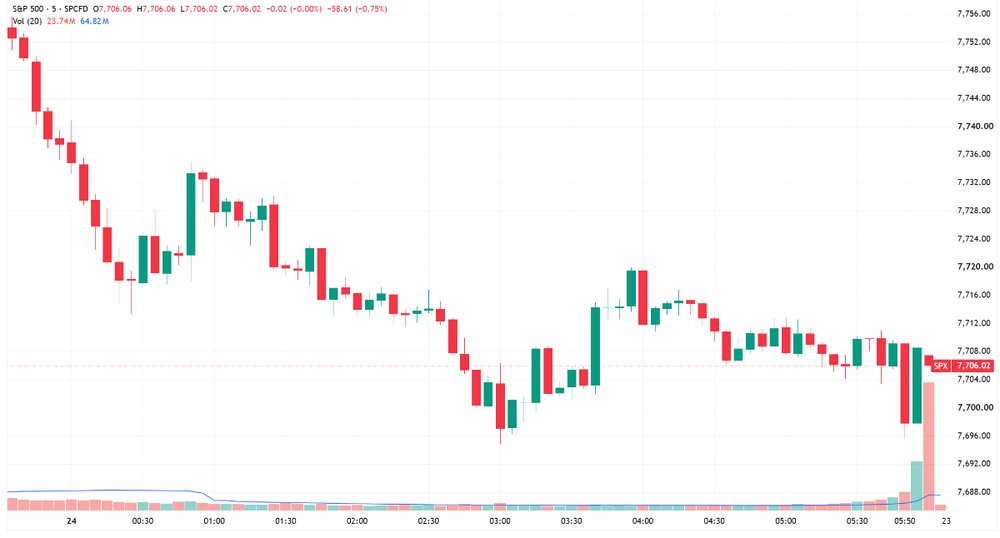
S&P 500 trended lower throughout the session and finished close to worst levels (Source: Trading View)
Overnight Markets
Major US benchmarks pulled lower early to finish near worst levels after hot PMI print
US 10-year yield rose 15 bps to reach 5.11%, its highest since July 2007 and the biggest one-day move since April 2025, while the 2-year hit 4.89%, a level last seen in May 2024
US 5-year yields breached 5% for the first time since 2007 as a poorly received auction accelerated the slide
US Dollar index pushed 0.5% higher to 101.1, extending gains a 2.3% run since 9 September, now at its highest since July
Brent rose 5% to US$103.45 a barrel, snapping a five day losing streak, as tight fuel supplies, Hormuz risk and diesel export speculation drove a choppy session
Gold fell 1.6% to US$4,287/oz extending an 8% pullback since 25 August and silver near US$64.4/oz, both retreating as strong US data lifted yields and the dollar
Copper pulled back from near-record levels on the London Metal Exchange after a six-day advance, with traders weighing shifting oil prices and hawkish Fed commentary (BBG)
European diesel's premium to Brent jumped above $95 a barrel, a record in Bloomberg data going back to 2011, as the threatened US ban put the region's main overseas supplier at risk (BBG)
The Australian dollar came under fresh pressure near 0.7100 and the yen sat near mid-157 as a firmer greenback and hawkish Fed pricing weighed on major currencies (FXStreet)
Procyon head of US equities Massimo Santicchia said strong corporate earnings are in a tug of war with inflationary pressure, adding there is no way the Fed lowers rates or pauses now (CNBC)
Stocks
McDonald's fell 5% in afternoon trading after unveiling a plan to spend heavily on restaurant remodels, with CEO Chris Kempczinski telling CNBC the chain expects elevated inflation and flat industry traffic to persist rather than ease, a message Wall Street did not reward (CNBC)
Disney is raising streaming prices for the fourth time in four years, with ad-free Disney+ and Hulu each up 13% or US$2.50 to US$21.49 a month, narrowing the gap to Netflix's US$26.99 top tier and steering subscribers towards the cheaper bundle (BBG)
Apple began shipping upgraded Mac minis and Mac Studios costing up to nearly US$20,000, pitching corporate buyers on running AI workloads locally rather than renting data centre capacity, a direct challenge to Nvidia and Microsoft in on-device AI (RT)
AI personal assistants are upending a slice of the market, with Meta's Muse agent topping app download charts and investors marking down banks, insurers and online travel names exposed to consumer inertia (BBG)
Nvidia's compressing valuation is flagging a warning on profit growth, with the shares up 22% in 2026 against a 76% gain for the semiconductor index and gross margin seen dipping below 72% in the fourth quarter (BBG)
Geopolitics
Iranian President Masoud Pezeshkian used a defiant UN General Assembly address to blame the US and Israel for stoking global instability, insisting Tehran seeks no nuclear weapons and will accept no limits on peaceful nuclear technology (CNBC)
Pezeshkian said Iran cannot let some countries have free access to the Strait of Hormuz if the waterway is used to impose aggression, with the US delegation's seats left empty during the speech (ABC)
Iran's military called Trump's threats to annihilate Tehran a sign of strategic desperation and said it stands ready to deliver strikes more crushing than earlier in the seven-month conflict (CNBC)
Trump said US officials held a very productive meeting with Iranian envoys on the UN sidelines and indicated further talks were planned despite his hardline speech a day earlier (BBG)
Tehran has signalled it could reopen the Strait of Hormuz within seven days if Washington lifts its naval blockade of Iranian ports and eases military pressure (TE)
Secretary of State Marco Rubio said Vladimir Putin has been invited to the G20 summit in Miami in December, which would be his first in-person attendance since 2019 (CNN)
Tariffs
Trump hosts Xi Jinping at the White House today, the Chinese leader's first US visit since 2015, with the trade truce between the two countries due to expire on 10 November (RT)
US Trade Representative Jamieson Greer said discussions on extending the truce would continue and that Washington needs to keep pressure on Beijing to ensure compliance on critical minerals (RT)
Soybean, Boeing aircraft and rare earth commitments underpinning the truce are being met at markedly different speeds, with China having bought almost half its 25m tonne annual soybean commitment (CNBC)
Central Banks
Fed Governor Michael Barr said further policy adjustments are likely to be needed, noting growth is strong and the labour market solid but inflation is above target and not clearly trending towards it (YF)
Odds of a Fed rate hike at the October meeting rose to 68%, up from 55% a day earlier, after a run of hawkish policymaker commentary (FXStreet)
Richmond Fed President Tom Barkin said it could take time for inflationary shocks to wane, with other officials also signalling that further tightening may be needed (BBG)
The OECD raised its 2027 inflation projections for every G20 economy apart from China and Saudi Arabia and said monetary policy may have to respond with more tightening from the US to Australia (BBG)
RBA Governor Michele Bullock said Australia's jobs market is probably still a bit too tight and putting upward pressure on wages, business costs and inflation, with all four major banks expecting a hike at the 28-29 September meeting (ABC)
Economy
US flash manufacturing PMI raced to 56.7 in September, a level not seen in more than four years, against ests of 53.6 and August's 53.9 (CNBC)
US flash services PMI climbed to 58.7 from 56.5, its highest in nearly five years, with the composite at 58.4 against ests of 55.3 (YF)
Euro area flash composite PMI unexpectedly rose to 53.1 from 52.0 against ests of 51.7, with services at 53.0 and manufacturing steady at 52.7 (FXStreet)
Australia's flash PMIs showed manufacturing slipping into contraction and services expanding only slowly for a second straight month (NS)
Global debt climbed to a record $365 trillion in the first half, with advanced economies spending more than $3.5 trillion on interest over 12 months, above estimated global AI spend of $2.6 trillion, says IIF (YF)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Steel | 104.8 | -1.81% |
| Lithium & Battery Tech | 69.58 | -2.45% |
| Strategic Metals | 68.76 | -3.11% |
| Copper Miners | 87.03 | -3.28% |
| Uranium | 41.99 | -4.00% |
| Gold Miners | 93.56 | -4.36% |
| Silver Miners | 92.22 | -5.33% |
Industrials | ||
| Agriculture | 28.55 | 0.00% |
| Aerospace & Defense | 213.92 | -0.04% |
| Construction | 91.684 | -1.92% |
| Global Jets | 28.25 | -2.99% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 206.6 | -2.00% |
Renewables | ||
| Hydrogen | 44.66 | -2.49% |
| Solar | 45.05 | -3.12% |
Technology | ||
| Cybersecurity | 47.12 | +1.93% |
| Cloud Computing | 29.14 | +0.66% |
| Semiconductor | 565.72 | -1.23% |
| Electric Vehicles | 33.7143 | -1.96% |
| Robotics & AI | 35.29 | -2.00% |
| FinTech | 25.4279 | -2.09% |
| Data Center & Digital Infrastructure | 28.16 | -2.15% |
ASX Today
Forrestania Resources lifts the British Hill global resource 21% to 212,400oz Au at 1.60g/t, with the higher-confidence Indicated category up 37% to 138,100oz Au at 1.62g/t on 15 RC holes (3,685m) drilled since the previous estimate a month earlier. Drilling continues with three RC rigs and one diamond rig, targeting extensions along strike and down dip (FRS)
Soul Patts posts revenue up 96% to $1,872 million, with statutory NPAT up 502% to $2,191 million, driven by a $1.3 billion day-one accounting gain from the Brickworks merger. Net Cash Flow From Investments up 11.5% to $571.5 million. Final dividend of 63 cents per share, fully franked, up 6.8% on FY25 (SOL)
Kaoko Metals expands the Chalkos drilling program to at least 15,000m, with five diamond holes completed at Otniel and a sixth in progress. Assays for the first two holes due in 2-3 weeks. New surface discovery at Donkey Hill East returns grades up to >50% Cu, extending the mineralised trend 700m to a 1,500m mapped footprint, with a second rig now drilling there (KAO)
GenusPlus wins a Design and Construct contract from Atmos Renewables for 330kV terminal, transmission line and ancillary works at the Parron Maam Marang Farm substation in WA, worth circa $135 million including early works already completed. Work is subject to Atmos reaching financial close and issuing notice to proceed, with completion due in 2028 (GNP)
What To Watch Today
The unwind: The past few days had yields and oil slowly moving in the right direction. The overnight session undid all of it. The US 10-year yield V-shaped back to fresh 19-year highs, back above the uncomfortable five handle, while the 2-year surged 15 bps to 4.89% as markets priced in more rate hikes. Brent, which had finally slipped into the US$90s, is back at US$103 a barrel. The US Dollar Index has staged its own V-shaped move since 9-Sep, up 2.3% to 101.14, including a 0.57% jump overnight. A one-day move of that magnitude is usually a wrecking ball for global equities.
Commodities smashed: The commodity complex (ex-energy) copped the brunt. Copper fell 1.5% to US$6.81/lb, gold tanked, aluminium slipped 0.3% to US$3,235/t and Singapore iron ore futures settled at US$96.85/t. Equities fared even worse, with our overnight ETF watchlist flagging heavy declines for Gold Miners (-4.3%), Uranium (-4.0%), Copper Miners (-3.2%), Rare Earths/Strategic Metals (-3.1%) and Airlines (-3.0%). It's going to be a rough one for miners today.
Key Events
Stocks trading ex-dividend:
Thu 24 Sep: Bisalloy Steel Group (BIS) – $0.13, Briscoe Group Australasia (
Fri 25 Sep: Teaminvest Private Group (TIP) – $0.015
Mon 28 Sep: Shine Justice (SHJ) – $0.025, Viva Leisure (VVA) – $0.03, Lindsay Australia (LAU) – $0.017
Tue 29 Sep: Acrow (ACF) – $0.014, DPM Metals (DPM) – $0.042, EVZ (EVZ) – $0.006, Rural Funds Group (RFF) – $0.029, Centuria Industrial REIT (CIP) – $0.043, Centuria Office REIT (COF) – $0.022, Tasmea (TEA) – $0.085, Cadence Capital (CDM) – $0.03, Cadence Opportunities Fund (CDO) – $0.075, Charter Hall Social Infrastructure REIT (CQE) – $0.045, Charter Hall Long Wale REIT (CLW) – $0.064, Charter Hall Retail REIT (CQR) – $0.066, Ram Essential Services Property Fund (REP) – $0.01, Arena REIT (ARF) – $0.045, Waypoint REIT (WPR) – $0.043, iShares S&P Mid-Cap ETF (IJH) – $0.00, iShares S&P 500 ETF (IVV) – $0.00, iShares S&P Small-Cap ETF (IJR) – $0.00
Wed 30 Sep: Staude Capital Global Value Fund (GVF) – $0.033, Nick Scali (NCK) – $0.39, Sims (SGM) – $0.20, Cedar Woods Properties (CWP) – $0.25, Genusplus Group (GNP) – $0.036
Other ASX corporate actions today:
Dividends paid: AGL Energy (AGL), Amcor (AMC), Ariadne Australia (ARA), BSP Financial Group (BFL), Channel Infrastructure NZ (CHI), EVT (EVT), IDP Education (IEL), Iluka Resources (ILU), LGI (LGI), Monadelphous Group (MND), PLS Group (PLS), PWR Holdings (PWH), Ramsay Health Care (RHC), ResMed (RMD), Rio Tinto (RIO), Shriro Holdings (SHM), Telstra Group (TLS), The Lottery Corp (TLC), Universal Store Holdings (UNI)
IPOs: None
AGMs: Suncorp (SUN), 10:00 am
Economic calendar:
No major economic events