Investors stuck firmly with a defensive mindset today, shifting capital away from growth areas of the market like resources. BHP Group (BHP) (-1.6%) was a major drag on the index after it released its September quarter production numbers — revealing a 19% year-on-year fall in copper production. Healthcare stocks like Cochlear (COH) (+5.2%) and Telix Pharmceuticals (TLX) (+2.3%) lead the way.
Be sure to click/scroll through for the usual reporting of the major sector and stock-specific moves, the broker responses to them, as well as all the key economic data in tonight's Evening Wrap. Also, I have detailed technical analysis on the Nasdaq Composite and the S&P/ASX 200 in today's ChartWatch.
Let’s dive in!
Today in Review
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
| ASX 200 | 8,816.9 | -0.33% |
| All Ords | 8,944.2 | -0.35% |
| Small Ords | 3,150.2 | -0.87% |
| All Tech | 2,823.6 | -0.03% |
| Emerging Companies | 2,767.3 | -0.88% |
Currency | ||
| AUD/USD | 0.6983 | +0.04% |
US Futures | ||
| S&P 500 | 7,730.5 | -0.05% |
| Dow Jones | 52,260.0 | +0.15% |
| Nasdaq | 29,602.5 | -0.40% |
Name | Value | % Chg |
|---|---|---|
Sector | ||
| Consumer Staples | 13,792.0 | +1.14% |
| Health Care | 34,269.6 | +0.87% |
| Consumer Discretionary | 3,729.4 | +0.76% |
| Real Estate | 3,252.2 | +0.70% |
| Utilities | 10,696.2 | +0.49% |
| Information Technology | 1,670.5 | +0.36% |
| Communication Services | 1,538.2 | -0.12% |
| Industrials | 8,034.4 | -0.17% |
| Financials | 9,380.7 | -0.48% |
| Materials | 22,881.2 | -1.16% |
| Energy | 11,165.6 | -1.31% |
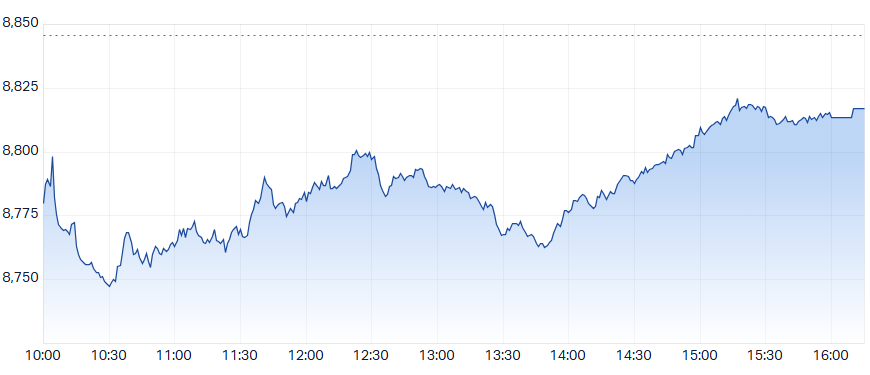
ASX 200 Intraday Chart
Markets
The S&P/ASX 200 (XJO) finished 28.8 points lower at 8,816.9, 0.80% from its session low and 0.33% from its high. Despite the recovering in the benchmark index during the session, in the broader-based S&P/ASX 300 (XKO) advancers lagged decliners miserably by 96 to 180.
The market breadth kinda tells the story today. Well, the market breadth and the mix of sectors that added / recovered enough points to skew the benchmark towards a "respectable" decline.
"Defensives" are sectors that tend to see resilient earnings regardless of the state of the economy or stage of the business cycle. They deal in essentials, like healthcare, consumer staples, utilities, etc. Arguably, the big banks are defensive bloc in our market, given their size and track record for delivering stable fully franked dividends.
Look at some of the sectors that did well today (in a down market):
Consumer Staples (XSJ) (+1.1%)
Health Care (XHJ) (+0.9%)
Utilities (XUJ) (+0.5%)
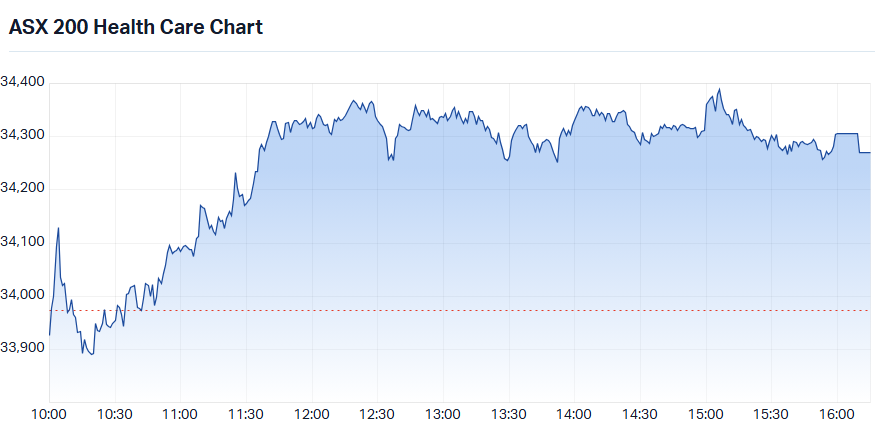
S&P-ASX 200 Health Care Sector Index (XHJ) intraday chart
Sure, Financials (XFJ) (-0.5%) were down, tracking a 0.8% decline in their US counterparts overnight. But consider that they climbed 0.84% from their lows... that's a bunch of important index points added back...
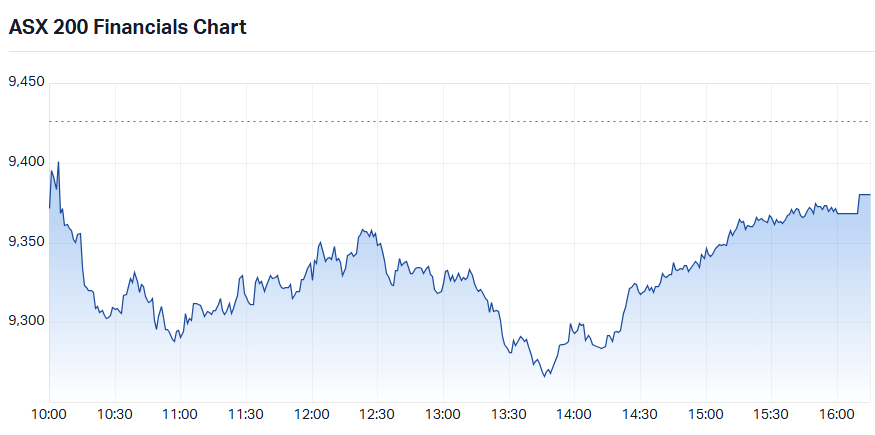
S&P-ASX 200 Financials Sector Index (XFJ) intraday chart
It's great that defensive stocks are strong right now, particularly if you happen to own them, but also due to the support their strength provides the index. But consider that there's usually something not quite right in the local or global economy if investors are allocating capital with a defensive mindset.
We know that a pile of cash from superannuation guarantee flows into the itsy-bitsy-by-global-standards Australian share market each day. It's a pile of cash with few opportunities (and its shrinking with all the takeovers this year!). Yet the cash must go somewhere.
So, we often get days like this where defensives are up and the more growth-oriented areas of the market are weak (i.e., due to all the bad stuff that's troubling those same investors who are diverting cash into defensives!). Take Materials (XMJ) (-1.2%) for example 👇
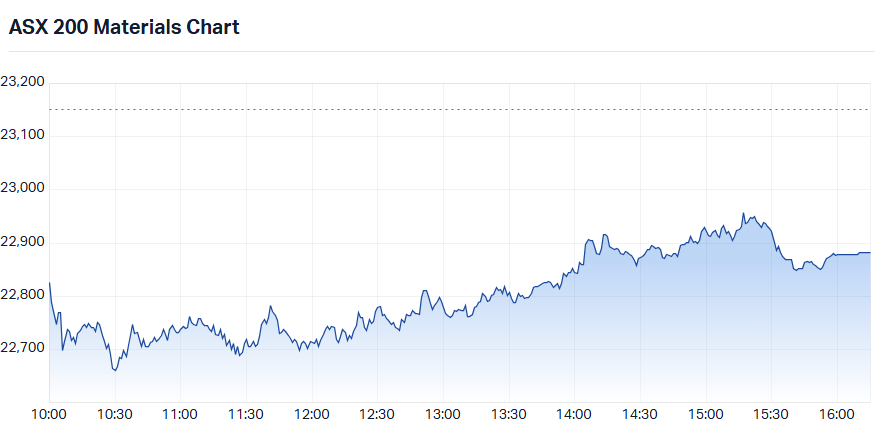
S&P-ASX 200 Materials Sector Index (XMJ) intraday chart
And Energy (XEJ) (-1.3%), although arguably, this is a sector prone to plenty of volatility given current world events.
Consider that if you sell some growth stocks, you end up with cash. That kinda defeats the goal of allocating all that capital coming in. So, you kinda have to buy even more defensive stocks. You're effectively robbing Peter to pay Paul. Alas, such is the nature of the Old Tin Pot! 🤦
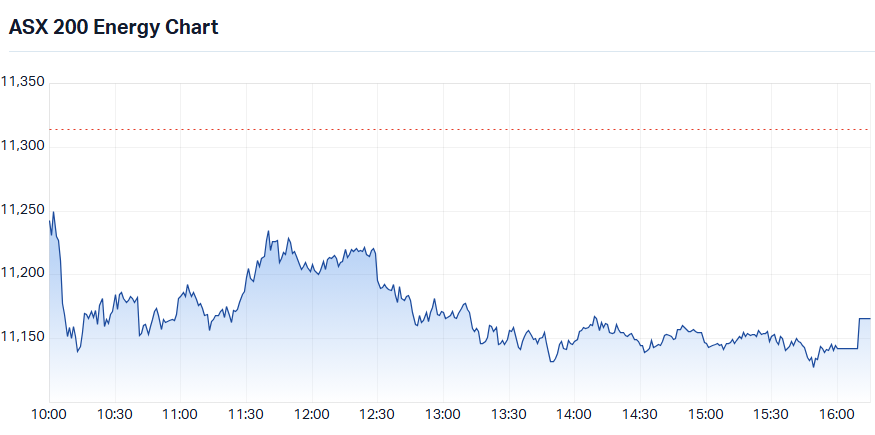
S&P-ASX 200 Energy Sector Index (XEJ) intraday chart
Now, if you've been suffering through my rantings here in the Evening Wrap long enough, you may have started to pick which sectors are likely to prosper or falter on a day depending on which way the winds of global risk appetite are blowing. I hope this is the case!
Consider that stock picking is important, but even the best stock in the worst sector could find itself underperforming an average stock in the best sector. So, it's important to know which sectors the big fund managers are being forced to buy / favouring, and which sectors they're being forced to sell / avoid.
Today's best ASX Top 300 gainers
Company | Last Price | Change $ | Change % | 1mo % | 1yr % |
|---|---|---|---|---|---|
| Ingenia Communities Group (INA) | $4.65 | +$0.41 | +9.7% | +7.6% | -17.3% |
| Austal (ASB) | $4.18 | +$0.27 | +6.9% | -9.9% | -38.1% |
| PWR Holdings (PWH) | $11.11 | +$0.64 | +6.1% | +10.1% | +40.8% |
| Cochlear (COH) | $139.40 | +$6.85 | +5.2% | +4.1% | -51.4% |
| Orora (ORA) | $1.455 | +$0.065 | +4.7% | +4.7% | -27.6% |
| Aura Consolidated Group, Inc. (AXQ) | $3.39 | +$0.14 | +4.3% | -17.9% | -50.5% |
| HUB24 (HUB) | $67.08 | +$2.51 | +3.9% | -4.5% | -37.4% |
| Domino's Pizza Enterprises (DMP) | $22.01 | +$0.81 | +3.8% | +16.6% | +46.4% |
| Lycopodium (LYL) | $21.65 | +$0.72 | +3.4% | -4.5% | +78.5% |
| Generation Development Group (GDG) | $3.15 | +$0.10 | +3.3% | +5.7% | -55.8% |
| L1 Long Short Fund (LSF) | $4.47 | +$0.14 | +3.2% | -8.2% | +28.4% |
| Arena REIT (ARF) | $2.57 | +$0.08 | +3.2% | +20.7% | -34.3% |
| Liberty Financial Group (LFG) | $3.21 | +$0.09 | +2.9% | -1.5% | -24.8% |
| Civmec (CVL) | $1.58 | +$0.04 | +2.6% | -10.7% | +16.6% |
| TPG Telecom (TPG) | $3.83 | +$0.09 | +2.4% | -1.0% | -28.1% |
| Telix Pharmaceuticals (TLX) | $15.76 | +$0.36 | +2.3% | -11.7% | -4.5% |
| Ricegrowers (SGLLV) | $13.98 | +$0.31 | +2.3% | +17.1% | -19.7% |
| WIA Gold (WIA) | $0.455 | +$0.01 | +2.2% | -1.1% | +30.0% |
| Flight Centre Travel Group (FLT) | $11.07 | +$0.23 | +2.1% | +5.5% | -7.1% |
| Mineral Resources (MIN) | $45.46 | +$0.92 | +2.1% | -13.9% | +9.8% |
Today's worst ASX Top 300 losers
Company | Last Price | Change $ | Change % | 1mo % | 1yr % |
|---|---|---|---|---|---|
| Benz Mining Corp (BNZ) | $4.21 | -$0.64 | -13.2% | -10.4% | +137.9% |
| Sunrise Energy Metals (SRL) | $14.40 | -$1.12 | -7.2% | -26.3% | +142.8% |
| Ampol (ALD) | $39.32 | -$2.61 | -6.2% | -8.8% | +32.8% |
| Minerals 260 (MI6) | $0.735 | -$0.04 | -5.2% | -21.8% | +122.7% |
| PDI Gold (PDI) | $4.08 | -$0.22 | -5.1% | -16.9% | +33.8% |
| Stanmore Resources (SMR) | $2.67 | -$0.13 | -4.6% | -0.4% | +19.2% |
| Macmahon Holdings (MAH) | $1.03 | -$0.05 | -4.6% | -4.2% | +116.8% |
| Kingsgate Consolidated (KCN) | $4.42 | -$0.21 | -4.5% | -18.1% | +13.9% |
| GQG Partners Inc. (GQG) | $1.035 | -$0.045 | -4.2% | -3.3% | -35.1% |
| Yancoal Australia (YAL) | $6.04 | -$0.25 | -4.0% | +3.8% | +7.1% |
| 4DMedical (4DX) | $3.73 | -$0.14 | -3.6% | -13.5% | +116.2% |
| Silex Systems (SLX) | $3.52 | -$0.13 | -3.6% | -21.4% | -53.9% |
| Alkane Resources (ALK) | $1.70 | -$0.06 | -3.4% | -13.7% | +57.4% |
| NRW Holdings (NWH) | $6.70 | -$0.23 | -3.3% | -14.8% | +37.0% |
| Megaport (MP1) | $15.41 | -$0.52 | -3.3% | -16.9% | +10.2% |
| GenusPlus Group (GNP) | $8.30 | -$0.28 | -3.3% | -12.3% | +39.7% |
| Virgin Australia Holdings (VGN) | $2.43 | -$0.08 | -3.2% | -10.7% | -30.8% |
| Air New Zealand (AIZ) | $0.31 | -$0.01 | -3.1% | -1.6% | -41.0% |
| Greatland Resources (GGP) | $9.54 | -$0.30 | -3.0% | -13.7% | +14.1% |
| DroneShield (DRO) | $1.49 | -$0.045 | -2.9% | -13.4% | -66.7% |
Chartwatch
Nasdaq Composite Index
Nasdaq Composite Index chart
Analysis
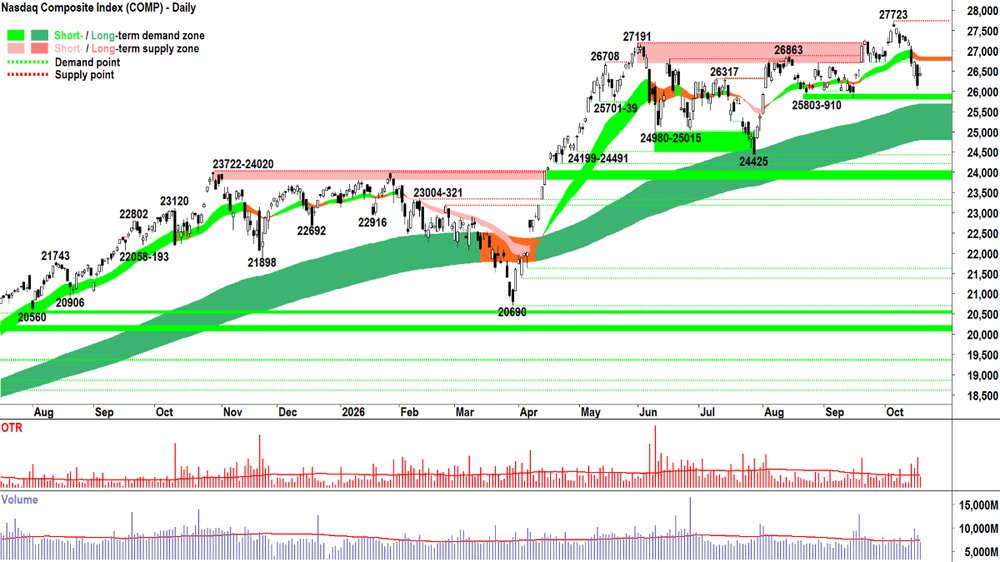
It's not obvious, but that's another zebra day. 🦓 It didn't end long and white, but consider the pop on the open vs Friday's low close.
Friday's candle is a strong supply side showing = MOTN ⬇️.
Yet, as is the nature of the Comp, Monday's traders suffered a little amnesia of Friday's woes and bought the dip.
We can say that the upward pointing shadow of Monday's candle suggests the demand side was eventually met with some opposition, but net-net, it's still a solid demand side win.
Another strong performance tonight would set Friday's low of 26023 as a trough, and solidify 25803-25910 as a credible zone of excess demand. From there, one could easily see the Comp recover and eventually take a look at the 27723 all-time high.
It's conceivable.
But so too is the scenario where a test / fail of the short term trend ribbon confirms latent supply building at higher prices — and a new STR mentality among investors. That RUT chart remains the elephant in the room, and it arguably got worse last night — not better (tell me what you think of its Monday candle!). ⚠️🚨
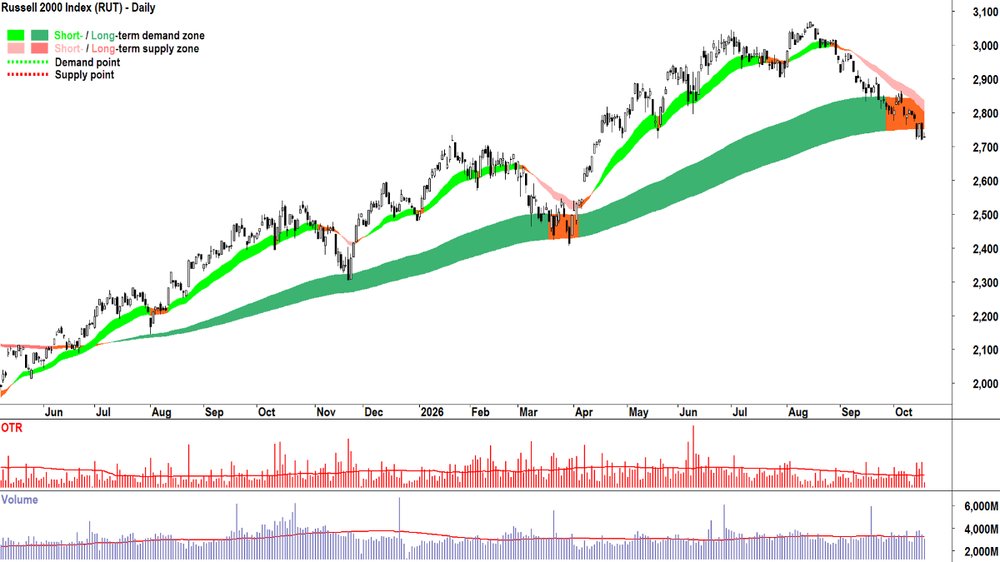
Multiple choice question: The Russell 2000 chart is a A) Concern | B) Trainwreck! 💥🚂
Hopefully you agree after suffering through my rants here for some time, that MOTN, we don't do a whole lot when it comes to portfolio risk. It's a steady-as-she-goes, wait for the irrefutable evidence sort of thing... We must be convinced by the trends, price action, candles, volatility and volume that a new course of action is required.
There are no whims. There are no gut feelings. There's no emotion. Just: Analyse, Accept, Act.
And on that basis, Monday's technicals give me no reason to Act!
View
I am 1/2RP on US stocks (RP = Risk Position – it reflects my personal allowable capital allocation limit for my investments in US stocks. So 1/2RP is 50%, 2/3RP is 67% and FRP is 100%).
Key Levels
27723 is the closest key point of supply, but the short term trend ribbon will also likely act as a dynamic zone of supply (presently 26772-26888). 25803-910 as the closest key zone of demand.
S&P/ASX 200 (XJO)
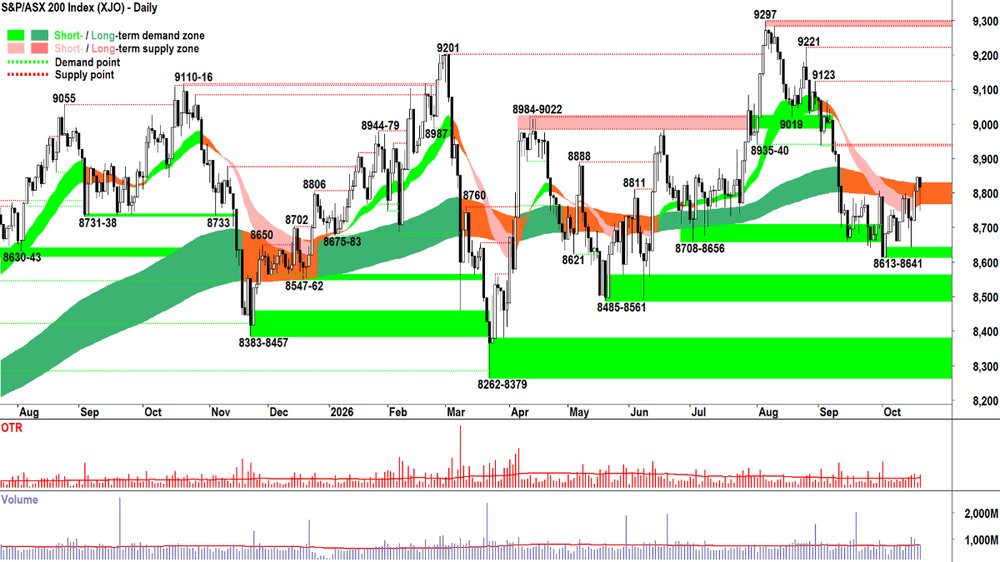
S&P/ASX 200 (XJO) chart
Analysis
Three solid demand side candles... and one more very decent showing today (i.e., the downward pointing shadow = BTD).
The OTP is showing some impressive resilience that many other major global stock indices are lacking. Say that sentence over a few times... Yes, the OTP is behaving very solidly at the moment!
Can I go so far as to say that today's comeback even had me thinking about a move back to 1/2RP for a little while there...
But... double-amber on the trend ribbons. Price action that's rising peaks and rising troughs, granted, but with sufficient overlap to warrant caution. Mixed candles, arguably even after the last four demand side showings — and as good as today's candle was, look at the market breadth in the ASX 300: 96 ⬆️ vs 180 ⬇️.
Which means it's pass on adding risk for me today. But I'm open to using the full extent of my current 1/3RP allocation — skewed towards long exposure, with a few strategic shorts in the mix for insurance.
Now throw in the fact that since I left, cash rates have risen close to 5%... 🤔
And it feels like cash isn't such a terrible place to be right now! 💰
View
I am 1/3RP on Australian shares (i.e., 67% cash vs 33% invested, with some of the invested portion allocated to shorts).
Key Levels
8935-8940 is the closest zone of supply vs 8613-8641 is the critical zone of demand.
(Glossary of acronyms! Old Tin Pot (OTP): S&P/ASX 200 | MOTN: More Often Than Not | FOMO: Fear Of Missing Out | HOFU: Holding On For Upside | BTD: Buy The Dip | NUTE: No Urgency To Enter | FOHO: Fear Of Holding On | STR: Sell The Rally | RP: Risk Position | FFS: Fund Flow Shenanigans!)
ChartWatch LIVE Webinars – RETURN ON WEDS 28 OCT @ 12pm AEDT!!!
Learn more about technical analysis and trend following through real case studies on ASX stocks. Australia's premier technical analyst, Carl Capolingua, shares his unique insights on stocks as requested by viewers. Ask about a company in your portfolio or anything related to trading and investing and get Carl's expert opinion.
Places are limited so >REGISTER NOW!<
Economy
TODAY
TUESDAY
12:00 CHN People's Bank of China ("PBOC") Loan Prime Rates
1-year LPR: No change as forecast, unchanged at 3% p.a.
5-year LPR: No change as forecast, unchanged at 3.5% p.a.
LATER THIS WEEK
TONIGHT
23:30 USA September Building Permits & Housing Starts
Building Permits: 1.39 million forecast vs 1.4 million in August
Housing Starts: 1.3 million forecast vs 1.28 million in August
WEDNESDAY
No major economic announcements scheduled for Wednesday
THURSDAY
No major economic announcements scheduled for Wednesday
FRIDAY
09:00 AUS Flash October Purchasing Managers Index ("PMI")
Manufacturing: no forecast available vs 49.6 previous (revised up from 49.3)
Services: no forecast available vs 51.9 previous (revised up from 51.4)
SATURDAY
09:00 USA Flash October PMI's
Manufacturing: 55.5 forecast vs 55.9 previous (revised down from 57.0)
Services: 58.0 forecast vs 58.8 previous (revised up from 58.7)
Interesting Movers
Trading higher
- Corporate Travel Management (CTD) $3.06+23.4%
IATA has released the $65 million security guarantee provided by CTM and restored the company’s previous settlement cycles. Restoration is expected to improve working capital by approximately $30 million.
- Dateline Resources (DTR) $0.09+12.1%
No news, was up 9.2% yesterday also... below average volume both days though. 🤔
- Ingenia Communities Group (INA) $4.65+9.7%
Updated market on Warburg Pincus' $5.25 takeover bid for the company, noting “considerable progress” had been made in finalising terms. Deadline extended to Friday as Warburg continues to conduct due diligence. Ingenia Board intends to abandon its bid for Peet (PPC) — a key requirement of its own acquisition.
- CuFe (CUF) $0.06+9.6%
Entered a binding conditional Share Sale Agreement to acquire 100% of Gecko Mining (i.e., the remaining 45% interest in the Tennant Creek Copper Project) for a consideration of 1.6 billion new fully paid CuFe shares. Completion subject to due diligence, CuFe shareholder, and regulatory approvals.
- Core Lithium (CXO) $0.21+6.3%
No news. Performance reflected general weakness in the broader lithium sector. Sector fell yesterday as benchmark lithium carbonate futures rose late afternoon in China. Possibly a delayed response.
- PWR Holdings (PWH) $11.11+6.1%
Provided a Q1 update at the AGM. Management noted a positive start to FY27 with shipments on the follow-on US Government order and Ford S650 program commencing in July. Outlook revised upwards with A&D revenue growth now expected around 50% (up from 30%), driven by a recently secured US$4.6m pre-contract order. Management now expects FY27 statutory NPAT margin of 12.5%.
- Gentrack Group (GTK) $3.50+5.4%
Announced that Hydro Tasmania owned energy retailer Momentum Energy has contracted to use GTK’s g2 billing solution to support its 200,000-plus residential and business meter points across Australia.
- Waratah Minerals (WTM) $0.79+5.4%
Reported partial assay results from first drill hole GCD001 at Goldenclad: 83 m of gold mineralisation from 6 m including 42 m @ 2.23 g/t Au (partial assays from 0–100 m).
- Cochlear (COH) $139.59+5.3%
No news. Performance reflected general weakness in the broader healthcare sector.
- EBR Systems Inc (EBR) $0.15+5.2%
Submitted a TGA ARTG application for its WiSE® System; expected to be assessed under Priority Review, the next regulatory step toward potential market entry in Australia, supported by clinical data and U.S. FDA approval.
- HUB24 (HUB) $67.08+3.9%
Posted net inflows of $4 billion in the September quarter (down 23% vs prior corresponding period but ahead of consensus forecast of $3.8 billion). Total funds under administration ("FUA") grew 15% to $168.6 billion and platform FUA grew 18% to $143.7 billion. Management noted a “strong start" to FY27 amid a “subdued macroeconomic environment.”
- PLS Group (PLS) $2.99+2.9%
Announced it intends to offer, subject to market and other conditions, up to an aggregate principal amount of US$700M Senior Unsecured Notes due 2032. The Notes will be offered only to persons reasonably believed to be qualified institutional buyers. PLS intends to use the net proceeds for general corporate purposes, including but not limited to capital expenditure and/or other growth opportunities.
Trading Lower
- Starpharma Holdings (SPL) $0.50-33.3%
Announced it has secured majority ownership of Petalion, increasing its equity interest from 22.5% to 66%> SPL will contribute up to AUD $5.0 million (AUD $3.0 million in cash and the balance in R&D services) to advance the FAP-targeted DEP® oncology program and will lead its development. Medicxi will retain a 30% interest, board representation, and an active strategic role.
- Benz Mining Corp (BNZ) $4.27-12.0%
No news, sharp pullback after yesterday's news regarding drilling results at the company's Glenburgh Gold Project in Western Australia.
- WAM Active (WAA) $0.89-9.7%
Announced an NTA update. Estimated pre-tax NTA is $0.84 per share before the payment of a fully franked final dividend of 3.2 cents per share (ex-dividend on 17 November) and a special fully franked dividend of 2.0 cents per share (ex-dividend on 4 December). Management said that "Equity markets have experienced heightened volatility during October, with selling pressure particularly pronounced across small-cap resources and technology companies."
- Peet (PPC) $1.43-8.1%
No news from the company itself, but note above item regarding Ingenia Communities takeover by Warburg whereby INA is required to drop its bid for Peet.
- Audinate Group (AD8) $1.91-5.5%
The company held its AGM today. No major new updates to FY27 outlook or current run rate in CEO's presentation may have disappointed some investors. Reaffirmed guidance that results will be 'in line or slightly ahead" of FY26's numbers. AD8 is one of the most featured stocks in the history of ChartWatch ASX Scans Downtrends List. 📉😭
- Stanmore Resources (SMR) $2.67-4.6%
No news. Performance reflected general weakness in the broader coal sector.
- National Australia Bank (NAB) $38.82-2.7%
Says it will slash 2,500 jobs (about 6% of the workforce), including 1,500 by end-December, as part of a broader review to simplify the operating model, reduce consultants/external contractors and better align the workforce to growth and technology initiatives.
- BHP Group (BHP) $59.50-1.6%
Delivered September quarter operational review — copper production decreased 19% to 401,000 tonnes due to lower planned concentrator feed grades, planned maintenance and severe weather in Chile. Full-year guidance, however, remained unchanged. Pilbara iron ore output rose 4%, steelmaking coal was up 1%, and NSW energy coal was up 26%.
Broker Moves
Company | Broker | Action | Rating | Price Target |
|---|---|---|---|---|
AAIAlcoa Corporation | Ord Minnett | Retained | Buy | $80.00 |
AELAmplitude Energy | Morgans | Retained | Buy | $2.70(from $2.90) |
ANZANZ Group Holdings | Morgan Stanley | Retained | Overweight | $35.50 |
ARBARB Corporation | Morgans | Retained | Buy | $25.90(from $27.85) |
ARFArena REIT | UBS | Upgraded | Buy(from Neutral) | $2.92(from $2.60) |
BENBendigo and Adelaide Bank | Macquarie | Retained | Underperform | $8.50(from $9.00) |
| Morgan Stanley | Retained | Underweight | $9.80 | |
BHPBHP Group | Citi | Retained | Neutral | $64.40 |
BLXBeacon Lighting Group | Citi | Retained | Neutral | $1.97 |
CBACommonwealth Bank of Australia | Morgan Stanley | Retained | Underweight | $125.00(from $124.00) |
CGFChallenger | Citi | Retained | Buy | $13.20(from $11.55) |
| UBS | Downgraded | Neutral(from Buy) | $12.25(from $11.50) | |
CGSCogstate | Bell Potter | Retained | Buy | $4.05(from $3.70) |
COHCochlear | Citi | Retained | Neutral | $140.00 |
CSLCSL | Citi | Retained | Neutral | $180.00 |
CWYCleanaway Waste Management | Morgans | Downgraded | Hold(from Buy) | $2.95 |
DNLDyno Nobel | Morgan Stanley | Upgraded | Overweight(from Equal Weight) | $4.80(from $3.50) |
EOSElectro Optic Systems Holdings | Canaccord Genuity | Retained | Buy | $17.00(from $15.00) |
FHEFrontier Energy | Canaccord Genuity | Initiated | Speculative Buy | $0.29 |
FPRFleetPartners Group | Macquarie | Downgraded | Neutral(from Outperform) | $5.30(from $3.43) |
| Morgan Stanley | Retained | Equal Weight | $4.65 | |
HUBHUB24 | Citi | Retained | Buy | $88.00(from $93.50) |
| UBS | Retained | Buy | $77.75(from $77.35) | |
IMDImdex | Macquarie | Retained | Outperform | $5.15(from $5.00) |
INNInnovaero Technologies | Canaccord Genuity | Initiated | Buy | $1.00 |
MSVMitchell Services | Morgans | Upgraded | Speculative Buy(from Accumulate) | $0.80(from $0.60) |
NABNational Australia Bank | Morgan Stanley | Retained | Underweight | $34.00 |
NEMNewmont Corporation | Citi | Retained | Buy | $200.00(from $215.00) |
NHCNew Hope Corporation | Barrenjoey | Upgraded | Neutral(from Underweight) | $6.40(from $5.20) |
| Bell Potter | Retained | Sell | $5.30(from $5.00) | |
PLSPLS Group | Ord Minnett | Retained | Buy | $4.40(from $5.00) |
QANQantas Airways | UBS | Retained | Buy | $11.40(from $11.60) |
RHCRamsay Health Care | Macquarie | Downgraded | Neutral(from Outperform) | $55.60(from $54.20) |
RRLRegis Resources | Citi | Retained | Neutral | $7.90 |
S32South32 | Citi | Retained | Buy | $6.10 |
| Macquarie | Retained | Neutral | $5.00 | |
SCGScentre Group | Citi | Retained | Buy | $4.10 |
SGPStockland | Citi | Retained | Buy | $5.40 |
| UBS | Retained | Buy | $5.01(from $5.12) | |
SIGSigma Healthcare | Bell Potter | Downgraded | Hold(from Buy) | $3.00 |
SLCSuperloop | Ord Minnett | Initiated | Buy | $2.97 |
TLXTelix Pharmaceuticals | Citi | Retained | Buy | $31.00 |
VGNVirgin Australia Holdings | UBS | Retained | Buy | $4.10 |
WA1WA1 Resources | Canaccord Genuity | Retained | Speculative Buy | $34.00 |
WBCWestpac Banking Corporation | Morgan Stanley | Retained | Underweight | $30.00 |
WOWWoolworths Group | UBS | Retained | Sell | $40.00(from $39.50) |
WTMWaratah Minerals | Bell Potter | Retained | Speculative Buy | $1.45(from $1.25) |
XROXero | Citi | Retained | Buy | $91.55 |
Scans
Top Gainers
Code | Company | Last | % Chg |
|---|---|---|---|
| BWF | Blackwall Ltd | $0.12 | +30.44% |
| EAX | Energy Action Ltd | $0.40 | +26.98% |
| CTD | Corporate Travel Management Ltd | $3.06 | +23.39% |
| EM3 | Emc Gold Corporation | $0.11 | +20.88% |
| RCE | Recce Pharmaceuticals Ltd | $0.35 | +20.69% |
Top Fallers
Code | Company | Last | % Chg |
|---|---|---|---|
| NAG | Nagambie Resources Ltd | $0.012 | -33.33% |
| SPL | Starpharma Holdings Ltd | $0.50 | -33.33% |
| GDM | Great Divide Mining Ltd | $0.23 | -20.69% |
| RMI | Resource Minerals International Ltd | $0.10 | -20.00% |
| AUG | Augustus Minerals Ltd | $0.03 | -18.92% |
52 Week Highs
Code | Company | Last | % Chg |
|---|---|---|---|
| WAT | Waterco Ltd | $6.86 | +3.94% |
| ALV | Alvo Minerals Ltd | $0.10 | +3.09% |
| APA | APA Group | $11.46 | +1.33% |
| WOW | Woolworths Group Ltd | $41.61 | +1.09% |
| IAG | Insurance Australia Group Ltd | $8.67 | +0.70% |
52 Week Lows
Code | Company | Last | % Chg |
|---|---|---|---|
| GDM | Great Divide Mining Ltd | $0.23 | -20.69% |
| CAZ | Cazaly Resources Ltd | $0.016 | -15.79% |
| ATH | Alterity Therapeutics Ltd | $0.27 | -15.63% |
| DBO | Diablo Resources Ltd | $0.011 | -15.39% |
| FRB | Firebird Metals Ltd | $0.10 | -14.89% |
Near Highs
Code | Company | Last | % Chg |
|---|---|---|---|
| PCI | Perpetual Credit Income Trust | $1.09 | +0.93% |
| WVOL | iShares MSCI World Ex Aust Minimum Volatility ETF | $47.06 | -0.59% |
| IAGPF | Insurance Australia Group Ltd | $105.55 | +0.71% |
| GCI | Gryphon Capital Income Trust | $2.01 | 0.00% |
| VVLU | Vanguard Global Value Equity Active ETF | $81.69 | -0.78% |
Relative Strength Index (RSI) Oversold
Code | Company | Last | % Chg |
|---|---|---|---|
| RAC | Racura Oncology Ltd | $1.59 | +2.91% |
| FFM | Firefly Metals Ltd | $1.355 | -1.46% |
| MLX | Metals X Ltd | $1.60 | -2.14% |
| NVA | Nova Minerals Corp | $0.385 | -2.53% |
| GLN | Galan Lithium Ltd | $0.225 | 0.00% |