In a nutshell:
A chip-led rebound lifted Wall Street as CoreWeave's upbeat outlook revived the AI trade, while Microsoft slipped on Anthropic's push into office software
Rate-hike nerves lingered with US cash bonds shut for Veterans Day, leaving the 10-year yield near 5% and economists adding to Fed hike calls
Oil snapped a two-day slide as US-Iran peace efforts showed little progress, while European shares closed at a record
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,619 | +1.31% |
Dow Jones | 52,486 | +0.49% |
NASDAQ Comp | 25,466 | +1.60% |
Russell 2000 | 2,846 | +0.87% |
Global Indices | ||
 S&P/TSX | 36,412 | +0.67% |
 Shanghai Composite | 3,681 | +0.46% |
 DAX | 26,663 | +1.20% |
 Hang Seng | 24,316 | -0.98% |
 Nifty 50 | 81,879 | +0.95% |
 Nikkei 225 | 61,249 | +1.31% |
 FTSE 100 | 10,835 | +0.78% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 3,985.4 | -1.17% |
 Copper | 6.25 | +0.48% |
 WTI Oil | 86.36 | +0.37% |
Currency | ||
 AUD/USD | 0.6849 | -0.25% |
Cryptocurrency | ||
 Bitcoin (USD) | 74,587 | +1.11% |
 Ethereum (AUD) | 3,032 | +0.81% |
Miscellaneous | ||
US 10 Yr T-bond | 4.998 | +0.30% |
VIX | 17.52 | -9.97% |
US Sectors
Sector | % Chg |
|---|---|
| Information Technology | +2.71% |
| Energy | +1.83% |
| Industrials | +1.32% |
| Communication Services | +0.91% |
| Financials | +0.59% |
| Consumer Staples | +0.53% |
Sector | % Chg |
|---|---|
| Materials | +0.45% |
| Utilities | +0.26% |
| Health Care | +0.06% |
| Real Estate | +0.03% |
| Consumer Discretionary | -0.36% |
S&P 500 Session Chart
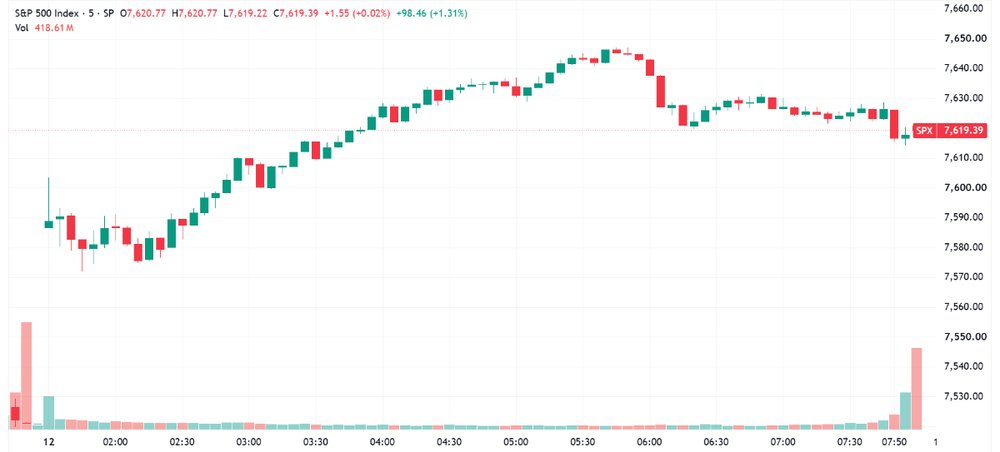
S&P 500 trends higher, closes off best levels (Source: TradingView)
Overnight Markets
Major US benchmarks mostly higher, but off best levels as a chip-led bounce lifts the S&P 500 and Nasdaq, while the Dow lagged
Chipmakers did the heavy lifting, the Philadelphia Semis index up 5.6% to a one-week high after CoreWeave's results eased worries about bloated AI spending
Nasdaq now up 4.6% in the last four sessions, recovering almost the entirety of the 5-Nov selloff where it tumbled 5.5%
US cash Treasury market shut for Veterans Day, leaving the 10-year yield hovering near 5% after Tuesday's hot CPI print fuelled bets on more Fed hikes (YF)
European shares climbed to a record, the Stoxx 600 topping its August closing high as miners and tech rallied on renewed AI optimism (BBG)
Analysts trimmed 2027 S&P 500 profit forecasts for a fourth straight week, now seeing 20% growth versus 30% this year as AI spending and midterm fallout cloud the outlook, per Bloomberg Intelligence (BBG)
AI whiplash is testing Wall Street's dip-buying habit, after the S&P 500 resumed declines Tuesday following last Thursday's 4.4% plunge, its biggest since the 2025 trade war (BBG)
Anthropic's IPO book is several times oversubscribed, with pricing expected on 18 November and trading as soon as 19 November at a targeted $1.4tn valuation (YF)
Retail investors could pour a record $250m into Anthropic on debut, more than double SpaceX's $118m first-day retail buying, says Vanda Research (YF)
Stocks
Nvidia rose for the first time since CEO Jensen Huang admitted an affair with a suspected Chinese spy, despite a Baird downgrade to neutral, but remains down about 14% in November (YF)
CoreWeave jumped 24% to a near two-week high after saying it expects to turn profitable on an adjusted basis in the first half of 2028 (YF)
Memory makers Sandisk and Micron both up 12-13% as CoreWeave's results pulled investors back into the AI trade (CNBC)
Microsoft fell again, bucking the tech rebound, after Anthropic launched Claude Sheets and other workplace tools that compete with Excel and Microsoft 365 (YF)
Geopolitics
Congress is set to subpoena Nvidia's Jensen Huang over his affair with an alleged Chinese spy if he doesn't agree to a closed-door briefing, says House China committee chair Moolenaar (BBG)
Russia and Ukraine agreed a large prisoner-of-war exchange as two days of US-brokered talks in Abu Dhabi ended without a broader breakthrough (AP)
Oil snapped a two-day decline as traders weighed the outlook for ending the US-Iran war, with Trump saying more strikes weren't needed but talks showing little progress (BBG)
Iran asked the UN and IAEA to condemn a US reward of up to $20m for information on its nuclear program, saying it risks encouraging the targeting of nuclear scientists (BBG)
European gas futures pushed above €85 a megawatt-hour, extending gains as Iran war talks stalled and Europe’s low winter stockpiles began to fall (BBG)
Tariffs
Canada's ambassador to the US warned Trump's tariffs are lifting investment costs and discouraging expansion, as new Fed research points to more US consumer price rises next year (CNBC)
Central Banks
Wall Street economists add to Fed hike calls after a third straight hot inflation print, with some weighing bigger moves as a December hike is all but locked in (YF)
Economy
Germany's October inflation was confirmed at 2.8% year-on-year, down from 3.3% in September as a temporary fuel tax cut took effect
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Strategic Metals | 53.115 | +2.46% |
| Lithium & Battery Tech | 61.1075 | +1.88% |
| Uranium | 33.63 | +1.45% |
| Copper Miners | 73.45 | +0.80% |
| Steel | 100.195 | +0.47% |
| Gold Miners | 85.22 | -1.47% |
| Silver Miners | 77.72 | -1.51% |
Industrials | ||
| Aerospace & Defense | 73.27 | +1.27% |
| Construction | 89.37 | +0.77% |
| Agriculture | 26.355 | +0.36% |
| Global Jets | 30.18 | -0.03% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 218.14 | +0.44% |
Renewables | ||
| Hydrogen | 35.2887 | +3.97% |
| Solar | 43.95 | +1.01% |
Technology | ||
| Semiconductor | 155.4 | +6.01% |
| Cloud Computing | 26.5 | +2.32% |
| Robotics & AI | 32.23 | +2.09% |
| Data Center & Digital Infrastructure | 25.87 | +1.97% |
| Cybersecurity | 45.71 | +1.85% |
| Electric Vehicles | 29.557 | +1.73% |
| FinTech | 24.63 | +1.48% |
ASX Today
Orica posts FY26 NPAT pre-significant items of $589.7m, up 9%, with EPS of 126.8 cents a 3.9% beat on ests. Statutory NPAT of $264.2m after $325.5m of significant items. Final dividend of 35.5 cents takes the full year to 64 cents, up 12% (ORI)
Rio Tinto shortlists five bidders for its $7bn energy infrastructure portfolio, with Blackstone and Ares chasing the lot while Brookfield targets Canada and GIP and IFM focus on the Pilbara assets. Binding offers due in the first week of December (AFR)
Xero lifts FY27 revenue guidance to NZ$3,770-3,830m from NZ$3,620-3,730m and announces a $1bn buy-back. H1 revenue rose 46% to NZ$1.7bn on 226,000 net customer adds, with adjusted EBITDA up 3% to NZ$362m or 23% pro-forma (XRO)
What To Watch Today
Not a whole lot. Markets are settling down after the recent bout of volatility. Semis and tech are catching a bounce off CoreWeave’s earnings and the highly anticipated Anthropic IPO later this month, while defensives like Healthcare, REITs and Utilities traded flattish overnight.
Yields and the US dollar. The US bond market was closed for Veterans Day, but the 2-year still ran up 27 bps across the previous three sessions, with 18 bps of that from Tuesday’s hotter-than-expected October CPI print. Yields look like they’re back on the rise after topping out in late September. The US Dollar Index broke out overnight, up 0.7% to 102.92 and the highest since April 2025, which usually weighs on commodities and equities. Gold is down 1.1% to US$3,984/oz, so expect a bit of softness for local resources.
A busy day for off-cycle earnings and AGMs. Aristocrat, Graincorp, Orica and Xero all report, with Graincorp up around 50% since July on upgrades to national wheat crop forecasts. Corporate Travel and Inghams hold AGMs, with CTD surging 58% since 3-Sep, when it crashed 85% on returning from a year-long trading suspension.
Cya in two weeks! I (Kerry) will be back on Monday, 30 November, after a little Hong Kong/China trip with the family. My colleague Joe will be looking after the wrap and blog in the meantime. As always, thanks for tuning in and hopefully markets don't fold while I'm away.
Key Events
Stocks trading ex-dividend:
Thu 12 Nov: ANZ Group (ANZ) – $0.83, Dominion Income Trust 1 (DN1) – $0.687
Fri 13 Nov: Dicker Data (DDR) – $0.115
Mon 16 Nov: Plato Income Maximiser (PL8) – $0.006, Spheria Emerging Companies (SEC) – $0.011, WAM Alternative Assets (WMA) – $0.03
Tue 17 Nov: Global Masters Fund (GFL) – $0.15, L1 Global Long Short Fund (GLS) – $0.02, L1 Long Short Fund (LSF) – $0.039, Solaris Australian Equity Income Plus (SET) – $0.007, WAM Active (WAA) – $0.032, WAM Income Maximiser (WMX) – $0.007, WAM Leaders (WLE) – $0.048
Wed 18 Nov: None
Thu 19 Nov: Rand Mining (RND) – $0.10, Tamawood (TWD) – $0.105, Tribune Resources (TBR) – $0.20
Other ASX corporate actions today:
Earnings: Aristocrat Leisure (ALL), GrainCorp (GNC), Orica (ORI), Xero (XRO)
IPOs: Capability X (CX8) at 12:00 pm
AGMs: Computershare (CPU), Corporate Travel Management (CTD), Inghams Group (ING)
Economic calendar (AEDT):
6:00 pm: UK GDP