In a nutshell:
Major US benchmarks finished slightly higher, recovering early loses to finish near best levels
A rebound in Treasuries pulled the 10-year yield back from its highest since 2002 and overshadowed energy-driven inflation worries
Trump said ramped-up strikes on Iran are "possible" after November's midterms pushing Brent back above US$102 a barrel, having rejected a Tehran proposal to reopen Hormuz in exchange for concessions including an end to the US blockade of Iranian ports
AI dealmaking stayed front and centre, with Anthropic reportedly targeting a mid-November IPO and its prospectus revealing a $42bn Broadcom financing line
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,666 | +0.19% |
Dow Jones | 50,927 | +0.04% |
NASDAQ Comp | 26,872 | +0.04% |
Russell 2000 | 2,807 | +0.35% |
Global Indices | ||
 S&P/TSX | 35,155 | -0.23% |
 Shanghai Composite | 3,842 | +0.31% |
 DAX | 24,939 | -1.03% |
 Hang Seng | 24,613 | +0.37% |
 Nifty 50 | 71,910 | -0.79% |
 Nikkei 225 | 68,957 | +3.30% |
 FTSE 100 | 10,428 | -1.68% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,173.43 | +0.38% |
 Copper | 6.51 | -0.69% |
 WTI Oil | 92.87 | +2.71% |
Currency | ||
 AUD/USD | 0.6927 | -0.04% |
Cryptocurrency | ||
 Bitcoin (USD) | 84,723 | +1.31% |
 Ethereum (AUD) | 3,895 | +0.63% |
Miscellaneous | ||
US 10 Yr T-bond | 5.237 | -1.06% |
VIX | 16.39 | +0.31% |
US Sectors
Sector | % Chg |
|---|---|
| Energy | +1.92% |
| Industrials | +1.00% |
| Information Technology | +0.76% |
| Utilities | +0.61% |
| Financials | +0.16% |
| Consumer Discretionary | -0.15% |
Sector | % Chg |
|---|---|
| Consumer Staples | -0.29% |
| Materials | -0.45% |
| Real Estate | -0.62% |
| Communication Services | -1.19% |
| Health Care | -1.30% |
S&P 500 Session Chart
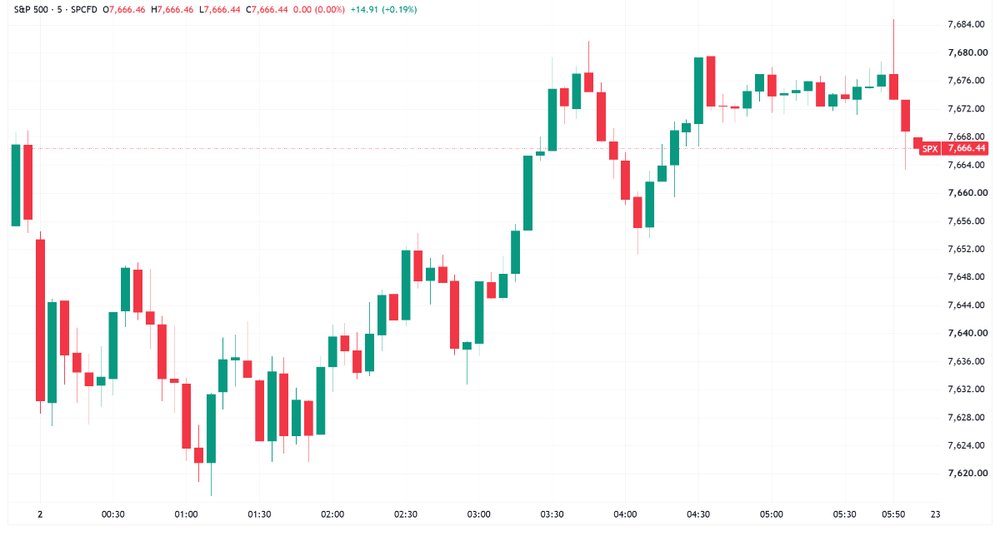
S&P 500 recovered early loses to finish near best levels (Source: Trading View)
Overnight Markets
Major US benchmarks finished higher, clawing back early losses as Treasury yields turned lower by late morning, with the S&P 500 reversing a 0.45% decline to finish 0.2% higher, and snapping a three-day losing streak
Treasuries recovered from a punishing global bond rout, with the rate sensitive US 2-year falling 10 bps to 4.79%, and the US 10-year pulling back from its 2002 high
US Dollar continued its four day ascent with a 0.5% gain to 102, adding to the 3.3% gain since 10 September
Anthropic is seeking to list as soon as mid-November after pushing back its IPO plans, with formal marketing possibly starting the week of 9 November and prospective investors pegging fair value at $1.8tn to $2tn (BBG)
French lawmakers were due to open debate on the 2027 budget about six months before presidential elections, with the CAC40 on track for its deepest annual underperformance versus the Stoxx 600 since 2010 (BBG)
A Bloomberg MacroScope column said Treasuries appear good value relative to equities, growth and the global cycle, but warned history suggests further losses before the market is oversold enough to rebound sustainably (BBG)
Wells Fargo Investment Institute's Tracie McMillion said corporate earnings have stayed resilient despite headwinds, with the key question being whether that strength can persist while borrowing costs remain elevated (YF)
Stocks
Micron guided fiscal Q1 revenue to about $61.5bn, well above $56.8bn ests, and adjusted EPS of $38.15, about 6% above ests, but warned rising staff compensation would weigh on margins as AI-driven memory demand outstrips supply. Shares rose about 3% on Thursday (BBG)
Nike Q1 FY27: revenue fell 4% to $11.21bn, short of $11.32bn ests, as Greater China sales slumped 26%, while EPS of 48c beat ests by about 12%. Nike guided to a high-single-digit revenue decline for fiscal 2027, shares fell about 4% after hours, down more than 40% this year (CNBC)
Accenture fiscal Q4: revenue rose about 6% to $18.7bn, above the top of its $17.8bn to $18.4bn guidance range and $18.3bn ests, while EPS of $3.29 also topped ests. Shares of the IT services giant soared 16% (CNBC)
Alphabet lost 1.7% after Google launched Gemini 4 Argon, touting stronger coding and cybersecurity performance, with Jefferies noting launch pricing of $2 per 1m input tokens and $10 per 1m output tokens sits well below comparable Anthropic offerings (YF)
Broadcom agreed to lend Anthropic up to $42bn to lease its chips, according to Anthropic's IPO prospectus, with the AI lab expected to become Broadcom's largest compute customer in 2027 (RT)
Geopolitics and Iran
The Pentagon may soon deploy an extra aircraft carrier and 10,000 sailors and Marines to the Persian Gulf, a US official said, which would widen military options if Trump steps up strikes on Iran (BBG)
Trump said ramped-up strikes on Iran are "possible" after November's midterms, having rejected a Tehran proposal to reopen Hormuz in exchange for concessions including an end to the US blockade of Iranian ports (BBG)
The US Treasury sanctioned more of Russia's A7 network, a financial firm accused of using shell companies to move money for sanctioned businesses including in Iran, as Washington seeks to cut off Iran's economy (BBG)
PetroChina has reportedly pulled several gasoline and jet fuel cargoes scheduled for October export as Beijing seeks to preserve domestic inventories, tightening refined product supply already strained by the Iran war (TE)
Central Banks
Minneapolis Fed President Neel Kashkari said he expects more rate hikes to restrain the economy into 2027, but has no strong view on whether the next should come at the 27-28 October meeting (RT)
BoE policymaker Catherine Mann said a rate hike is needed to manage inflation risks and protect credibility, arguing officials cannot simply rely on markets pricing as many as four increases by next summer (BBG)
Tariffs
USTR Greer hosted G20 trade ministers in Milwaukee, their first gathering since Washington imposed sweeping tariffs on dozens of partners over alleged failures to enforce forced-labour bans, as some Trump tariffs faced fresh legal scrutiny (BBG)
Economy
ISM manufacturing PMI eased to 54.5 in September against 55.0 ests, but the prices paid gauge jumped 6.8 points to 77.9, well above 73.0 ests and the highest since May (TS)
US initial jobless claims slipped 1,000 to 197,000 in the week to 26 September, the lowest since July and below 200,000 ests, while continuing claims fell to a three-year low (BBG)
S&P Global's US manufacturing PMI rose to its highest since May 2022 in September as a surge in new orders pushed factories to lift output sharply and add workers, chief business economist Chris Williamson said (YF)
US companies' announced layoff plans fell in September to the lowest for the month since 2022, Challenger, Gray & Christmas said, though firms are not rushing to add holiday staff (YF)
Japan's Tankan index for large manufacturers rose to 24 from 22, the highest since March 2018 and a sixth straight quarterly gain, though short of 25 ests, suggesting the BoJ can keep raising rates (BBG)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Lithium & Battery Tech | 68.22 | -0.29% |
| Steel | 101.814 | -0.44% |
| Silver Miners | 85.63 | -0.44% |
| Uranium | 39.59 | -0.65% |
| Gold Miners | 86.74 | -1.21% |
| Copper Miners | 83.4 | -1.53% |
| Strategic Metals | 62.95 | -2.04% |
Industrials | ||
| Construction | 91.5938 | +0.92% |
| Aerospace & Defense | 208.04 | +0.42% |
| Agriculture | 28.13 | -0.04% |
| Global Jets | 28.09 | -0.46% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 205.96 | -2.17% |
Renewables | ||
| Hydrogen | 43.71 | -1.06% |
| Solar | 43.07 | -2.05% |
Technology | ||
| Cloud Computing | 29.0 | +1.90% |
| Semiconductor | 576.33 | +1.35% |
| Cybersecurity | 46.48 | +0.65% |
| Robotics & AI | 35.43 | +0.57% |
| FinTech | 24.3707 | +0.46% |
| Electric Vehicles | 33.05 | -0.06% |
| Data Center & Digital Infrastructure | 27.07 | -0.26% |
ASX Today
It's crickets out there today!
What To Watch Today
A bandaid for a bullet wound. ASX futures are pointing to a ~0.5% bounce after yesterday's sea of red. Every sector finished lower and 176 S&P/ASX 200 constituents fell (88%). Most major banks tanked 2 to 3%, Woolies and Coles both fell ~2.5%, high-flyer CSL pulled back 3.2% and Woodside tumbled 3.1% despite higher oil prices. You get the idea, nothing was spared. There were some encouraging signs in the bond market overnight, where the policy-sensitive Aussie 3-year yield rose as much as 8 bps early before finishing 2 bps lower at 4.93%, its lowest since 10 September. US yields showed a similar fade to finish broadly lower. On the flip side, Brent has rallied back above US$100 and US diesel futures are trending higher again after a ~10% pullback from record highs. So we're set to bounce from oversold levels, but what gives?
Key Events
Stocks trading ex-dividend:
Fri 2 Oct: NRW Holdings (NWH) – $0.145, Steamships Trading Company (SST) – $0.093
Mon 5 Oct: Verbrec (VBC) – $0.002
Tue 6 Oct: Harvey Norman Holdings (HVN) – $0.13, Reece (REH) – $0.134, Ridley Corporation (RIC) – $0.053
Wed 7 Oct: MFF Capital Investments (MFF) – $0.11
Thu 8 Oct: ARB Corporation (ARB) – $0.35, Clime Capital (CAM) – $0.014, Naos Emerging Opportunities Company (NCC) – $0.021, WAM Capital (WAM) – $0.077
Other ASX corporate actions today:
Dividends paid: CSL (CSL), Origin Energy (ORG), Lycopodium (LYL), Perpetual (PPT), Service Stream (SSM), Joyce Corp (JYC), Vita Life Sciences (VLS), a2 Milk Co (A2M), Auckland International Airport (AIA), Integral Diagnostics (IDX), QBE Insurance Group (QBE), Supply Network (SNL), Spark New Zealand (SPK), Evolution Mining (EVN), Peter Warren Automotive Holdings (PWR), Tourism Holdings (THL), Symal Group (SYL)
IPOs: None
AGMs: None
Economic calendar (AEST):
7:00 pm: European Inflation Rate
10:30 pm: US Non Farm Payrolls and Unemployment Rate