In a nutshell:
Major US benchmarks finished higher, but off best levels, with the S&P 500 up 0.6% to its first record close since August, the Nasdaq also closed at a record for a second day
The US 10-year bond yield pulled back from its highest since 2002, with traders pricing about an 80% chance the Fed holds at its next meeting
AI and power stocks led the session, as Google's nuclear deal lifted Constellation Energy and Marvell raised its long-term revenue targets, while Nvidia's market cap is now approaching $6 trillion
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,819 | +0.58% |
Dow Jones | 51,521 | +0.49% |
NASDAQ Comp | 27,600 | +0.45% |
Russell 2000 | 2,830 | -0.59% |
Global Indices | ||
 S&P/TSX | 35,650 | +0.37% |
 Shanghai Composite | 3,842 | +0.31% |
 DAX | 25,449 | +0.77% |
 Hang Seng | 24,281 | +1.00% |
 Nifty 50 | 73,068 | +0.95% |
 Nikkei 225 | 70,684 | +1.05% |
 FTSE 100 | 10,542 | +0.42% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,164.34 | +0.59% |
 Copper | 6.61 | +0.32% |
 WTI Oil | 89.91 | +0.54% |
Currency | ||
 AUD/USD | 0.6984 | +0.00% |
Cryptocurrency | ||
 Bitcoin (USD) | 85,568 | -0.43% |
 Ethereum (AUD) | 3,861 | -0.54% |
Miscellaneous | ||
US 10 Yr T-bond | 5.269 | -0.79% |
VIX | 15.01 | -3.29% |
US Sectors
Sector | % Chg |
|---|---|
| Utilities | +3.01% |
| Consumer Discretionary | +1.39% |
| Real Estate | +1.13% |
| Consumer Staples | +0.96% |
| Industrials | +0.90% |
| Materials | +0.65% |
Sector | % Chg |
|---|---|
| Information Technology | +0.55% |
| Energy | +0.44% |
| Financials | +0.18% |
| Communication Services | +0.16% |
| Health Care | -0.16% |
S&P 500 Session Chart
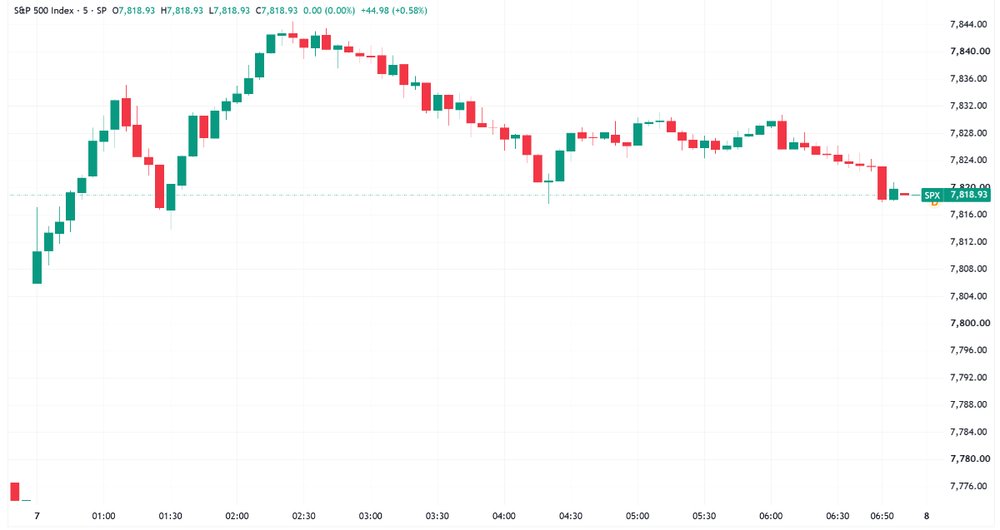
S&P 500 gapped up at open then trended sideways to finish off best levels (Source: Trading View)
Overnight Markets
Major US benchmarks higher and finished off best levels, with the S&P 500 up for a fourth straight session and marking its first record high since 13-Aug
Nasdaq scored a second straight all-time high, though most megacap tech names struggled for outsized gains and up less than 1%
Breadth was strong as 10 of the 11 S&P 500 sectors higher, healthcare was the only weak spot after names like Novavax and Moderna reversed Monday's Russia plague-scare gains
Russell 2000 snapped three day gains and was the only benchmark to finish lower as investors rotated back into megacap tech and the AI trade
US Dollar lost 0.25% to 101.8, but is still up 3.1% since early September
Treasury yields eased after the US 10-year hit its highest since April 2002 on Monday, with the benchmark down about 2 bps near 5.28%
Brent settled 0.9% higher at US$101.12 a barrel but briefly tumbled 3.1% intraday as Saudi Arabia restored East-West pipeline capacity to 5.8m barrels a day
JPMorgan CEO Jamie Dimon said he is concerned inflation may prove sticky and push rates higher, in a Bloomberg TV interview on AI financing and the global bond selloff (BBG)
S&P 500 PEG ratio at a 30-year low, according to Yardeni Research, suggesting valuations are not overheated relative to earnings growth (YF)
Wall Street profits surge, with first-half profits at NYSE member firms up 51% to $49.5bn, already above New York City's full-year projection, says Comptroller DiNapoli (YF)
Emerging markets gain for a second day as Treasury yields and oil eased, while Brazilian assets stayed bid after a conservative first-round election sweep (BBG)
BNP warns against axing the 20-year bond, saying Bessent cutting the tenor could push borrowing costs higher as traders weigh a shift toward short-dated debt (BBG)
Stocks
Constellation Energy surged about 12% after Google signed a 20-year power deal worth $4.3bn to bring 890MW of nuclear capacity online through upgrades at six existing plants in Illinois, New Jersey and Pennsylvania (YF)
AMD CEO Lisa Su said the chipmaker will substantially increase supply in 2027 to meet booming AI demand, with its market value recently topping $1tn (RT)
Nvidia hit another record high, with its market value approaching $6tn as AI-linked shares led the rally (BBG)
OpenAI and Anthropic face rising price pressure as AI-powered software startups increasingly switch to cheaper open models (BBG)
Berkshire Hathaway disclosed buying about 2.4m Lennar shares, lifting its stake to about 12% and sending the homebuilder higher (CNBC)
Geopolitics
Yemen government forces launched a strategic offensive on the Houthi-held capital Sanaa after retaking the Red Sea port of Mokha, loosening the group's grip on a key oil route (CNBC)
Iran stepped up attacks on tankers transiting Hormuz, threatening a fragile export rebound, with Windward estimating crude flows at 9m to 10m barrels a day against a 14.5m pre-war baseline (CNBC)
The Saudi-led coalition said it intercepted a Houthi ballistic missile launched at the southern city of Khamis Mushait (AJ)
Central Banks
October Fed hike bets fade, with CME FedWatch showing a 21% chance of an October hike but almost 70% odds of a December increase (CNBC)
BoJ Governor said the bank intends to keep raising rates in line with economic and price developments, doing little to challenge bets against an October hike (BBG)
ECB chief economist Philip Lane said the recent surge in energy prices is a second wave of the energy supply shock, to be assessed alongside fiscal policy, AI and financial conditions (ECB)
Economy
US trade deficit widened to more than $100bn in August, above ests of $89.8bn, as importers absorbed new tariffs and kept buying AI data-centre components. The deficit with China rose to $16.4bn (YF)
ANZ-Roy Morgan consumer confidence fell 3.4pts to 67.1, the tenth-lowest reading since 1973, after the RBA lifted the cash rate to 4.60% (ANZ)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Uranium | 41.8 | +4.01% |
| Lithium & Battery Tech | 71.07 | +1.34% |
| Gold Miners | 88.22 | +0.92% |
| Silver Miners | 86.63 | +0.56% |
| Strategic Metals | 63.79 | +0.39% |
| Copper Miners | 86.28 | -0.06% |
| Steel | 105.04 | -0.08% |
Industrials | ||
| Construction | 94.72 | +2.37% |
| Agriculture | 28.85 | +1.37% |
| Global Jets | 28.1 | +0.75% |
| Aerospace & Defense | 208.26 | +0.62% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 203.1 | -2.34% |
Renewables | ||
| Solar | 44.4 | +1.67% |
| Hydrogen | 45.05 | +0.87% |
Technology | ||
| Cybersecurity | 48.73 | +2.10% |
| Data Center & Digital Infrastructure | 27.78 | +1.39% |
| Electric Vehicles | 33.9366 | +0.67% |
| Semiconductor | 589.45 | -0.01% |
| Robotics & AI | 36.17 | -0.08% |
| FinTech | 24.837 | -0.45% |
| Cloud Computing | 29.06 | -0.48% |
ASX Today
It's crickets out there!
What To Watch Today
(Kerry here. FYI my colleague Joe has been writing the Morning Wrap for the past two weeks, so I've just added a few thoughts on what to watch)
Uranium in focus after the Global X Uranium ETF rose 4.0% overnight on read-through from the Google-Constellation nuclear deal. Evercore says the deal is positive for other plant owners and for uranium enrichers via higher fuel demand
Biotech under pressure with US biotech ETFs down 2-3% as Novavax (-9.8%) and Moderna (-7.7%) unwound Monday's Russia plague scare, which the WHO has since called low risk. Though not so much to do with our market/local names
Yields take a breather but remain as volatile as ever. The Aussie 10-year fell 5 bps in early trade on Tuesday, reversed the entire dip to trade fractionally higher by late afternoon, then closed the session down 5 bps at 5.35%. Yields were broadly lower to flat overnight and the US Dollar Index slipped 0.2% to 101.86, a combination that usually makes for a solid lead for local equities
Thinking out loud, higher yields and a resilient market are two sides of the same bullish argument. A recession-proof US economy should push yields higher, but it should also encourage investors to price in stronger corporate earnings growth. Without a clear danger to the economy, the two can co-exist, which is why the US market keeps grinding selectively higher (and why we're not, due to the lack of earnings growth ... among other things)
Key Events
Stocks trading ex-dividend:
Wed 7 Oct: MFF Capital Investments (MFF) – $0.11, Ryder Capital (RYD) – $0.03
Thu 8 Oct: ARB Corporation (ARB) – $0.35, Clime Capital (CAM) – $0.014, Naos Emerging Opportunities Company (NCC) – $0.021, WAM Capital (WAM) – $0.077
Fri 9 Oct: EQT Holdings (EQT) – $0.20
Mon 12 Oct: Civmec (CVL) – $0.035, Washington H. Soul Pattinson (SOL) – $0.63
Tue 13 Oct: Perenti (PRN) – $0.045, Star Combo Pharma (S66) – $0.003
Other ASX corporate actions today:
Dividends paid: Atlas Arteria (ALX), Cash Converters International (CCV), HMC Capital (HMC), Humm Group (HUM), Kina Securities (KSL), Neuren Pharmaceuticals (NEU), News Corp (NWS), NIB Holdings (NHF), Perseus Mining (PRU), Regis Resources (RRL), Servcorp (SRV), Solvar (SVR), Southern Cross Electrical Engineering (SXE), Wesfarmers (WES), West African Resources (WAF)
IPOs: None
AGMs: None
Economic calendar (AEDT):
No major economic events today