In a nutshell:
Wall Street gave back part of Monday's rally after hot inflation data, with Nvidia dragging the major averages lower a day after the S&P 500's best session since April
Core CPI beat for a third straight month, keeping the Fed on track to hike next month, while short-dated Treasuries headed for their worst day since April 2025
Brent briefly slipped below US$90 for the first time since August as Trump's comments fed hopes for an end to the Iran war
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,521 | -0.38% |
Dow Jones | 52,232 | -0.30% |
NASDAQ Comp | 25,066 | -0.74% |
Russell 2000 | 2,826 | -0.53% |
Global Indices | ||
 S&P/TSX | 36,170 | -0.76% |
 Shanghai Composite | 3,664 | +0.08% |
 DAX | 26,347 | +0.31% |
 Hang Seng | 24,557 | +0.44% |
 Nifty 50 | 81,107 | +0.13% |
 Nikkei 225 | 60,460 | +2.87% |
 FTSE 100 | 10,752 | -0.29% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,030.71 | -2.65% |
 Copper | 6.25 | -1.18% |
 WTI Oil | 86.32 | -0.61% |
Currency | ||
 AUD/USD | 0.6866 | -0.87% |
Cryptocurrency | ||
 Bitcoin (USD) | 73,876 | -1.40% |
 Ethereum (AUD) | 3,001 | -3.21% |
Miscellaneous | ||
US 10 Yr T-bond | 4.983 | +2.45% |
VIX | 19.33 | -2.96% |
US Sectors
Sector | % Chg |
|---|---|
| Financials | +0.49% |
| Consumer Discretionary | +0.46% |
| Energy | +0.32% |
| Health Care | +0.27% |
| Consumer Staples | +0.22% |
| Industrials | -0.08% |
Sector | % Chg |
|---|---|
| Real Estate | -0.11% |
| Communication Services | -0.15% |
| Utilities | -0.23% |
| Materials | -0.55% |
| Information Technology | -1.40% |
S&P 500 Session Chart
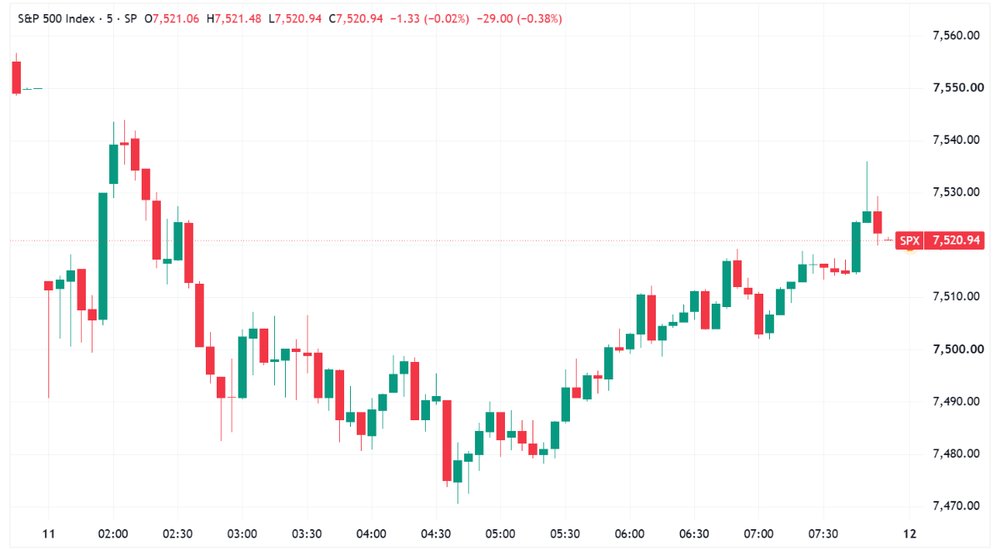
S&P 500 lower but off worst levels (Source: TradingView)
Overnight Markets
Major US benchmarks lower, finished off worst levels after a hot October CPI print and hawkish Fed speak, with Nvidia (-5.5%) dragging all three major averages a day after the S&P 500's best session since April
Short-dated Treasuries sank, with two-to-five-year yields up more than 10 bps as traders added bets on at least two Fed hikes by mid-2027 and a small chance of a half-point December move (BBG)
Traders fully priced a quarter-point December hike and lifted half-point odds to 13.6% from around zero before the CPI release, per CME FedWatch (CNBC)
A Yahoo Finance basket of 62 chipmakers has shed about $5trn, with Nvidia on track for its lowest close since 30 March and its RSI the most oversold since June 2019 (YF)
Anthropic set its IPO range at $70 to $78 a share, seeking a valuation of about $1.4trn and up to $90.4bn including a private placement (BBG)
Semiconductors are now clearly oversold, with Nvidia, Broadcom and AMD top picks, says Goldman Sachs' James Schneider (YF)
Treasury yields won't truly peak until a recession, and the Fed risks hiking until something breaks, says T. Rowe Price's Arif Husain (BBG)
October CPI likely sealed a December hike, though most officials will be more cautious than Waller on a half-point move, says Bloomberg Economics (BBG)
Stocks
Nvidia board hired Wachtell Lipton and former acting SDNY US Attorney Joon Kim to investigate CEO Jensen Huang and whether company secrets or national security were compromised (CNBC)
Microsoft fell about 3% after Anthropic unveiled Claude Sheets, Claude Whiteboards and Claude Data, workplace tools that could rival Office (CNBC)
TSMC October revenue up 59.7% year-on-year to NT$586.89bn, up 14.7% month-on-month, with shares rising on the print (CNBC)
Goldman Sachs, Citigroup, Santander and Deutsche Bank are among firms committing about $270m to a joint US dollar stablecoin venture (BBG)
Geopolitics
Trump said the Iran war could end soon and played down new strikes after meeting Qatar's PM, though Iranian officials disputed that talks were underway (CNBC)
US, Russian and Ukrainian negotiators opened talks in Abu Dhabi, the first trilateral round since February, with security guarantees at the centre of the two-day session (AP)
Brent briefly fell below $90 for the first time since August on hopes the nearly nine-month war with Iran is ending, with ING saying the geopolitical risk premium is unwinding (CNBC)
Saudi tanker firm Bahri is sending vessels through Hormuz in coordination with the US military, with four crossing on Tuesday (BBG)
Tariffs & Trade
Central Banks
Fed Governor Christopher Waller said a December hike is likely and a half-point move could be warranted if inflation data runs hotter than expected (CNBC)
Dallas Fed President Lorie Logan backed at least two more quarter-point hikes, adding they may be needed at a quicker pace than this fall (BBG)
Rate decisions hinge on how far fuel price increases spill into wages and other prices, with energy starting to reverse, says ECB chief economist Philip Lane (YF)
Bank of Canada officials said uncertainty from higher oil and the US trade war won't necessarily stop further hikes, after lifting rates to 2.5% last month (BBG)
Economy
US CPI rose 0.4% month-on-month in October, with core up 0.3% and topping ests for a third straight month, the last print before the Fed's 8-9 December meeting (BBG)
China's trade surplus topped $1trn for the year for the second time ever as October imports jumped almost 42% year-on-year, the most since 2021, and exports rose about 35% (BBG)
Australian consumer sentiment fell 2.7% to a four-year low of 78.2 in November, per the Westpac-Melbourne Institute survey (YF)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Steel | 99.7265 | +0.10% |
| Lithium & Battery Tech | 59.92 | -2.33% |
| Copper Miners | 72.89 | -3.14% |
| Uranium | 33.14 | -3.49% |
| Strategic Metals | 51.82 | -3.54% |
| Gold Miners | 86.55 | -5.37% |
| Silver Miners | 78.91 | -5.43% |
Industrials | ||
| Aerospace & Defense | 72.41 | +1.03% |
| Agriculture | 26.275 | +0.67% |
| Global Jets | 30.175 | -0.08% |
| Construction | 88.68 | -1.66% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 217.18 | -1.09% |
Renewables | ||
| Hydrogen | 33.94 | -1.39% |
| Solar | 43.51 | -3.70% |
Technology | ||
| Semiconductor | 146.59 | -0.12% |
| Data Center & Digital Infrastructure | 25.37 | -0.28% |
| Cloud Computing | 25.9 | -0.96% |
| Robotics & AI | 31.57 | -0.97% |
| FinTech | 24.27 | -1.10% |
| Electric Vehicles | 29.062 | -1.37% |
| Cybersecurity | 44.88 | -1.49% |
ASX Today
Auric Mining taps Canaccord, Taylor Collison and MA Moelis for a $13m two-tranche placement at 18.5c, a 24.5% discount, to fund the Iron Maiden gold acquisition near Norseman plus works at Munda and Union Jack. An SPP on the same terms follows (AWJ, AFR)
Commonwealth Bank posts 1Q27 unaudited cash NPAT of ~$2.8bn, flat on the 2H26 quarterly average and up 8% on the pcp. Operating income rose 3% on lending and deposit volume growth with underlying NIM broadly stable. Loan impairment expense of $300m, CET1 at 11.5% (CBA)
Generation Development Group is building an internal business case to buy financial planning firms out of its own client base, targeting a new arm with about $150m in annual revenue. The $1.3bn group says it has made no such acquisitions to date (GDG, AFR)
Tanami Gold completes blasting of the central and ventilation portals for the Groundrush exploration decline at the 50/50 Central Tanami JV with MGX Resources. The $38m Macmahon contract covers 3.5km of decline over 14 months, opening access for 33,000m of infill drilling (TAM)
What To Watch Today
Uh oh. October CPI came in slightly hotter than expected, lifting the odds of a December Fed rate hike to 90.5%, up from 77.4% a week ago. By Jun-27, markets now slightly favour three hikes to 4.50–4.75%. Not a good look. The print drove the US 2-year yield 17 bps higher, and longer-dated yields by a little less (just as they were rolling over). Then there’s the AI trade, with Nvidia (-5.5%) extending its sell-off and Microsoft (-2.2%) tanking after Anthropic released Claude Sheets, its own take on Excel. So now we've got a mix of a more hawkish Fed and a still-volatile AI trade weighing on various pockets of the market, including small caps, tech and commodities. Copper (-1.7%) got smacked right after bouncing 2% on Monday, while gold fell a sizeable 2.6% to US$4,030/oz. Our overnight ETF watchlist was pretty much the opposite of yesterday, with most resource-related names down 2-5%, led by Gold and Silver Miners, both down ~5.5%. Overall, markets remain at a choppy and confusing juncture. Inflation is sticky, AI stocks are oversold but volatile, bond yields have renewed ammo to bounce, and the US dollar is eyeing a breakout to its highest since April 2025. Encouragingly, oil is still moving in the right direction and the Equal-weight S&P 500 traded flat thanks to gains from banks, retailers, healthcare and staples. So I guess the broadening out/defensives trade is still there?
Monadelphous Group: Shares surged ~15% on Tuesday after the company guided to 1H27 NPAT of $80-85m, implies 23-31% growth or 23% above consensus expectations (a massive surprise). For context, MND shares have been trading sideways since Feb after rallying some ~180% since August 2024. It sold off after its August FY26 result, where management said FY27 would be a year of "consolidation" after roughly 50% revenue growth over the last two years. Not a good look for a stock that was trading at around 30x at the time. Now it's got some growth behind it, though the catalyst isn't as clean as it could be, with management noting activity is expected to moderate in 2H27
Key Events
Stocks trading ex-dividend:
Wed 11 Nov: Macquarie Group (MQG) – $3.25, ResMed (RMD) – $0.066, Sandon Capital (SNC) – $0.005
Thu 12 Nov: ANZ Group (ANZ) – $0.83, Dominion Income Trust 1 (DN1) – $0.687
Fri 13 Nov: None
Other ASX corporate actions today:
Dividends paid: Kingsgate (KCN), Dexus Industrial REIT (DXI), Dexus Convenience Retail REIT (DXC)
Earnings: None
IPOs: None
AGMs: Adairs (ADH), Beach Energy (BPT), Domino’s Pizza Enterprises (DMP), Downer EDI (DOW), Flight Centre Travel Group (FLT), Growthpoint Properties Australia (GOZ), Netwealth Group (NWL), PEXA Group (PXA)
Economic calendar (AEDT):
11:30 am: Australia Home Loan Growth, Investment Lending