In a nutshell:
Major US benchmarks slipped in a fairly rangebound session, a second straight fall as the long-bond selloff deepened, with the 30-year rising for a sixth straight session
US consumer confidence slumped to its weakest in more than a decade as views on jobs and the economy soured, while Fed officials kept the door open to another rate hike this year
Oil eased as Saudi Arabia ramped up its Red Sea bypass pipeline and Washington tapped more emergency reserves, even as Iran talks stalled
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,671 | -0.17% |
Dow Jones | 51,350 | -0.26% |
NASDAQ Comp | 26,798 | -0.09% |
Russell 2000 | 2,808 | -0.35% |
Global Indices | ||
 S&P/TSX | 35,460 | -0.08% |
 Shanghai Composite | 3,830 | +0.18% |
 DAX | 25,399 | +0.10% |
 Hang Seng | 24,524 | -0.48% |
 Nifty 50 | 72,529 | -0.33% |
 Nikkei 225 | 65,481 | -0.60% |
 FTSE 100 | 10,637 | -0.45% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,179.58 | +1.57% |
 Copper | 6.59 | +0.35% |
 WTI Oil | 89.38 | -3.48% |
Currency | ||
 AUD/USD | 0.6987 | -0.02% |
Cryptocurrency | ||
 Bitcoin (USD) | 83,507 | -0.01% |
 Ethereum (AUD) | 3,840 | +0.40% |
Miscellaneous | ||
US 10 Yr T-bond | 5.255 | +0.29% |
VIX | 16.04 | -0.19% |
US Sectors
Sector | % Chg |
|---|---|
| Utilities | +1.14% |
| Communication Services | +0.40% |
| Industrials | +0.19% |
| Consumer Discretionary | +0.05% |
| Real Estate | -0.01% |
| Information Technology | -0.28% |
Sector | % Chg |
|---|---|
| Health Care | -0.32% |
| Financials | -0.37% |
| Consumer Staples | -0.54% |
| Materials | -0.55% |
| Energy | -0.89% |
S&P 500 Session Chart
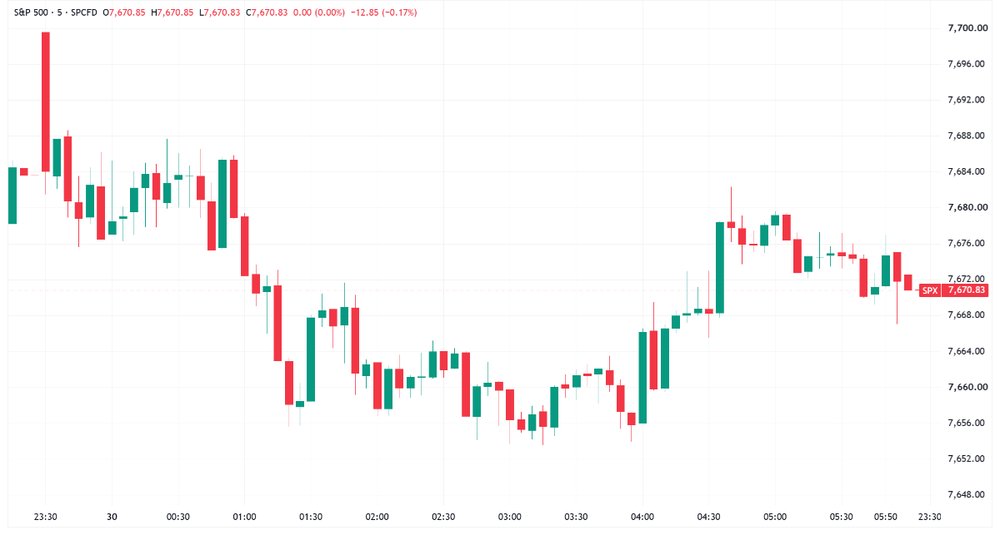
S&P 500 recovered some early loses in a fairly rangebound session to finish off worst levels (Source: Trading View)
Overnight Markets
Major US benchmarks slipped, finished off worst levels for a two session slide
US 30-year yield rose for a sixth straight session topping 5.61% intraday, its highest since 2002, as inflation angst and hefty corporate debt supply weighed on the long end
Brent slid to settle below US$103 a barrel as Saudi Arabia restored about half its East-West pipeline capacity after drone strikes, overshadowing the US-Iran stalemate
US Dollar added 0.2% to finish at 101.3, extending a 2.7% gain since 10 September
Lower oil did little to calm Wall Street's concern that elevated energy costs could fuel inflation and spur further Fed hikes, with the dollar edging up as the pace of the Treasury rout eased (BBG)
US offered up to 40m barrels from the Strategic Petroleum Reserve, the final tranche of its 172m-barrel contribution to the coordinated release, and urged European nations to follow as fuel prices climb before midterms (BBG)
US Treasuries are on track for their worst September since 2023, with history suggesting October may bring little relief as traders price in more Fed hikes and oil stays elevated (YF)
Yardeni Research president Ed Yardeni said the bond selloff could mark a return of the bond vigilantes, saw room for yields to keep rising and flagged a yen-carry unwind as a possible driver (BBG)
Stocks
OpenAI is seeking at least $30bn in new funding at a roughly $1.4tn valuation before new money after pushing back IPO plans, potentially lifting it back above Anthropic's latest private valuation, Bloomberg reported (BBG)
Paramount Skydance launched an eight-tranche investment-grade bond sale, the largest slice of a $52bn debt package funding its Warner Bros. Discovery acquisition, with maturities from two to 40 years (BBG)
Carnival Q3: record revenue of $8.44bn topped ests as the cruise operator absorbed higher fuel costs, shares jumped about 13% early in the session (YF)
President Trump said he signed a morally binding AI document with tech leaders after a White House lunch, saying the sector was policing itself well and floating a possible 10-person oversight committee (CNBC)
Geopolitics
Iranian officials privately expressed pessimism about reaching a deal to end hostilities and reopen the Strait of Hormuz before the 3 November US midterms, seeing a high chance of escalation after the vote, Bloomberg reported (BBG)
Tehran said it remained ready for talks after President Trump rejected reports he had offered Iran sanctions relief and the release of frozen funds for nuclear steps, saying he offered them nothing (RT)
Kpler satellite imagery confirmed a major operational recovery at Saudi Arabia's Yanbu and Muajjiz export terminals, with 12.5m barrels loaded onto nine tankers at Yanbu between Saturday and Monday (CNBC)
Tariffs & Trade
Trump's 100% tariff on certain patented drugs and their ingredients took effect, with Brookings finding more than 100 drugmakers make at least one non-exempt drug, while generics and orphan drugs are largely exempt (CNN)
A US import ban on select Canadian products including alcohol and motorcycles is now in effect, marking the latest escalation in the trade conflict between the two neighbours (BBG)
China's tariff cuts on US farm goods left crop traders unsure of any demand lift, with soybeans excluded, weak Chinese growth sapping corn and wheat demand and the timing of the cuts still unclear (BBG)
Central Banks
New York Fed President John Williams said one more rate hike may be appropriate late this year to speed inflation's return to target, but saw no urgency after the Fed's September increase (BBG)
Fed Governor Michael Barr repeated that further rate increases will likely be needed to slow inflation, echoing last week's view that a robust economy makes inflation the bigger priority (BBG)
St Louis Fed President Alberto Musalem said clearly communicating how the Fed adjusts rates to incoming data can improve policy transmission and deliver better economic outcomes, speaking in London (BBG)
RBA unanimously lifted the cash rate 25bps to 4.6%, the highest since late 2011, with the board open to further hikes, though Bullock said a hold was considered and recession is not the base case (BBG)
Economy
US Conference Board consumer confidence fell 6.7 points to 81.9, the lowest since 2014, after a downward revision to August and below every forecast in a Bloomberg survey (BBG)
US job openings fell to a five-month low of 7.1m in August from 7.3m, short of all ests in a Bloomberg survey, while layoffs stayed subdued (BBG)
Spain's annual inflation rate jumped 0.6 percentage points to 4.9% in September, driven by fuel, lubricants and package holidays, while core inflation rose to 3.1% (YF)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Gold Miners | 89.07 | +1.34% |
| Strategic Metals | 64.79 | +0.50% |
| Lithium & Battery Tech | 68.54 | +0.38% |
| Copper Miners | 85.48 | +0.26% |
| Silver Miners | 87.17 | +0.21% |
| Uranium | 40.04 | -0.22% |
| Steel | 102.507 | -1.51% |
Industrials | ||
| Global Jets | 28.56 | +0.25% |
| Aerospace & Defense | 209.3 | +0.02% |
| Agriculture | 28.25 | 0.00% |
| Construction | 91.5827 | -0.40% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 211.04 | +0.16% |
Renewables | ||
| Hydrogen | 43.9 | +2.71% |
| Solar | 43.43 | +1.00% |
Technology | ||
| Semiconductor | 567.44 | +1.19% |
| Robotics & AI | 35.24 | +0.31% |
| Cybersecurity | 45.44 | +0.09% |
| Electric Vehicles | 33.1536 | +0.07% |
| Cloud Computing | 28.1 | 0.00% |
| Data Center & Digital Infrastructure | 27.31 | -0.11% |
| FinTech | 24.61 | -0.65% |
ASX Today
Ai-Media Technologies launches an on-market buy-back of up to 20.8m shares, or 9.9% of issued capital, funded from existing cash. Purchases can start 26 October and run up to 12 months, with Morgans appointed to act (AIM)
Liontown Resources takes FID on the Kathleen Valley expansion, approving $389m to lift processing from ~2.8Mtpa to 4.2Mtpa and take five-year average concentrate output to ~780,000 dmt a year from FY30. Payback ~2.5 years from end of construction, unit costs targeted at $840-920/dmt FOB (LTR)
Liontown Resources leaves FY27 concentrate guidance of 390,000-440,000 dmt and unit costs of $1,050-1,250/dmt FOB unchanged, but lifts FY27 capex guidance to $435-495m from $320-370m to absorb the expansion spend (LTR)
Metal Powder Works executes a two-year deal to supply Embassy Powdered Metals with pure copper powder worth ~US$300,000 a year, or ~US$600,000 over the term. Converts August's maiden copper infiltration order into recurring revenue, with supply from January 2027 (MPW)
Telix Pharmaceuticals granted FDA Fast Track designation for its BiPASS program, evaluating 68Ga-PSMA-PET imaging alongside MRI pre-biopsy for prostate cancer. Phase 3 enrollment is complete and an NDA is being prepared, with Fast Track potentially enabling expedited review (TLX)
SkyCity Entertainment launches a structured process with UBS and Chapman Tripp to evaluate value-enhancing opportunities, including continued talks with the two parties whose August takeover approaches it rebuffed. Also starting a formal sale process for its Adelaide business and targeting $275–300m in asset sale proceeds by end-2026 (SKC)
What To Watch Today
Not a whole lot: A fairly uneventful US lead, with the major indices finishing slightly lower and sectors little changed. Closer to home, the Aussie 3-year yield tumbled 11 bps to 4.94% on Tuesday, its second-largest one-day fall this year, while the 30-year slipped 5 bps to 5.78%. Much of the hawkishness may already have been priced in ahead of the RBA decision, which brought some relief to the short end and the broader market. But this isn't an all-clear. Breadth remains very weak, and most ASX sectors, including REITs, retailers, financials, telcos, tech and industrials, have fallen sharply since late August and now sit below their 200-day moving averages.
Commodities bounce: Most commodities clawed back around a third of the previous session's slide. Gold rose 1.5% to US$4,182 after a 4.0% drop, and copper added 0.8% to US$6.69 after falling 2.4%. Gains across our resource-related ETF watchlist were fairly muted. Most of those ETFs, spanning gold, silver, nickel, uranium and rare earths/strategic metals, have rolled over 15-20% since late August and look technically vulnerable.
Key Events
Stocks trading ex-dividend:
Wed 30 Sep: Staude Capital Global Value Fund (GVF) – $0.033, Nick Scali (NCK) – $0.39, Sims (SGM) – $0.20, Cedar Woods Properties (CWP) – $0.25, Genusplus Group (GNP) – $0.036
Thu 1 Oct: CUE Energy Resources (CUE) – $0.003, Imperial Pacific (IPC) – $0.08, Kip McGrath Education Centres (KME) – $0.06, London City Equities (LCE) – $0.025, Pengana Global Private Credit Trust (PCX) – $0.013, Vulcan Steel (VSL) – $0.038, WAM Strategic Value (WAR) – $0.033
Fri 2 Oct: NRW Holdings (NWH) – $0.145, Steamships Trading Company (SST) – $0.093
Mon 5 Oct: Verbrec (VBC) – $0.002
Tue 6 Oct: Harvey Norman Holdings (HVN) – $0.13, Reece (REH) – $0.134, Ridley Corporation (RIC) – $0.053
Other ASX corporate actions today:
Dividends paid: Beach Energy (BPT), Bendigo and Adelaide Bank (BEN), Boom Logistics (BOL), Data3 (DTL), Karoon Energy (KAR), Praemium (PPS), Worley (WOR), EDU Holdings (EDU), Red Hill Minerals (RHI), Sandfire Resources (SFR), Mercury NZ (MCY), Ampol (ALD), Mineral Resources (MIN), Stealth Group Holdings (SGI), Regal Partners (RPL), IGO (IGO), Viva Energy Group (VEA), Guzman y Gomez (GYG)
IPOs: None
AGMs: None
Economic calendar (AEST):
11:30 am: Australia CPI
11:30 am: China manufacturing PMI
10:30 pm: US Core PCE Price Index