In a nutshell:
Wall Street had a bout of volatility in the final hour of trade to erase an early rally on cooler-than-expected PCE data, the S&P 500 and the Dow finished lower and at worst levels, while the Nasdaq was the only major to finish higher
Softer personal consumption expenditures (PCE) data cooled October Fed hike bets, but the long end of the Treasury curve stayed pinned near 24-year highs
Trump called for Powell to be forced off the Fed board minutes before the close, reviving Fed independence concerns
Micron's blowout result and guidance after the bell reinforced the AI memory boom heading into Q4
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,652 | -0.25% |
Dow Jones | 50,906 | -0.86% |
NASDAQ Comp | 26,861 | +0.24% |
Russell 2000 | 2,797 | -0.39% |
Global Indices | ||
 S&P/TSX | 35,236 | -0.63% |
 Shanghai Composite | 3,842 | +0.31% |
 DAX | 25,199 | -0.79% |
 Hang Seng | 24,613 | +0.37% |
 Nifty 50 | 72,480 | -0.07% |
 Nikkei 225 | 66,754 | +1.94% |
 FTSE 100 | 10,606 | -0.29% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,156.44 | -0.61% |
 Copper | 6.57 | +0.43% |
 WTI Oil | 90.42 | +1.16% |
Currency | ||
 AUD/USD | 0.6947 | +0.03% |
Cryptocurrency | ||
 Bitcoin (USD) | 83,601 | +0.02% |
 Ethereum (AUD) | 3,861 | -0.05% |
Miscellaneous | ||
US 10 Yr T-bond | 5.293 | +0.72% |
VIX | 16.34 | +1.87% |
US Sectors
Sector | % Chg |
|---|---|
| Information Technology | +0.61% |
| Consumer Discretionary | +0.13% |
| Energy | -0.02% |
| Communication Services | -0.04% |
| Utilities | -0.73% |
| Materials | -0.82% |
Sector | % Chg |
|---|---|
| Financials | -1.19% |
| Real Estate | -1.28% |
| Industrials | -1.29% |
| Health Care | -1.39% |
| Consumer Staples | -1.68% |
S&P 500 Session Chart
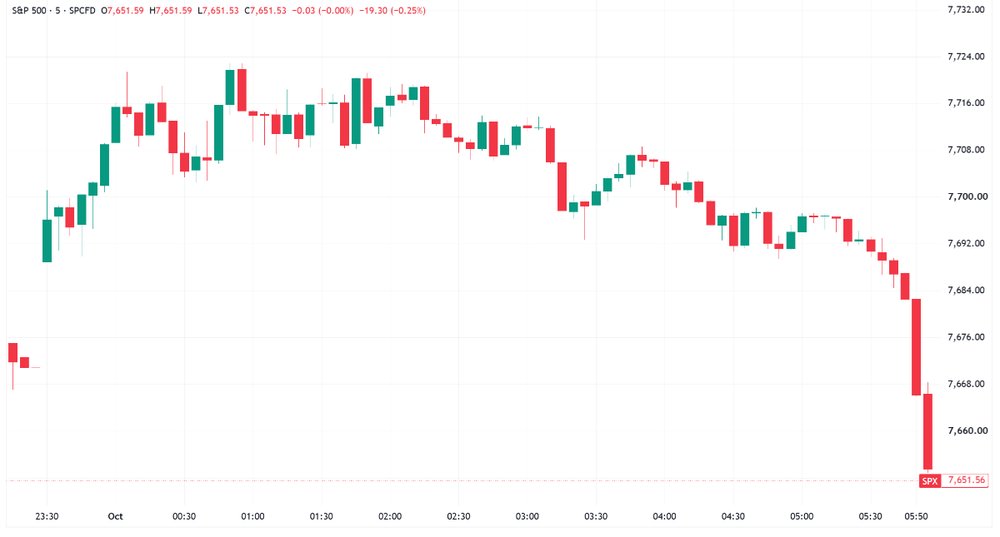
S&P 500 made early gains and traded sideways until a late sell off pushed index to finish at worst levels (Source: Trading View)
Overnight Markets
Major US benchmarks finished mixed, with S&P and the Dow erasing gains to finish at worst levels after a bout of volatility in the final hour of trading leaving the Nasdaq the only major gauge higher
The S&P 500 had its worst month since June, down 0.45% from 31 August
The 30-year Treasury yield climbed for a seventh session, up another 6bps to 5.63%, holding near its highest since 2002, the two and 10-year yields also made gains despite the softer inflation print
The US dollar rose 1.9% in September, its biggest monthly gain since June, as the Iran war kept energy prices elevated and pushed Treasury yields to historic peaks
Schwab's Cooper Howard said the softer PCE print does not change the Fed story, warning inflation breadth remains too high with 52% of PCE subcomponents rising above 3% (Schwab)
Manulife JH Investments co-CIO said every stock is loved and every bond disliked, arguing the PCE data could be the catalyst that draws investors back into bonds (BBG)
Stocks
Micron Q4 FY26: revenue up 379% to a record $54.23bn, core data centre sales $18bn, adjusted EPS $33.42 beat ests by ~6%, guided Q1 revenue to $61.5bn vs $56.8bn ests as AI demand outstrips supply, CEO flagged an even stronger FY27, shares edged lower after hours (BBG)
Boeing won a more than $20bn Pentagon contract to develop the US Navy's sixth-generation F/A-XX carrier fighter, beating Northrop Grumman and adding to its 2025 Air Force F-47 win, with BNP Paribas noting the market already saw Boeing as favourite, shares jumped at the open (YF)
Nvidia faces a fresh challenge to its CUDA software moat after DeepSeek partnered with Huawei to open-source Ascend chip programming tools, including a language pitched as simpler than CUDA, and the pair jointly built a 128-chip Ascend 950 supernode (YF)
Moderna fell after Citi cut the vaccine maker to Sell, arguing its valuation had become stretched after a strong run to a 52-week high of $208.90, even as the broker lifted its price target to $80 from $60, implying roughly 60% downside (YF)
Iran & Energy
Iran said it received an official US response to its latest proposal to reopen the Strait of Hormuz and end the seven-month war, without disclosing its contents, days after Trump publicly rejected the plan (AP)
Trump said he has done a very bad job explaining his economic record as high gasoline prices from the Iran war weigh on his approval ahead of November midterms (RT)
Kpler data showed Middle East Gulf crude exports excluding Iran recovered to pre-war levels of at least 16.5m barrels a day in September, seven months after the Strait of Hormuz closed (TS)
Tariffs & Trade
A three-judge US trade court panel questioned whether USTR Jamieson Greer disregarded a decades-old congressional framework on forced labour and adequately justified 10-12.5% Section 301 tariffs on dozens of countries (BBG)
Central Banks
Money markets now price a below 37% chance of a 25bp Fed hike against 70% a week ago at the October meeting after August PCE undershot ests, easing pressure for a follow-up to September's first hike since 2023 (TE)
Trump said former Fed Chair Jerome Powell should be forced to resign from the central bank's board after an inspector general report found a series of missteps behind surging headquarters renovation costs (BBG)
ECB board member Isabel Schnabel said energy's impact on inflation expectations, resilient demand and the global jump in borrowing costs led by US yields will decide whether more rate hikes are needed (RT)
Economy
US PCE undershot ests in August, with headline at 3.4% year-on-year vs 3.7% and core at 3% vs 3.3%, helped by methodology changes that cut about 36bp from core, while spending surged (RT)
ADP private payrolls rose 90,000 in September, beating 68,000 ests and accelerating from a downwardly revised 36,000 in August, ahead of Friday's nonfarm payrolls report (CNBC)
US Q2 GDP growth was revised up to 2.2% annualised in its third reading from 1.5% previously, while corporate profit growth was revised down to 7.7% from 8.2% (Investrade)
Australia's trimmed mean CPI rose 0.2% month-on-month in August, holding annual core inflation at 3.6% in line with ests, while headline accelerated to 4% on fuel, prompting traders to wind back November RBA hike bets (BBG)
China's official manufacturing PMI rose to 50.1 in September from 49.8, returning to expansion for the first time since June and matching ests, while the non-manufacturing gauge jumped to 50.2 from 49 (BBG)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Lithium & Battery Tech | 68.42 | -0.18% |
| Steel | 102.263 | -0.24% |
| Uranium | 39.85 | -0.47% |
| Strategic Metals | 64.26 | -0.82% |
| Copper Miners | 84.7 | -0.91% |
| Silver Miners | 86.01 | -1.33% |
| Gold Miners | 87.8 | -1.43% |
Industrials | ||
| Agriculture | 28.14 | -0.39% |
| Construction | 90.76 | -0.90% |
| Aerospace & Defense | 207.18 | -1.01% |
| Global Jets | 28.22 | -1.19% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 210.53 | -0.24% |
Renewables | ||
| Hydrogen | 44.18 | +1.28% |
| Solar | 43.97 | +1.24% |
Technology | ||
| Cybersecurity | 46.18 | +1.63% |
| Cloud Computing | 28.46 | +1.28% |
| Semiconductor | 568.64 | +0.21% |
| Electric Vehicles | 33.1216 | +0.00% |
| Robotics & AI | 35.23 | -0.03% |
| Data Center & Digital Infrastructure | 27.14 | -0.62% |
| FinTech | 24.26 | -1.42% |
ASX Today
New Zealand King Salmon says shareholder China Resources Asset Management will sell its 9.87% stake to Oregon Group and the Porus Holdings Trust at NZ$0.225 a share, with a voting deed giving Oregon control of 50.68% of voting rights. The deal needs approval from shareholders, the Takeovers Panel and the Overseas Investment Office (NZK)
Exultant Mining reports final assays from its maiden drilling at the Balerion prospect in NSW, with five of six holes hitting zinc-lead-silver mineralisation, including 11.75m @ 9.12g/t silver and 1.43% zinc-lead from 240.15m. The mineralised zone thickens about 57% down dip and remains open, with near-term exploration focus now shifting to the Black Hammer copper-gold project (10X)
Bison Resources says magnetic imagery supports its targeting models across its Nevada projects, with the 1.5km Carlin-type gold anomaly at Bald Peaks sitting within a magnetic low that extends over 6.2km of strike, 4.7km of which remains unsampled. Drill planning is underway at Bald Peaks, with assays from a second batch of rock chip samples due this month (BSR)
What To Watch Today
Bottom or bull trap? What a session on Wednesday. Almost every sector caught an aggressive bid after Aussie CPI came in slightly cooler than expected, with headline inflation up 4.0% year-on-year (vs. 4.1% ests) and the trimmed mean in line at 3.6%. Combined with RBA Bullock's comments on Tuesday that "the hope here is that this will be restrictive enough … to bring things down," the data sparked massive bounces in rate-sensitive sectors like Real Estate (+3.6%), Discretionary (+2.2%) and Telcos (+1.9%). But then you look at where the Aussie 3-year settled, reversing a 7 bp decline to close fractionally higher at 4.95%, with Brent still holding above US$100. So you have to wonder, is this just a relief rally given how much hawkishness was already priced in, or is this the market bring looking forward? Meanwhile, the overnight session featured fairly broad weakness outside US tech, and most of our ETF watchlist finished lower, with resource ETFs mostly down 0.5-1.0%
Key Events
Stocks trading ex-dividend:
Thu 1 Oct: CUE Energy Resources (CUE) – $0.003, Imperial Pacific (IPC) – $0.08, Kip McGrath Education Centres (KME) – $0.06, London City Equities (LCE) – $0.025, Pengana Global Private Credit Trust (PCX) – $0.013, Vulcan Steel (VSL) – $0.038, WAM Strategic Value (WAR) – $0.033
Fri 2 Oct: NRW Holdings (NWH) – $0.145, Steamships Trading Company (SST) – $0.093
Mon 5 Oct: Verbrec (VBC) – $0.002
Tue 6 Oct: Harvey Norman Holdings (HVN) – $0.13, Reece (REH) – $0.134, Ridley Corporation (RIC) – $0.053
Wed 7 Oct: MFF Capital Investments (MFF) – $0.11
Other ASX corporate actions today:
Dividends paid: Alkane Resources (ALK), Downer EDI (DOW), Focus Minerals (FML), Breville Group (BRG), Enero Group (EGG), Imdex (IMD), Seek (SEK), COG Financial Services (COG), Bega Cheese (BGA), Adairs (ADH), Propel Funeral Partners (PFP), IVE Group (IGL), Wagners Holding Co (WGN), Australian Finance Group (AFG), Endeavour Group (EDV), Freightways Group (FRW)
IPOs: None
AGMs: Australia Foundation Investment Company (AFI) – 9:30 am
Economic calendar (AEST):
11:00 am: Australia Balance of Trade