In a nutshell:
Major US benchmarks finished lower, whipsawed during session but closed near worst levels and left the S&P 500 near a September loss
Oil volatility revived inflation fears, pushing the 10-year yield to a fresh 2007 high and lifted bets on an October Fed hike from 64% to 70%
Trump's rejection of Iran's Hormuz offer kept Brent above US$100 a barrel, though reports he is open to sanctions relief for nuclear progress helped stocks recover from midday lows
Nvidia unveiled the largest buyback authorisation increase on record and bucked a broad chip selloff, as renewed worries over rogue AI agents weighed on the AI trade
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,684 | -0.77% |
Dow Jones | 51,482 | -0.67% |
NASDAQ Comp | 26,820 | -0.92% |
Russell 2000 | 2,818 | -0.69% |
Global Indices | ||
 S&P/TSX | 35,490 | -0.87% |
 Shanghai Composite | 3,824 | -1.67% |
 DAX | 25,374 | -0.13% |
 Hang Seng | 24,643 | +0.54% |
 Nifty 50 | 72,772 | -1.52% |
 Nikkei 225 | 65,878 | -0.73% |
 FTSE 100 | 10,685 | -0.10% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,122.26 | -3.80% |
 Copper | 6.56 | -2.06% |
 WTI Oil | 93.29 | +0.95% |
Currency | ||
 AUD/USD | 0.7019 | +0.01% |
Cryptocurrency | ||
 Bitcoin (USD) | 83,071 | -1.33% |
 Ethereum (AUD) | 3,808 | -0.12% |
Miscellaneous | ||
US 10 Yr T-bond | 5.24 | +1.08% |
VIX | 16.07 | +8.07% |
US Sectors
Sector | % Chg |
|---|---|
| Consumer Staples | +0.40% |
| Health Care | +0.29% |
| Energy | +0.22% |
| Real Estate | -0.38% |
| Utilities | -0.65% |
| Information Technology | -0.70% |
Sector | % Chg |
|---|---|
| Materials | -0.74% |
| Industrials | -1.00% |
| Financials | -1.14% |
| Consumer Discretionary | -1.58% |
| Communication Services | -1.67% |
S&P 500 Session Chart
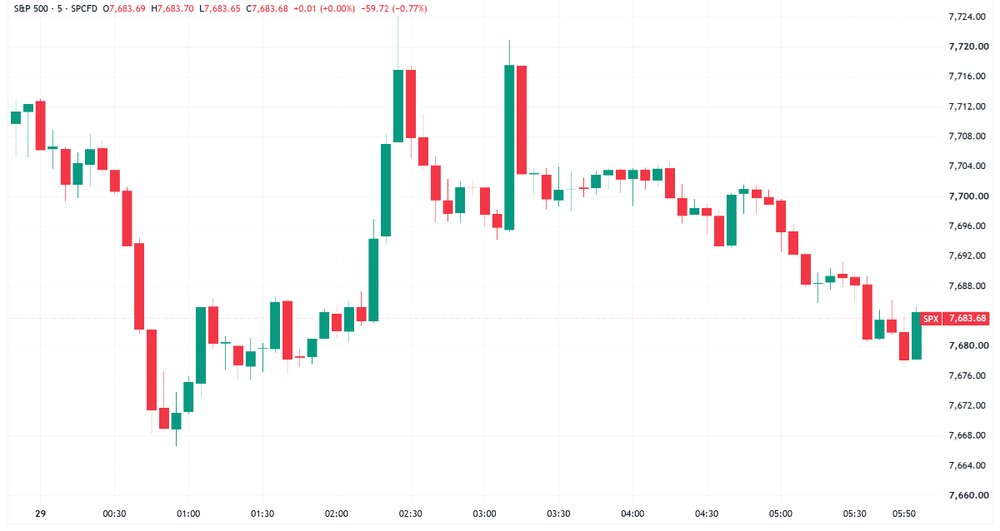
S&P 500 fell early then whipsawed during session to finish near worst levels (Source: Trading View)
Overnight Markets
Major US benchmarks finished lower, whipsawed during session to close near worst levels
US 10-year yield continued the recent accent, up 7 bps to 5.23%, and hit a near two-decade high as the US-Iran standoff drove oil volatility
Money markets boosted bets to 70.3% against 64.2% a day before for an October Fed rate increase and the US dollar increased 1.8% to 101.2 reversing a two day slide
Brent made a 0.8% gain to US$102.6 a barrel reversing some of Monday's losses, but holding firmly above US$100
The broad precious metals selloff was spurred by the Hormuz standoff which kept energy costs elevated and higher Treasury yields eroded the appeal of non-yielding bullion (BBG)
Chipmakers fell as an AI breach revived safety concerns, Intel down almost 6% and AMD down 4% to below $1tn in value, while Nvidia rose after releasing rogue-agent control tools (YF)
The 10-year to two-year Treasury spread shrank to as little as 0.17 percentage points last week intraday, putting the bond market on the brink of an inversion warning the US economy could stall (BBG)
Bianco Research's Jim Bianco turned bullish on Treasuries for the first time in six years, calling two-decade-high yields a value play and pledging to keep buying if yields climb further (BBG)
Goldman Sachs chief credit strategist Amanda Lynam warned a surge of US high-yield bond supply is starting to overwhelm debt investors, pushing risk premiums to their highest level in five months (BBG)
Stocks
Nvidia increased its share buyback authorisation by $150bn, lifting the total remaining amount authorised to $235bn, with the Santa Clara-based chipmaker at the heart of the AI boom saying it will complete the programme through fiscal 2028 (BBG)
Meta Platforms hired MongoDB chief executive to run a new Meta Enterprise Platform offering AI to business customers, a unit Mark Zuckerberg described as the company's next major business pillar, sending MongoDB shares plunging (BBG)
Boeing fell almost 7% after The Wall Street Journal reported a 737 Max cockpit software glitch that can disable an automated navigation function when landing after a missed approach, with US regulators reviewing the issue (YF)
Iran & Energy
Iran and the US appeared far apart on a new ceasefire or Hormuz reopening, with Tehran saying it would stick with the proposal Trump rejected and would not soften its conditions (BBG)
Trump is willing to ease sanctions and unfreeze Iranian assets in exchange for nuclear concessions, a US official said, with Qatari mediators due to meet administration officials Monday or Tuesday (Axios)
Saudi Arabia restored about half the flows through its East-West pipeline bypassing Hormuz, reaching at least 3.5m barrels a day to the Red Sea after drone strikes halted the route earlier this month (BBG)
EU and UK LNG deliveries are about 4% below a year earlier on a 30-day average, from 30% below in early August, while flows to Northeast Asia fell amid prolonged Hormuz disruption (BBG)
Tariffs & Trade
The US and China detailed a plan to cut tariffs on about $30bn of imports from each country, a key outcome of last week's Trump-Xi summit, freeing most goods from trade war-era duties (BBG)
China's list of 1,619 US goods set for potential tariff relief spans meat, seafood, dairy products, grains, coal and timber, while the 77-entry US list includes fireworks, sporting equipment and toys (BBG)
Trump said he is thinking very seriously about a diesel export ban to tackle record prices but conceded it could lift gasoline costs, as his team weighs three options short of an outright ban (YF)
TotalEnergies CEO Patrick Pouyanne told investors in New York that a US diesel export ban would be a bad idea, warning it could force US refiners to cut throughput and lift gasoline prices (BBG)
Central Banks
Fed Governor Lisa Cook warned expected AI productivity gains may not be enough to offset near-term price pressures, said this month's rate hike was needed and that future moves will be data-driven (BBG)
ECB President Christine Lagarde said the notable rise in long-term interest rates since the September meeting will slow eurozone growth and curb energy cost pass-through to inflation by more than projected (BBG)
The RBA is expected to lift the cash rate a quarter point to 4.6% at 2.30pm AEST, its highest since November 2011, ending a two-meeting pause, according to a Bloomberg survey (BBG)
Economy
China's State Council pledged to step up counter-cyclical policy and study new measures to stabilise the property market, promote employment and boost domestic demand, Xinhua reported (BBG)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Silver Miners | 91.56 | +0.66% |
| Gold Miners | 92.87 | +0.56% |
| Copper Miners | 86.73 | +0.56% |
| Lithium & Battery Tech | 69.02 | +0.29% |
| Uranium | 40.91 | +0.12% |
| Steel | 104.798 | -0.03% |
| Strategic Metals | 66.66 | -0.40% |
Industrials | ||
| Global Jets | 28.98 | +1.83% |
| Construction | 92.6091 | +1.47% |
| Aerospace & Defense | 213.81 | +0.49% |
| Agriculture | 28.54 | -0.04% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 209.77 | +0.25% |
Renewables | ||
| Hydrogen | 44.6278 | +2.62% |
| Solar | 44.06 | +1.36% |
Technology | ||
| Semiconductor | 572.68 | +1.17% |
| Electric Vehicles | 33.655 | +0.64% |
| Robotics & AI | 35.4 | +0.51% |
| FinTech | 25.3589 | -0.16% |
| Data Center & Digital Infrastructure | 27.84 | -0.45% |
| Cloud Computing | 28.39 | -1.90% |
| Cybersecurity | 44.71 | -4.16% |
ASX Today
Codan guides H1 FY27 group NPAT of not less than $160m vs $71.2m in the pcp and $175.2m for full-year FY26, with Communications revenue of $400-410m against $221.8m pcp and EBIT margin around 40% vs 26%. Conflict regions to make up ~50% of Communications revenue vs ~20% in the pcp. Targets FY27 Communications revenue growth of 30-40% (CDA)
Develop Global hands down maiden FY27 guidance of 775-875kt at 2.7% CuEq from Woodlawn for 21-23.5kt contained metal, with Pioneer Dome DSO starting in the December quarter at 650-750kt and 1.2% Li₂O. Growth capex of $411-458m is weighted to Yitirrti construction, with mining services revenue of $100-110m (DVP)
GR Engineering Services closes its SPP at the $10m target after $32.5m in applications from 1,337 holders, forcing a pro rata scale-back. Around 1.6m shares issue 30 September at $6.10, matching the August placement that raised $100m (GNG)
Megaport signs three AI infrastructure contracts worth ~$978.6m TCV with ~$322.6m in prepayments, lifting strategic contract TCV since April to ~$2.3bn and pro forma group ARR to ~$1.1bn. Upgrades FY27 revenue guidance to $720-810m from $620-730m and EBITDA margin to 42-44% from 38-40%, with capex rising to $1.78-1.88bn (MP1)
Navigator Global Investments sells down Invictus Capital Partners as New York Life Investment Management takes a 60% stake, with the residual 40% to be bought out in 2031. NGI books net upfront proceeds of ~US$40-43m plus an earn-out of up to US$32m in 2030 and retains distribution exposure through FY27-FY31 (NGI)
SRJ Technologies wins a US$1.234m LNG controls upgrade purchase order through CAPSA for a National Oil Company, marking its entry into the Middle East offshore LNG market. About US$300k lands in FY26 with the balance in FY27 (SRJ)
Tungsten Mining receives non-binding indicative debt terms from multiple financiers, with most supporting up to 70% gearing on Watershed, or ~$200m against a $274m pre-production capital cost. Deliberately sequencing Watershed ahead of Mt Mulgine and progressing a proposed US listing alongside offtake talks (TGN)
What To Watch Today
Commodities copped a beating. The selling started on Monday morning and persisted through to US market close. Chinese lithium carbonate futures tanked 5.6%, Silver tumbled 5.6%, palladium down 4.5%, gold dipped 3.9% to US$4,115/oz and copper fell 2.4% to US$6.63/lb. Moves of these magnitudes are pretty rare. Yields are the likely culprit, as they continue to trade vertical. The 10-year hit a fresh 19-year high of 5.23%, up almost 50 bps this month. This drove broad-based selling across our overnight ETF watchlist, with Gold Miners (-5.3%), Silver Miners (-4.9%), Rare Earths/Strategic Metals (-3.2%) and Uranium (-1.9%) trading sharply lower. Surprising to see Copper Miners (-1.7%) show some relative strength and also bounce off session lows of (-3.3%). NYSE-listed BHP shares finished (-0.4%) lower, well-above session lows of (-2.4%).
Defensives on the rise: Staples, healthcare and energy were the only S&P 500 sectors to finish higher. Locally, CSL rallied another 2.8% on Monday to a seven-month high. The stock has almost doubled from its 3-Jun low of $90 and is now up 5.4% YTD.
RBA decision: The RBA is widely expected to hike rates by 25 bps to 4.60% at 2:30 pm AEST. Expect hawkish commentary to follow, likely pointing to multiple hikes through to mid-to-late 2027.
Key Events
Stocks trading ex-dividend:
Tue 29 Sep: Acrow (ACF) – $0.014, DPM Metals (DPM) – $0.042, EVZ (EVZ) – $0.006, Rural Funds Group (RFF) – $0.029, Centuria Industrial REIT (CIP) – $0.043, Centuria Office REIT (COF) – $0.022, Tasmea (TEA) – $0.085, Cadence Capital (CDM) – $0.03, Cadence Opportunities Fund (CDO) – $0.075, Charter Hall Social Infrastructure REIT (CQE) – $0.045, Charter Hall Long Wale REIT (CLW) – $0.064, Charter Hall Retail REIT (CQR) – $0.066, Ram Essential Services Property Fund (REP) – $0.01, Arena REIT (ARF) – $0.045, Waypoint REIT (WPR) – $0.043, iShares S&P Mid-Cap ETF (IJH) – $0.00, iShares S&P 500 ETF (IVV) – $0.00, iShares S&P Small-Cap ETF (IJR) – $0.00
Wed 30 Sep: Staude Capital Global Value Fund (GVF) – $0.033, Nick Scali (NCK) – $0.39, Sims (SGM) – $0.20, Cedar Woods Properties (CWP) – $0.25, Genusplus Group (GNP) – $0.036
Thu 1 Oct: CUE Energy Resources (CUE) – $0.003, Imperial Pacific (IPC) – $0.08, Kip McGrath Education Centres (KME) – $0.06, London City Equities (LCE) – $0.025, Pengana Global Private Credit Trust (PCX) – $0.013, Vulcan Steel (VSL) – $0.038, WAM Strategic Value (WAR) – $0.033
Fri 2 Oct: NRW Holdings (NWH) – $0.145, Steamships Trading Company (SST) – $0.093
Other ASX corporate actions today:
Dividends paid: Pro Medicus (PME), Commonwealth Bank of Australia (CBA), Fortescue (FMG), Super Retail Group (SUL), Netwealth Group (NWL), TPG Telecom (TPG)
IPOs: None
AGMs: None
Economic calendar (AEST):
2:30 pm: RBA interest rate decision