In a nutshell:
Major US benchmarks finished higher and near best levels as hopes of a US-Iran breakthrough pulled oil lower and paused the Treasury rout
Though Trump rejected Iran's Hormuz proposal over the weekend, undercutting the de-escalation bet behind Friday's oil selloff, while Tehran says it will not soften its conditions
US and China agreed tariff relief on non-sensitive goods and a truce extension into January as Xi wrapped his Washington visit, with Beijing also committing to multi-year US coal purchases
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,743 | +0.51% |
Dow Jones | 51,829 | +0.93% |
NASDAQ Comp | 27,069 | +0.48% |
Russell 2000 | 2,838 | +0.07% |
Global Indices | ||
 S&P/TSX | 35,801 | +0.26% |
 Shanghai Composite | 3,888 | -1.22% |
 DAX | 25,409 | +0.56% |
 Hang Seng | 24,510 | -1.01% |
 Nifty 50 | 73,896 | +0.43% |
 Nikkei 225 | 66,364 | +1.30% |
 FTSE 100 | 10,695 | +0.14% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,285.0 | +0.24% |
 Copper | 6.7 | -0.34% |
 WTI Oil | 92.41 | -2.33% |
Currency | ||
 AUD/USD | 0.7015 | +0.01% |
Cryptocurrency | ||
 Bitcoin (USD) | 84,483 | +0.26% |
 Ethereum (AUD) | 3,812 | -0.38% |
Miscellaneous | ||
US 10 Yr T-bond | 5.184 | +0.43% |
VIX | 14.87 | -5.11% |
US Sectors
Sector | % Chg |
|---|---|
| Information Technology | +0.99% |
| Industrials | +0.94% |
| Financials | +0.53% |
| Consumer Staples | +0.51% |
| Health Care | +0.49% |
| Utilities | +0.39% |
Sector | % Chg |
|---|---|
| Materials | +0.29% |
| Consumer Discretionary | +0.05% |
| Real Estate | -0.36% |
| Communication Services | -0.65% |
| Energy | -0.87% |
S&P 500 Session Chart
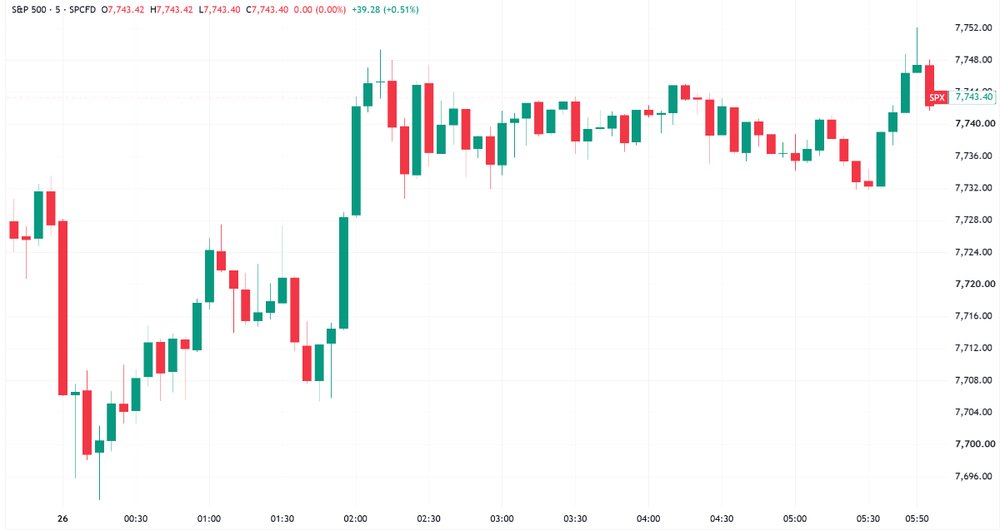
S&P 500 made gains after hopes of a Iran-US breakthrough and finished near best levels (Source: Trading View)
Overnight Markets
Major US benchmarks higher and just off best levels on hopes of Iran-US breakthrough early in the session
S&P 500 added 1.2% and the Nasdaq 2% over the week, with both indices still close to record highs, and the Dow flat after Friday's gains
Breadth held up with eight of the 11 sectors making gains, Tech drove the winners while Real Estate, Communication Services and Energy were in the red
Treasury yields steadied after a bruising week with the 10-year down 0.8% after reaching its highest since June 2007 on Thursday, the 2-year down 7 bps at 4.86% pulling back from a two session climb, while the 30-year held ground at 5.49% its highest since 2004
Iran diplomacy hopes drove the rebound as oil slid on a New York Times report that Tehran proposed reopening Hormuz and reviving nuclear talks, calming the Treasury volatility that has rattled markets (BBG)
Brent fell 3.2% to US$101.8 a barrel halting a two day win streak, on US-Iran truce hopes while Kpler data showed Hormuz crude flows steady at 33.7m barrels last week (RT)
Corporate bonds have held up through the global government bond selloff, but Bloomberg's credit weekly warns a rising rates-market fear gauge signals that resilience may not last (BBG)
Wall Street is growing more sceptical of the AI data centre boom as higher rates, local opposition and permitting delays add cost and uncertainty to projects (BBG)
Stocks
Microsoft rallied 3.7%, lifting its 2026 gain to 7%, after unveiling new Copilot capabilities including a coding tool and an always-on AI agent, leading a broader tech bid that also lifted Qualcomm 4% and Dell 5% (RT)
Meta's Muse AI agent is emerging as a major catalyst, with analysts arguing "Muse over Metaverse" could see investors value the stock at 25 to 30 times 2028 earnings, implying shares of US$1,000 or more (Investing)All
Alphabet plans to send an experimental satellite into orbit via SpaceX, carrying chips capable of answering simple AI queries, as the first step of its Project Suncatcher orbital data centre push (YF)
Iran & Energy
Trump rejected Iran's proposal to reopen Hormuz, saying on Saturday that Tehran wants the strait opened immediately because it is losing badly, as Houthi fire targeted the Saudi capital over the weekend (BBG)
Iran says it will not soften its conditions, with Foreign Minister Araghchi saying late Saturday Tehran has yet to receive a formal US response via mediators Qatar and Pakistan on its seven-day plan (BBG)
US envoy Mike Waltz said Trump doubts Iran is acting in good faith, while Araghchi told NBC on Sunday that diplomacy had not failed and suggested Washington had not fully read Tehran's proposal (TN)
Trump expects Iran negotiations to continue despite rejecting the ceasefire offer, with reports he is privately sceptical Tehran will meet his demands, weeks out from the US midterms (USA)
Trump posted a "Trump Strait" image of Hormuz to Truth Social, while President Pezeshkian told Al Jazeera the dispute can be resolved through negotiation, not force, but that Iran does not trust Washington (NBC)
Tehran's plan closely resembles the June memorandum of understanding, which collapsed after disputes over vague wording, including language on who would control the strait, before strikes resumed (NPR)
Saudi-led coalition intercepted two ballistic missiles and two drones fired by the Houthis towards the kingdom early Saturday, hours after Saudi, Pakistani and Turkish military chiefs met in Riyadh to review threats (The National)
Trump's UN posturing has not moved Xi, Putin or Tehran, Bloomberg Opinion columnist Hal Brands wrote, arguing the President is stuck in a stalemate with China and facing rivals that refuse to yield (BBG)
Tariffs & Trade
US and China agreed to cut tariffs on US$30bn of non-sensitive goods in each direction and launch an AI dialogue, covering US farm goods, wood and cosmetics and Chinese appliances, toys and decorations (RT)
China will import at least 10m tonnes of US coal in both 2027 and 2028, the White House said, under agreements reached through the newly operational US-China Board of Trade (BBG)
Xi's first formal Washington visit in 11 years delivered few concrete agreements beyond extending the trade truce until January, with Xi also promising to send a pair of pandas to Atlanta (CNBC)
Treasury Secretary Scott Bessent said China has met its 25m-tonne soybean commitment but remains behind on roughly US$17bn of other agricultural purchases, as talks eye a "30 by 30" goods deal (BZ)
Central Banks
RBA decision due 29 September, with all 29 economists surveyed by Bloomberg tipping a 25bp hike to 4.60%, the highest cash rate since November 2011 (ABC)
Fed's Hammack said the biggest inflation risk is an inflationary mindset setting in after more than five years above target, adding the Fed needs policy at a restrictive stance (RT)
Economy
US consumer sentiment fell to a four-month low of 48.1 in September's final University of Michigan reading, above 47.6 ests, as year-ahead inflation expectations jumped to 4.6% from 4.0%, the highest since June (QZ)
US durable goods orders were flat in August month-on-month against ests of a 0.3% decline, following a downwardly revised 0.9% gain in July, while orders excluding defence rose 0.1% (CNBC)
The 30-year US mortgage rate climbed to 7.45%, its highest since 2024, as the surge in 10-year Treasury yields fed through to household borrowing costs (CNBC)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Silver Miners | 91.56 | +0.66% |
| Gold Miners | 92.87 | +0.56% |
| Copper Miners | 86.73 | +0.56% |
| Lithium & Battery Tech | 69.02 | +0.29% |
| Uranium | 40.91 | +0.12% |
| Steel | 104.798 | -0.03% |
| Strategic Metals | 66.66 | -0.40% |
Industrials | ||
| Global Jets | 28.98 | +1.83% |
| Construction | 92.6091 | +1.47% |
| Aerospace & Defense | 213.81 | +0.49% |
| Agriculture | 28.54 | -0.04% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 209.77 | +0.25% |
Renewables | ||
| Hydrogen | 44.6278 | +2.62% |
| Solar | 44.06 | +1.36% |
Technology | ||
| Semiconductor | 572.68 | +1.17% |
| Electric Vehicles | 33.655 | +0.64% |
| Robotics & AI | 35.4 | +0.51% |
| FinTech | 25.3589 | -0.16% |
| Data Center & Digital Infrastructure | 27.84 | -0.45% |
| Cloud Computing | 28.39 | -1.90% |
| Cybersecurity | 44.71 | -4.16% |
ASX Today
Capral lifts the rate of its on-market buy-back, targeting 40-50% of volume traded over the preceding 20 business days through to 17 December, capped at 60%. No change to the 10% maximum or March terms (CAA)
Northern Star Resources rejected an unsolicited 14 September proposal from Gold Fields of 0.3125 CDIs plus $7.25 cash per share, implying $27.00 and a $38.7bn equity value. Board says it materially undervalues the tier-1 asset base and is opportunistic ahead of Fimiston commissioning. Gold Fields' share price fall since cuts the implied value to $25.19 (NST)
St Barbara lifts 15-Mile Ore Reserves 17% to 1.44Moz in an updated PFS, extending mine life to 13 years at an average 106kozpa. Initial capital C$289m ($315m), AISC US$1,098/oz and post-tax NPV5 of $1.71bn at US$3,000/oz gold. Feasibility pulled forward to Q3 FY27, FID still Q4 FY27 (SBM)
St Barbara accelerates Nova Scotia exploration, prioritising the Old Austen down-plunge prospect and Mill Shaft West after historic intercepts including 1.84m @ 163.7 g/t Au below the open pit reserve limit. A 22km² UAV magnetic survey lands early October ahead of drilling from Q4 FY27 (SBM)
Synlait Milk posts FY26 reported EBITDA of NZ$8.1m and underlying NZ$46.3m on revenue of NZ$1.94bn, with a reported net loss of NZ$75.4m. Second half swung to NZ$42.8m EBITDA and a NZ$5.2m profit as manufacturing stability returned. Balance date moves to 31 December, no transitional period guidance (SM1)
What To Watch Today
Not a whole lot: Friday was one of those encouraging US sessions, where major benchmarks finished broadly higher, breadth was positive and, oil and yields moved in the right direction. That translated into modest gains of ~0.5-1.0% across most resource-related ETFs on our overnight watchlist, while healthcare and biotech, software and energy edged slightly lower. Some of that optimism has unwound this morning after Trump rejected Iran's Hormuz proposal over the weekend. There's a lot of dust still to settle, so we'll have to see where the week takes us.
Key Events
Stocks trading ex-dividend:
Mon 28 Sep: Shine Justice (SHJ) – $0.025, Viva Leisure (VVA) – $0.03, Lindsay Australia (LAU) – $0.017
Tue 29 Sep: Acrow (ACF) – $0.014, DPM Metals (DPM) – $0.042, EVZ (EVZ) – $0.006, Rural Funds Group (RFF) – $0.029, Centuria Industrial REIT (CIP) – $0.043, Centuria Office REIT (COF) – $0.022, Tasmea (TEA) – $0.085, Cadence Capital (CDM) – $0.03, Cadence Opportunities Fund (CDO) – $0.075, Charter Hall Social Infrastructure REIT (CQE) – $0.045, Charter Hall Long Wale REIT (CLW) – $0.064, Charter Hall Retail REIT (CQR) – $0.066, Ram Essential Services Property Fund (REP) – $0.01, Arena REIT (ARF) – $0.045, Waypoint REIT (WPR) – $0.043, iShares S&P Mid-Cap ETF (IJH) – $0.00, iShares S&P 500 ETF (IVV) – $0.00, iShares S&P Small-Cap ETF (IJR) – $0.00
Wed 30 Sep: Staude Capital Global Value Fund (GVF) – $0.033, Nick Scali (NCK) – $0.39, Sims (SGM) – $0.20, Cedar Woods Properties (CWP) – $0.25, Genusplus Group (GNP) – $0.036
Thu 1 Oct: CUE Energy Resources (CUE) – $0.003, Imperial Pacific (IPC) – $0.08, Kip McGrath Education Centres (KME) – $0.06, London City Equities (LCE) – $0.025, Pengana Global Private Credit Trust (PCX) – $0.013, Vulcan Steel (VSL) – $0.038, WAM Strategic Value (WAR) – $0.033
Fri 2 Oct: NRW Holdings (NWH) – $0.145, Steamships Trading Company (SST) – $0.093
Other ASX corporate actions today:
Dividends paid: IRESS (IRE), Insurance Australia Group (IAG), Prime Financial Group (PFG), Comms Group (CCG), Saferoads (SRH), Newmont (NEM)
IPOs: None
AGMs: None
Economic calendar (AEST):
No major economic announcements.