ASX 200 Live Today - Wednesday, 26th August
The S&P/ASX 200 gave back early gains on sharp declines for Tech, Energy and Telcos. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Wednesday, August 26. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Reporting season is heating up and we've got you covered. Our reporting season calendar has over 250 stocks plus earnings and dividend estimates.
ASX 200 gives back early gains
[2:30 pm] That's a wrap! The ASX is down 18 pts (-0.19%), a sizeable reversal from this morning's high of 56 pts (+0.61%). The fade was pretty broad. Staples was up as much as 3% in early trade and now holds just 1.8%. Materials rallied a little over 1% and now sits up 0.6%. Financials traded 0.3% higher and are now down by the same margin. Telcos (-1.5%), Energy (-2.0%) and Tech (-2.8%) have chopped around the same levels all session. A dicey market overall, with the exception of Materials, which is on track for a third straight day of record highs. Even there, BHP (+0.35%) faded a session high of 1.6% and is starting to look heavy after surging around 10% in the last seven sessions.
I've been soloing the blog for reporting season, and on days like this a handful of results fall through the cracks. So here are a few things we missed this morning.
Sandfire (+7.2%) is trading at fresh all-time highs after reporting its FY26 result this morning, where strong copper prices and low treatment charges drove a threefold lift in underlying earnings, with FY27 production guidance landing in line and capex below ests. The below ests are only Macquarie ests and not consensus.
Sales revenue up 41% to US$1,654m vs US$1,654m ests (in line), a full year record on strong commodity markets and low TC/RCs
Operational EBITDA up 57% to US$960m vs US$922m ests (4% beat)
Profit after tax up 294% to US$354m vs US$331m ests (7% beat)
Operating cash flow up 54% to US$887m vs US$773m ests (15% beat)
Net cash of US$353m against net debt of US$123m a year earlier, hitting the targeted net cash position and well ahead of the geared position ests implied
Maiden fully franked final dividend of 35 cps (US ~22.8 cps) vs. US 17.0c ests (34% beat)
FY27 copper equivalent guidance of 150kt to 166kt, with the 158kt midpoint 2% below the 160.7kt est
FY27 capex guided to US$299m against US$329m ests (9% below), including US$51m for the Kalkaroo PFS and exploration projects
FY27 operating costs of US$668m to US$685m, broadly flat on FY26 and below the US$817m Macquarie carries, though definitional differences on cost scope apply
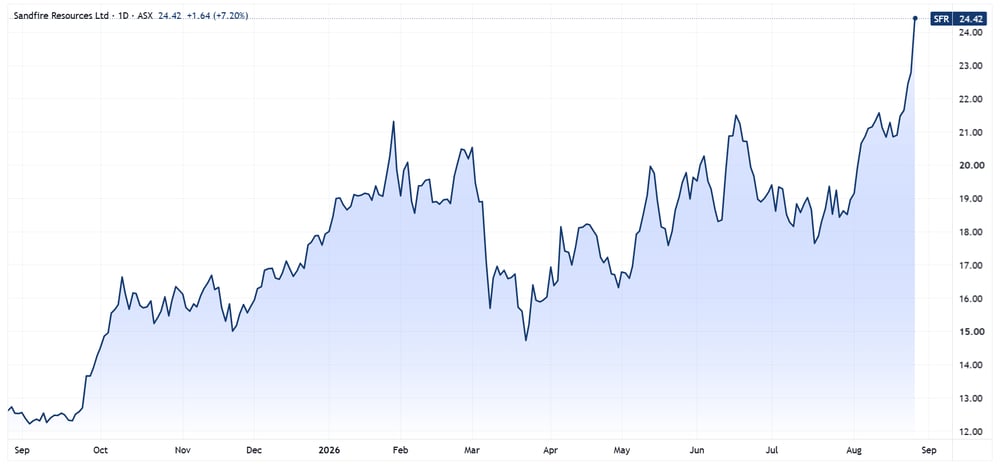
Sandfire 12-month price chart (Source: TradingView)
Mattress maker Koala (which IPO'd on 31 March at $3.40 per share), rallied 6.1% on a better-than-expected FY26 result.
Revenue up 24.4% to $332.3m in constant currency vs $332.1m ests (in line)
Australia revenue up 10.7% to $166.7m in a challenging consumer environment, with contribution margin up 3.0pp to 29.8% and the marketing ratio stable at 16.7%
US was the fastest growing market, with revenue up 67.6% in local currency to $74.9m and gross margin up 3.8pp to 69.8%
Japan revenue up 23.5% in local currency to $89.4m, with contribution profit up 38.0% and contribution margin up 5.1pp to 28.6%
Pro forma EBITDA up 139.2% to $27.9m vs $24.9m ests (12% beat) and ahead of the $24.8m prospectus forecast (13% beat)
Statutory NPAT of $24.6m vs. a $4.6m net loss a year ago
Gross margin up 2.9pp to 65.3%, with implied gross profit of around $217m about 2% ahead of ests
Ordered revenue up 27% in constant currency in the eight weeks to 23 August, or 20% in reported dollars, pointing to momentum carrying into FY27
UK entry completed as the fourth market, against an estimated $52bn addressable opportunity across sitting furniture and mattresses
No dividend declared, consistent with ests, though management flagged a pathway to dividends given the balance sheet position
No FY27 guidance provided beyond the trading update and four stated strategic priorities
Some pretty big numbers for a ~$310 million market cap company (~12.5x today's earnings, company is also debt free with $71.2m cash). Though Koala is extremely illiquid and thinly traded. It's 20-day average volume sits at just ~84,000 shares (or approx $300k).
Wisr is another illiquid name, trading at a market cap of ~$48 million. It delivered an inaugural FY26 cash NPAT of $1 million, on record loan originations of $695.3 million, up 65% year-on-year. The stock is up 14.8% to 3.1 cents and flat year-to-date. What makes Wisr interesting is that its targeting FY27 cash NPAT of "at least $5m" and expects to grow cash NPAT "substantially in FY28".
Worley FY26 earnings call highlights: FY27 growth lands below the FY30 ambition and skews to the second half
[1:45 pm] Management conceded FY26 fell short on the Middle East conflict and currency, and the FY27 guide sits under the double-digit trajectory Worley laid out at its May investor day.
On the size of that skew: asked whether first half earnings would grow, "You would have traditionally seen a trend for Worley that probably put our earnings at around probably 45%-55% type of weighting... We can certainly expect that earnings skew to be greater than that into the second half for FY27"
On getting back to double-digit growth: asked if FY27 guidance being below the FY30 target left line of sight to a recovery, "Yeah, we do... some of those projects that we have won, been awarding in the early phase of, that will get delivery traction in the latter part of 2027 into 2028"
On margins staying flat: "If we look at the EBITA percentage margin, you are right, we would likely expect that to be relatively flat on what we saw in FY 2026... The margin we are winning work at is not changing... Any margin shift is associated with mix rather than the margin we are actually bidding and winning work at"
On the Middle East: "We are operating in this space in the middle where it is neither all-out war nor complete peace... those projects that were deferred at the beginning of the war, at the end of February, are now back on the table", with the $58m FY26 hit "really around revenue and margin deferral, project deferral, not to do with their restructuring"
On the backlog step down: backlog fell to $13.8bn from $16.7bn at the half, with management arguing "the backlog is a point in time" and pointing to bookings and pipeline instead, noting Connah's Quay and TC Energy "once they get FID, will make a significant contribution to the backlog"
Company page: Worley (WOR)
Helloworld Travel FY26 earnings call highlights: Middle East conflict dents Q4, consumer demand holds
[1:45 pm] Management framed a soft June quarter as a one-off hit from the Iran conflict, with forward bookings recovering and the CEO arguing travel spending behaves nothing like discretionary retail.
On the Q4 hit: "We were expecting growth, certainly double-digit growth of around 15%-20%. As it turned out, it was only 4%, and that was a result of the many cancellations that came in once the war kicked off in Iran, and the Middle Eastern carriers stopped flying here for a period of time"
On where that money went: "Many customers got refunds, nearly $200 million worth. Most of those customers reinvested that either in booking with other carriers or booking later in the year"
On carrier capacity now: "Both Qatar Airways and Emirates are pretty much back to their pre-war, pre-conflict numbers", though "we have had issues with Etihad Airways, insofar as they have not yet got back to a schedule that resembles their pre-Middle Eastern hostilities commencing"
On the consumer: "Travel is not performing as other retailers are performing. We have all seen the commentary from JB Hi-Fi... I do not believe that travel is a discretionary part of the household budget. I think it is likely a non-discretionary part of it"
On New Zealand weakness: "It is not so much that the number of passengers has declined. The average expenditure of the passengers has declined. They are taking shorter haul holidays. They are taking holidays to cheaper destinations", with FY27 TTV growth there flagged at "somewhere between 5% and 8%"
On forward bookings: "The United States is our second-largest destination, followed by Italy. From the beginning of July, we have seen a double-digit growth in bookings for cruise... we have started the year very well", with formal guidance held back until the AGM
Company page: Helloworld Travel (HLO)
WiseTech FY26 earnings call highlights: commercial model refinements cost CargoWise growth
[1:10 pm] The call was dominated by why CargoWise growth undershot, what changed in the new pricing model, and how much of FY27 rests on a second-half skew.
On missing the CargoWise guide: "We landed at 11% growth for CargoWise, and we had put an assumption in we'd land at 14%-21%... the refinements that we made to the model in the second half really drove that slightly lower CargoWise growth"
On what the refinements actually were: "These were not rebates or incentives or anything like that. These were changes to how the commercial model actually works in terms of timing of billing and operationalising of how the commercial model works for our customers"
On pricing: "We've not disclosed the timing of the price increase, but I think most people will be aware that we did not put a price increase through for a number of customers on CVP on 1 July, and so that's obviously had an impact on the CargoWise growth rates in the first half"
On churn: CargoWise attrition "remains below 1% as it has been for the last 14 years", but at e2open "subscription revenue attrition continued during the year, reflecting the time required for these initiatives to take effect", with FY27 e2open revenue guided flat
On the FY27 second-half skew: exit rate was "about 10%" with first half FY27 "coming down slightly at around 9%", and the pickup depends on "STL to CVP conversion for the remaining 5% of our customers", AI monetisation and VerifyWise, against guidance of $1.48bn to $1.54bn revenue and underlying EBITDA of $725m to $780m
Company page: WiseTech Global (WTC)
Duratec FY26 earnings call highlights: record order book sets up a delivery year
[1:09 pm] Management framed FY26 as a setup year where revenue slipped on project timing but margins and the order book both hit records.
On the revenue miss: "Our FY26 revenue result was lower than anticipated due to the timing of some of the larger projects, which have now landed, but well later into the financial year than originally anticipated"
On the order book: "We converted tenders into the record order book of $650.8 million, up 66.9% from FY 2025... During FY 2027, we anticipate delivering between 70% and 80% of this along with the standing start MSA work"
On the FY27 setup: "These jobs are underway now, so we are not expecting that slippage to occur. Then you add the MSA work, you automatically get yourself to some pretty solid numbers... We have had the best standing start by a long shot than we ever have in the history of the company"
On margins and operating leverage: "We think that is sustainable, particularly as the acquisitions we have made... they are on the higher end of the margin profile... we have not had the opportunity to take advantage of operational leverage yet. The business is set up to handle this type of revenue into the $700 million"
On the AUKUS opportunity: "Next door to that is Henderson... There's a $24 billion plan spend. That number has just been revised, or other people think it's a lot more... We have also got that ISO accreditation, 19443, which allows us in that nuclear supply chain. That is a big target for us"
Company page: Duratec (DUR)
Paladin Energy FY26 earnings call highlights: utilities shift from just in time to just in case
[1:07 pm] Management framed FY26 as the year the Langer Heinrich ramp-up finished, with attention now turning to Patterson Lake South and a term uranium market that is pulling utilities further out the curve.
On the result: "Revenue increased 71% to $304 million, supported by higher sales volumes and an average realized price of $70 per pound. We reported gross profit of $52 million and generated positive operating cash flow of $37.7 million for the year. Net loss after tax improved significantly to $9.1 million"
On the term versus spot gap: "As we come into the WNA, people are recognising that that delta needs to narrow and term prices aren't coming down. So there's only one way for the spot price to go"
On utility buying behaviour: "We are seeing requests for proposals in the 2030s, well into late 2030s, in fact. Which has been quite unusual with utilities being a lot more forward-thinking"
On demand drivers: "We've got these additional countries now entering the mix with India, and with their aggressive reactor build-out programs... All these factors are really feeding into a market that requires supply into the long term"
On PLS funding: "Our key focus at the moment is really on ensuring we retain flexibility, and that flexibility is really ensuring we can project finance if we want to... that's not the only path, but probably the longest lead transaction"
On FY27 trading so far: "The week outage is complete as planned, and we are operating in accordance with our budgeted performance"
Company page: Paladin Energy (PDN)
Australian Retirement Trust builds biggest yen overweight in years
[1:05 pm] Australia's second-largest pension is making a contrarian bet that markets are underpricing Bank of Japan rate hikes.
Biggest yen overweight in years, with ART, which manages about $370bn, adding to the trade over the past six months as the yen weakened toward 160 per dollar, funded partly by trimming US dollar exposure
The thesis is two-part, with senior portfolio manager Jimmy Louca arguing the drag from higher energy prices is already priced in while the odds of BOJ hikes look too low, and "any reversion in those two factors should support the yen"
Fair value for dollar-yen seen around 150 and potentially the high 140s, against roughly 159.21 currently, implying about 6% upside for the currency
Swaps price an 80% chance of a September BOJ hike and a move fully priced by October, with Louca seeing scope for the central bank to signal two hikes before energy costs complicate the path
Sizing is modest, sitting within ART's dynamic asset allocation program across diversified options and accounting for about half a percentage point in the high-growth option
Also underweight US Treasuries by about half a percentage point, with the 30-year seen pushing toward 5.5% on the view that the Treasury's latest buyback plans delay rather than prevent upward yield pressure
Source: Bloomberg
Copper stocks trend higher
[11:38 am] Copper stocks are trading broadly higher after copper prices advanced 1.5% overnight to US$6.80/lb. Sandfire surged to all-time highs off the back of its FY26 result this morning, though a few names like Capstone Copper, BHP and Cyprium are starting to stall after some massive gains in recent weeks.
Ticker | Company | % Chg | Price | 1 Month | YTD |
|---|---|---|---|---|---|
HGO | Kantra Copper | 12.9% | $1.05 | 20.7% | 45.8% |
SFR | Sandfire Resources | 7.4% | $24.47 | 30.0% | 36.2% |
29M | 29Metals | 5.9% | $0.36 | 44.0% | -31.6% |
CPM | Cooper Metals | 4.1% | $0.08 | 24.2% | 37.5% |
HCH | Hot Chili | 3.3% | $1.77 | 18.1% | 27.5% |
AIS | Aeris Resources | 2.6% | $0.48 | 25.5% | -20.5% |
FFM | Firefly Metals | 2.4% | $1.95 | 15.1% | -5.6% |
MC2 | Marimaca Copper | 1.5% | $8.28 | 8.9% | -33.8% |
CSC | Capstone Copper | 0.8% | $16.56 | 24.1% | 9.2% |
BHP | BHP Group | 0.7% | $68.15 | 13.5% | 49.7% |
RIO | Rio Tinto | 0.7% | $180.49 | 10.6% | 22.9% |
AR1 | Austral Resources Australia | 0.0% | $0.07 | 4.6% | 19.3% |
CYM | Cyprium Metals | 0.0% | $0.57 | 33.9% | 6.7% |
Citadel Securities flips bullish on long bonds after 'cruel summer' call
[11:36 am] The firm's head of macro strategy now sees risks skewed toward a rally, pointing to stretched short positioning and softer data.
Frank Flight reversed his bearish stance, telling clients the asymmetry now favours lower long end yields, barely a month after warning of a difficult summer for bond investors
Trend-following positioning is the core of the call, with Citadel's CTA simulation showing bearish exposure "quite stretched" versus recent history, limiting further selling on dips while a rally could force short covering
Cross-asset model supports the view, with yields falling in 71% of 64 comparable growth and policy episodes since 2003 over the following 120 days, for an average decline of 25bps
Thirty-year yields hit an almost two-decade high last week, driven by inflation, fiscal deficit concerns and heavy tech issuance funding AI infrastructure
Treasury has already responded, with Bessent announcing plans to lift buybacks of bonds maturing between 10 and 30 years to stem the selloff
Source: Bloomberg
ASX 200 higher as Woolies and Miners rally, Tech and Energy stocks dip
[10:49 am] The ASX 200 is currently up 32 pts (+0.35%) and on track to record three straight days of gains. The Materials Index is now on a five-day win streak, including three-straight record highs as copper and gold miners surge. Woolworths (+5.4%) is trading sharply higher off the back of its FY26 result, now at the highest since September 2021. Wisetech (-6.3%) has tanked the tech sector, while Energy stocks pull back on a weak overnight session for oil prices.
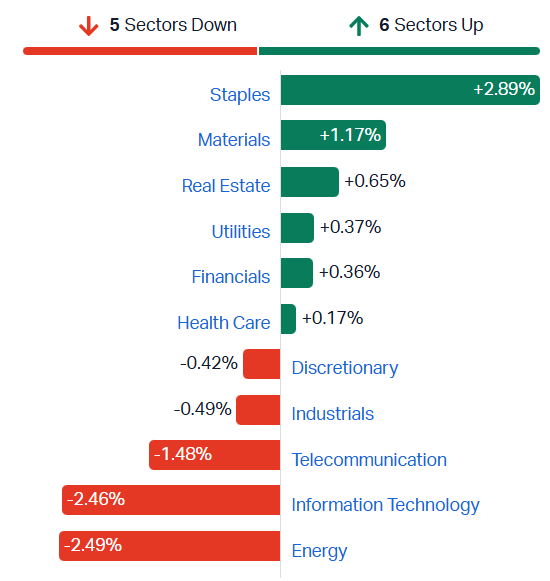
S&P/ASX 200 sectors (Source: Market Index)
The data vs. how the stocks performed
[10:34 am] Here's a bit of an educational post about why consensus data matters. Worley reported its FY26 result this morning, which featured:
Aggregated revenue flat at $12,023m vs $11,784m ests (2% beat)
Underlying NPATA down 16.8% to $395m vs $380m ests (4% beat)
Final dividend of 25 cps unfranked takes the full year to 50 cps vs 48.8 cps ests (2% beat), unchanged on FY25
FY27 guidance for mid to high single digit growth in both aggregated revenue and underlying EBITA, with revenue phasing broadly even but EBITA more heavily H2-weighted than usual
You might notice some posts have italic text at the bottom. That's just me rambling about some other data points that may add some context to the announcement/result.
Some context on the market reaction. UBS was expecting FY27 revenue and EBITDA growth of 15% and 19% respectively, so guidance for mid to high single digit growth on both lines is a material miss.
Worley had already downgraded FY26 guidance on 25 June, which sent the stock 10% lower on the day to $11.08. But it has traded sideways since rather than continuing to bleed, so the market wasn't positioned for another leg down.
This morning the stock opened 3.6% lower at $10.70 before hitting an intraday low of -13.4% at $9.61, and is now working its way off those lows. What we're watching is a price discovery process, with the market weighing an in-line FY26 result against a materially weaker FY27 outlook. Given the size of the miss, analysts will probably cut their earnings forecasts, which leads to a lower target price, and possibly rating downgrades.
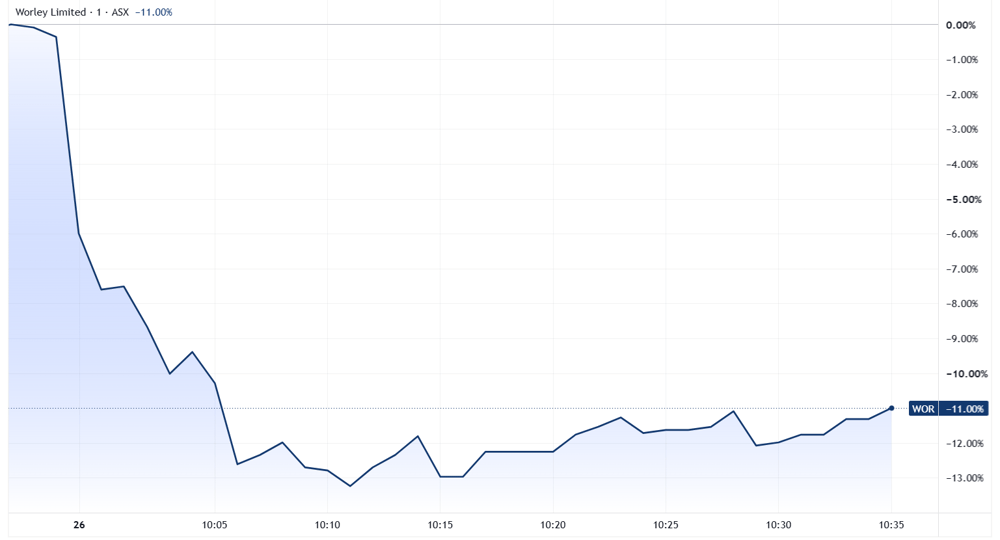
Worley intraday price chart (Source: TradingView)
Top ASX 200 gainers
[10:26 am] Lovisa rallies on a fairly in-line FY26 result (but first eight weeks of FY27 has total sales up 16.4%), Perseus surges on a new dividend policy, Sandfire reports a 294% jump in FY26 NPAT to $354m and gold stocks continue to trend higher.
Ticker | Company | % Chg | Price |
|---|---|---|---|
LOV | Lovisa | 15.43% | $28.28 |
PRU | Perseus Mining | 8.40% | $6.65 |
SFR | Sandfire Resources | 6.85% | $24.34 |
ALK | Alkane Resources | 4.77% | $1.98 |
PDN | Paladin Energy | 4.77% | $12.53 |
SLX | Silex Systems | 4.60% | $5.91 |
MI6 | Minerals 260 | 4.57% | $0.96 |
WOW | Woolworths Group | 4.35% | $40.54 |
WGX | Westgold Resources | 3.83% | $6.77 |
NEC | Nine Entertainment Co | 3.59% | $1.01 |
CIA | Champion Iron | 2.80% | $3.67 |
KCN | Kingsgate Consolidated | 2.64% | $5.45 |
OBM | Ora Banda Mining | 2.52% | $1.63 |
AAI | Alcoa Corporation | 2.52% | $71.13 |
RMS | Ramelius Resources | 2.52% | $4.07 |
PNR | Pantoro Gold | 2.39% | $2.57 |
NIC | Nickel Industries | 2.29% | $0.90 |
NEM | Newmont | 2.26% | $188.55 |
WAF | West African Resources | 2.24% | $3.89 |
CMM | Capricorn Metals | 2.20% | $18.14 |
Top ASX 200 losers
[10:26 am] Worley tumbles on a weaker-than-expected FY27 guidance, Domino's result was fairly in-line but same-store-sales for FY26 tumbled 4.1% (vs. ests of a 2.8% decline) and Energy stocks pull back on oil price softness.
Ticker | Company | % Chg | Price |
|---|---|---|---|
WOR | Worley | -10.77% | $9.91 |
DMP | Domino's Pizza | -9.06% | $18.26 |
DRO | Droneshield | -7.69% | $1.80 |
WTC | Wisetech Global | -7.41% | $42.10 |
FLT | Flight Centre | -6.79% | $12.08 |
XRO | Xero | -4.73% | $84.74 |
GQG | GQG Partners | -4.36% | $1.43 |
WDS | Woodside Energy Group | -4.11% | $31.65 |
NWL | Netwealth Group | -4.10% | $21.31 |
KAR | Karoon Energy | -3.68% | $1.70 |
DTL | Data#3 | -3.15% | $11.36 |
VNT | Ventia Services Group | -2.72% | $5.73 |
HUB | Hub24 | -2.64% | $76.11 |
STO | Santos | -2.58% | $7.94 |
ABB | Aussie Broadband | -2.56% | $4.57 |
TLS | Telstra Group | -2.55% | $4.58 |
AMC | Amcor | -2.35% | $65.70 |
ASX | ASX | -2.33% | $55.37 |
SLC | Superloop | -2.29% | $2.99 |
BPT | Beach Energy | -2.26% | $0.87 |
Netwealth delivers record result but flags margin step-down in FY27
[9:55 am] Income and earnings landed close to ests with NPAT slightly ahead, though the FY27 margin guidance points to a heavier investment year and a First Guardian compensation charge sits outside the underlying numbers.
Total income up 20.6% to $391.1m vs $394.3m ests (1% miss), a record on strong flows and market share gains
EBITDA up 18.0% to $192.9m vs $193.8m ests (in line), at a 49.1% margin in line with guidance excluding the Flux contingent consideration reversal
NPAT up 16.2% to $135.4m vs $133.7m ests (1% beat), with EPS up 16.0% to 55.2c
Final dividend of 21.0 cps fully franked takes the full year to 42.0 cps vs 43.2 cps ests (3% miss), up 9.1%
Total FUA up 20.3% to $135.7bn at year end (in-line with ests) and $138.8bn as at 21 August, with FUM up 27.9% to $34.6bn
First Guardian charge excluded from underlying, comprising a $100.7m compensation payment and $4.5m in legal and consulting fees, or $74m after tax
FY27 net flow guidance of $18bn to $20bn implies growth of 17% to 30%, a meaningful acceleration on FY26
FY27 EBITDA margin guided to around 47%, below the 47.5% implied by ests and a step down from 49.1%, on planned growth investment, with capitalised software spend of around $17m
Dx30 ambition to double FUA over four years, with margins trending back toward 50% as growth initiatives deliver scale
Company page: Netwealth Group (NWL)
Domino's grows profit as pricing reset trades volume for franchisee returns
[9:49 am] Sales went backwards across every region but franchise partner profitability hit a four-year high and the balance sheet was materially repaired.
Network sales down 6.8% to $3.87bn including store closures, with same-store sales of -4.1% against the -2.8% ests
Underlying EBIT up 1.0% to $200.1m vs $198m ests (1% beat), delivered despite a sharply lower sales base
Asia underlying EBIT up 19.7% despite same-store sales of -6.7%, driven by Japan store rationalisation, menu optimisation and cost discipline
ANZ underlying EBIT down 5.9% on same-store sales of -4.7%, as pricing resets and reduced discounting cut volumes and lower food and packaging costs were passed to franchisees
Europe underlying EBIT up 2.6% with same-store sales of -2.2%, BENELUX offsetting softer France and Germany in the second half
Underlying NPAT up 4% to $121.6m vs $118m ests (3% beat)
Franchise partner profitability up 11.3% to $105.7k rolling 12-month EBITDA per store, the highest in four years, with average store EBITDA margin lifting to 7.9%
Free cash flow of $164.1m, up $116.6m on FY25, cutting net debt by $227.8m and net leverage to 1.86x against a target below 2.0x
Final dividend of 32.5 cps unfranked up 51.2%, taking the full year to 57.5 cps
No FY27 guidance provided, with management framing the year around rebuilding profitable order growth rather than a return to broad discounting
Company page: Domino's Pizza Enterprises (DMP)
Nine lifts EBITDA 17% on continuing business as portfolio reshaping completes
[9:43 am] Divestments and the QMS acquisition have tilted the group toward growth assets, with a $481m Total TV impairment sitting alongside an $849m Domain gain.
Revenue up 3% to $2,189.0m on a continuing business basis, or up 1% to $2,407.0m pro forma including a full year of QMS
EBITDA up 17% to $378.8m continuing, with growth at Outdoor, Mastheads and Streaming & Broadcast, and pro forma EBITDA up 6% to $516.2m
EBITA up 6% to $235.3m and NPATA up 11% to $147.2m, with EPSA up 11% to 9.3c
Statutory net profit of $510.6m, comprising $142.4m from continuing operations, $849.4m from discontinued operations largely on the Domain sale, offset by a $481m non-cash Total TV impairment
Nine Outdoor contributed $55m EBITDA in its first three months, with pro forma FY26 EBITDA growth of 18%
Subscription revenue up 12% across Mastheads and Stan, with Stan delivering a record result led by Sports including Premier League and Olympics
Around $70m of maintainable cost efficiencies delivered, with Nine now expecting to exceed its three-year $160m target by the end of FY27
Final dividend of 3.0 cps unfranked takes the full year to 7.5c, flat on FY25
Leverage of 1.7x at year end, slightly better than prior guidance
FY27 pro forma revenue and EBITDA growth expected, with growth assets tipped to deliver more than 60% of revenue and around 70% of EBITDA, and QMS guided to double-digit pro forma EBITDA growth plus around $9m of synergies
Q1 trading is two-speed, with QMS revenue up mid-teens and digital subscriptions up mid single digits, against Total TV revenue down 7% to 8% on a later Block start and competing sports events
Total TV costs expected broadly flat in FY27 before the benefit of FY26 write-offs, with the broadcast ad market still short and difficult to forecast
Company page: Nine Entertainment (NEC)
WiseTech beats on EBITDA but FY27 revenue guidance lands below ests
[9:35 am] The e2open acquisition drove headline growth and cost synergies came through early, though the FY27 revenue range sits under where the market was positioned.
Revenue up 79% to US$1,395.9m vs US$1,407m ests (1% miss), within guidance and reflecting eleven months of e2open at US$541.2m
CargoWise revenue up 11% to US$756.9m, driven by customer growth, LGFF rollouts, M&A and the CargoWise Value Packs launched in December
Underlying EBITDA up 56% to US$644.5m at a 46% margin
Statutory NPAT of US$178.7m vs US$195m ests (8% miss)
Underlying NPAT rose 29% to US$313.5m
Around US$115m of annualised run-rate cost savings delivered, split US$64m from e2open, US$34m from the AI Transformation program and US$17m from efficiency initiatives
Operating cash flow up 29% to US$564.0m with underlying free cash flow up 67% to US$489.6m, cutting net leverage to 2.7x against a guided target of around 3x
Final dividend up 14% to 8.8 US cps fully franked vs. Macquarie ests of 8.5 US cps (3.5% beat)
FY27 revenue guidance of US$1.48bn to US$1.54bn, implies 6-10% growth, with the US$1,510m midpoint roughly 3% below the US$1,562m ests
FY27 underlying EBITDA guidance of US$725m to US$780m, implies 12-21% growth at a 49% to 51% margin, with the US$752.5m midpoint about 1% above ests
Guidance range rests on adoption, with the low end assuming FY26-like growth and modest uptake of new initiatives, the high end assuming accelerated CVP, agentic AI and VerifyWise adoption
Company page: WiseTech Global (WTC)
Worley earnings fall on Middle East disruption but bookings and pipeline build
[9:34 am] Revenue held flat while the conflict and currency knocked earnings, with the FY27 outlook pointing to a return to growth weighted heavily to the second half.
Aggregated revenue flat at $12,023m vs $11,784m ests (2% beat)
Underlying EBITA down 10.8% to $734m, or down 6.1% excluding currency translation, with the Middle East conflict costing $58m
Underlying EBITA margin fell to 6.1% from 6.8% on the shift toward lower-margin construction and procurement, though the ex-procurement margin held at 9.0%
Underlying NPATA down 16.8% to $395m vs $380m ests (4% beat)
Statutory NPATA fell 35.6% to $306m after $120m of pre-tax restructuring and transformation costs
Final dividend of 25 cps unfranked takes the full year to 50 cps vs 48.8 cps ests (2% beat), unchanged on FY25
Bookings up 23% to $15.5bn, with sole-sourced wins at 44% and the factored sales pipeline up 24%, roughly half of which is expected to be awarded within twelve months
Backlog up 9% to $13.8bn, or 18% in constant currency, but well below the $16.7bn at the half after project completions and the removal of ExxonMobil's paused Baytown hydrogen project
Cost-out delivered $132m, ahead of the initial target, with restructuring concentrated in Western Europe following two chemicals project cancellations
FY27 guidance for mid to high single digit growth in both aggregated revenue and underlying EBITA, with revenue phasing broadly even but EBITA more heavily H2-weighted than usual
Middle East recovery is the key uncertainty, with Ashton flagging sulphur supply disruption to North African fertiliser projects and customers turning to Worley for damage assessments and reconstruction planning
Capital management continues, with the $500m buyback completed in May, $24m spent under a new $300m program, cash conversion at 93.6% and leverage of 1.8x
For context, Worley is down 9% year-to-date after two trading updates successively downgraded FY26 guidance due to Middle East disruption and global project delays. UBS is looking for FY27 revenue and EBITA growth of 15% and 19% respectively, so today's guidance commentary seems to be a sizeable letdown.
Company page: Worley (WOR)
Kelsian beats on revenue and EBITDA with FY27 guidance ahead of ests
[9:24 am] A record result at the top of the guidance range, with leverage back inside target and the FY27 outlook sitting above where UBS was positioned.
Revenue up 8.8% to $2,402.7m vs $2,381m ests (1% beat), with over 90% of revenue contracted or non-discretionary and indexation shielding fuel, labour and maintenance
Underlying EBITDA up 10.8% to $315.8m vs $304m ests (4% beat), landing at the top end of the guidance range with margin expanding to 13.1%
Underlying NPATA up 17.2% to $111.1m, excluding $14.5m of after-tax one-offs tied to the Tourism Portfolio divestment and new finance systems
Statutory NPAT up 16.6% to $63.5m vs $59m ests (8% beat)
Net operating cash flow of $220.1m at 91.4% conversion, cutting leverage to 2.46x from 2.74x at December and back inside the 2.0x to 2.5x target band
Final dividend of 10.0 cps fully franked takes the full year to 18.0 cps vs 17.0 cps ests (6% beat)
FY27 EBITDA guidance of $320m to $335m sits about 2% above the $322m est, and implies 1% to 6% growth including roughly $3.5m of Kangaroo Island ferry mobilisation costs carried over
Guidance assumes the Tourism Portfolio for the full year, with the divestment still subject to ACCC and FIRB approvals and management to update once completion timing is clear
Company page: Kelsian Group (KLS)
HMC Capital guides to 16% earnings growth in FY27, well ahead of ests
[9:15 am] FY26 landed in line with guidance, but the FY27 outlook and dividend step-up are materially above where the market was positioned.
Operating EPS pre-tax of 40.4 cents delivered in line with FY26 guidance, or 43.7 cents excluding discontinued operations
Recurring funds management revenue up 22% to $165.5m, with fee-generating AUM up 15% to $16.9bn across the platform
FY26 dividend of 12.0 cps, in line with ests
FY27 underlying earnings guidance of at least 35cps, implying 16% growth and sitting roughly 30% above the 26.8c ests
FY27 dividend guidance of 15cps, up 25% and around 25% above the 12.0c ests
Guidance rests on three drivers, being more than 30% growth in recurring funds management revenue, a circa 35% lift in distributions from DGT, HCW and HDN co-investments, and fixed cost leverage
100% cash conversion expected in FY27 as scrip payments and deferrals on management fees cease, a notable quality-of-earnings improvement
Private Credit AUM up 17% to $2.3bn, with $1.35bn of new institutional mandates and the TPG Credit partnership adding over $1bn of capital to deploy
Energy platform recapitalised, with a $603m institutional partnership generating a $35m upfront fee and cutting HMC's remaining investment to around $200m while retaining upside on a circa 5GW pipeline
Guidance excludes upside from capital recycling across HMC's $1.4bn balance sheet investments and any realised investment income on principal investments
Note: HMC reports operating and underlying EPS on a pre-tax basis, while analyst estimates are on a normalised post-tax basis. UBS (30-Jun) had FY27 pre-tax EPS forecast of 28.3 cps and pre-tax of 32.8 cps. The FY27 dividend is still a sizeable surprise vs. UBS ests of 12 cps.
Company page: HMC Capital (HMC)
Woolworths lifts EBIT 12.7% with every segment contributing and BIG W back in profit
[9:09 am] Australian Food momentum built through the second half while W Living swung $147m, though New Zealand went backwards and the Other drag widened.
Group sales up 3.6% to $71,539m vs $71,609m ests (in line)
EBITDA up 6.7% to $6,089m vs $6,206m ests (2% miss)
Group EBIT before significant items up 12.7% to $3,105m vs $3,052m ests (2% beat), with all trading segments delivering growth
NPAT (ex-items) up 15.4% to $1,599m vs $1,545m ests (3% beat)
Final dividend up 15.6% to 52 cps fully franked, taking the full year to 97 cps vs 94.8 cps ests (2% beat), up 15.5%
Australian Food sales up 4.6% with EBIT up 8.5%, though excluding cycled industrial action and supply chain costs the underlying figures were 4.1% and 4.8%, with margin up 20bps to 5.5%
New Zealand Food EBIT fell 7.7% in H2, with gross margin down on customer investment and higher stockloss tied to the new store operating model rollout
W Living swung to $116m EBIT from a $31m loss, with BIG W returning to a $64m profit and Petstock EBIT up 33.5%
First eight weeks of FY27 saw Australian Food sales up 7.6%, though roughly 1.5 to 2pts came from the Disney Ooshies program, while BIG W sales declined modestly
Consensus for 1H27 Australian Food sales growth is 4.9%
Wage pressure flagged for F27, with Bardwell pointing to the 4.75% Australian annual increase and progressive pay changes for 18 and 19 year old team members
Company page: Woolworths Group (WOW)
Lovisa lifts FY26 revenue by 17.6% on store rollout
[9:03 am] Americas and Europe carried the growth while comparable store sales stayed modest, and the payout ratio moved to 100% of earnings.
Revenue up 17.6% to $938.8m vs $950m ests (1% miss), with the Americas up 29.6% and Europe up 29.5% doing the heavy lifting
Comparable store sales up 2.0%, with 160 new stores opened to take the network to 1,136 at year end
Gross margin up 60bps to 82.6%, in line with the 82.7% implied by ests
EBIT up 14.1% to $158.2m vs $157m ests (1% beat), including start-up drag from Jewells, the seven store UK trial brand
NPAT up 10.7% to $95.6m
Final dividend up 22.2% to 33.0 cps 50% franked, taking full year dividends up 11.7% to 86.0 cps vs 82.0 cps ests (5% beat)
Operating cash flow up 21.0% to $294.5m, with new stores and refurbishments fully funded from existing cash flows
First eight weeks of FY27 saw total sales up 16.4% on a constant currency basis with comparable store sales up 3.0% and momentum improving through August
No FY27 guidance provided, with management pointing to a long new store runway across physical and digital formats
Company page: Lovisa (LOV)
Tabcorp lifts EBITDA 10% on cost discipline and retail model changes
[9:00 am] Flat revenue but a 140bps margin expansion drove double-digit earnings growth, with a National Tote agreement and the BetMakers bid landing after year end.
Revenue up 0.8% to $2,636.3m vs $2,646m ests (in line), with domestic wagering turnover up 0.9%, sport turnover up 8.3% and digital-in-venue turnover up 9.1%
EBITDA up 10.3% to $431.7m vs $422m ests (2% beat), with margin expanding 140bps to 16.4% on a 0.8% underlying cost reduction
Wagering and Media EBITDA up 9.9% to $361.8m
Integrity Services EBITDA rose 12.0% to $69.9m on 3.3% revenue growth
NPAT (ex-items) up 43.6% to $71.1m vs $71.9m ests (1% miss)
Full year dividend up 50% to 3.0 cps vs 2.8 cps ests (7% beat), including a 1.5c unfranked final
Net debt of $533m with leverage down to 1.2x, alongside extended tenor and more diverse funding
FY27 wagering turnover growth guided to be broadly consistent with FY26 excluding the FIFA World Cup, with opex growth capped at general inflation of 3.0% to 3.5%
FY27 capex of up to $160m and D&A of $225m to $235m, with EBITDA expected to benefit from Next-Gen terminal rollout and Phase 2 of the retail commercial model
BetMakers acquisition targeted to complete in the third quarter of FY27, subject to conditions, following industry agreement on a National Tote
Tax remains distorted by roughly $67m of non-deductible items tied to Victorian Licence amortisation and discount unwind
Company page: Tabcorp Holdings (TAH)
Helloworld beats on revenue and EBITDA but Middle East disruption caps profit
[8:57 am] Margin expansion and acquisitions drove top-line growth, though a hit to the June quarter left underlying profit marginally lower on the prior year.
TTV up 4.1% to $4.0bn, with the Middle East conflict weighing on June quarter volumes
Revenue up 8.1% to $208.5m vs $195.5m ests (7% beat), outpacing TTV growth as revenue margin lifted to 5.1% from 4.9%
Underlying EBITDA up 8.4% to $60.2m vs $57.8m ests (4% beat), landing at the upper end of the $57m to $62m guidance range
Underlying NPAT down 0.5% to $30.2m vs $30.5m ests (1% miss), with the gap to EBITDA growth pointing to higher depreciation, interest or tax
Final dividend of 5.0 cps fully franked takes the full year to 10.0c, in line with ests but down 29% year-on-year
CEO Andrew Burnes flagged the Middle East impact as the swing on the result, saying performance "would have been considerably stronger" in its absence
Early FY27 trading is encouraging, with July TTV flat on the prior year but July EBITDA up 8.8%, alongside strong forward bookings
Recovery playbook flagged, with management noting leisure demand historically rebounds within 60 to 90 days of market stabilisation
No FY27 guidance yet, with the company signalling it will be provided ahead of the October AGM
Company page: Helloworld Travel (HLO)
Count lifts dividend to a nine-year high on Wealth-led earnings growth
[8:55 am] Acquisitions and organic advice demand drove double-digit revenue growth, with margins expanding as operating leverage builds.
Revenue up 15.6% to $165.9m, driven by acquisitions and organic growth in the Wealth segment, with financial planning revenue in Equity Partnerships up 15.2%
FUM up 66.1% to $6.5bn, boosted by insourcing of the Count Portfolios, the Oracle Investment Solutions acquisition, managed account expansion and market conditions
FUA up 13.7% to $43.0bn on new client growth and net inflows
Underlying EBITA up 20.5% to $33.4m, with margins expanding roughly 80bps to 20.1%
Underlying NPAT up 27.2% to $13.9m, with statutory NPAT up 70.8% to $15.2m on the one-off items above
Final dividend up 9.1% to 3.00 cps fully franked, the highest final payout in nine years
10 transactions completed including four financial planning acquisitions, taking the Equity Partnerships adviser count to 93
Management points to regulatory tailwinds, with CEO Hugh Humphrey citing superannuation, product complexity and proposed changes in the 2026-27 Federal Budget as driving elevated demand for advice
Company page: Count (CUP)
Chalice gets independent tick on Gonneville approvals pathway
[8:54 am] An external review by a former WA EPA chair backs the environmental approvals strategy underpinning a targeted FID in the first half of CY28.
Review found key environmental risks appropriately identified, with mitigation measures either already in place or planned, and concluded the H1 CY28 FID target is achievable
Reviewer is Dr Tom Hatton, WA EPA chair from 2015 to 2020 and a 25-year CSIRO veteran, who holds no financial interest in Chalice or the project
Ministerial approval remains on the critical path, the key gating item between here and FID rather than technical or financing workstreams
Environment Review Documents due Q4 2026, with environmental modelling recently completed ahead of submission
Project holds priority status with both the WA and Commonwealth governments, alongside extensive engagement with regulators and Traditional Owners
Company page: Chalice Mining (CHN)
Deep Yellow locks in Tumas water supply and local ownership ahead of Q4 FID
[8:53 am] Two long-standing conditions on the Namibian uranium project have been cleared, tightening the path to a final investment decision.
Long-term water supply agreement signed with NamWater, covering dedicated capacity over the life of the project across construction, commissioning and production, with financial terms commercial-in-confidence
Oponona to take a 5% stake in Reptile Uranium Namibia, the holder of mining licence ML237, satisfying the local ownership requirement attached to the licence
No cash call from the local partner, with Oponona's 5% share of historical and future Tumas spend treated as an interest-free loan repayable only from its future dividends
Community entity to receive 40% of Oponona's future dividends through a dedicated special purpose entity
Construction is progressing, with bulk earthworks complete and roughly $34m of civil and concrete works awarded to two Namibian contractors, opening multiple work fronts to reduce schedule risk
FID still targeted for Q4 2026, subject to market conditions, with engineering, procurement, optimisation and financing workstreams continuing in parallel
Company page: Deep Yellow (DYL)
Vysarn beats across the board as full year subsidiary contribution drives 41% profit growth
[8:51 am] A clean beat on revenue, earnings and profit, though cash conversion went backwards and FY27 is focused on two pending acquisitions.
Revenue up 31% to $140.1m vs $133.7m ests (5% beat), reflecting a full twelve month contribution from all wholly owned subsidiaries after the CMP and WWS acquisitions
EBITDA up 36% to $28.9m vs $27.8m ests (4% beat), with the industrial segment delivering a record year on tight water well drilling supply in WA iron ore
NPAT up 41% to $15.1m vs $14.4m ests (5% beat), with net tangible assets of $66.0m
Operational cash flow down 13% to $14.9m, converting at just 52% of EBITDA against 81% in FY25
Industrial second half stepped down deliberately, with two rigs pulled from the field for client-spec rebuilds ahead of a new five year Tier 1 iron ore contract expected to support multiple rigs and double shifting
Technology earnings were flat and heavily 2H skewed after wastewater plant awards slipped, pushing completion earnings on those plants into FY27
Two acquisitions pending, with NewGround and Welltech to add water infrastructure, irrigation, facilities management and sewerage services, funded in part by a $65.3m placement at $1.05 per share
No dividend declared, consistent with ests, with management flagging material FY27 investment in senior management ahead of the step-up in scale
Company page: Vysarn (VYS)
Flight Centre lands record TTV but Middle East hit costs leisure $60m in Q4
[8:48 am] A solid nine months unravelled in the June quarter as Middle East hostilities disrupted travel patterns, leaving underlying profit slightly lower despite corporate's full year uplift.
TTV up 4.7% to a record $25.7bn, slowing from 6.9% growth over the nine months to March as Q4 disruption bit
Revenue up 2.5% to $2.9bn vs $2.89bn ests (in line), with revenue growth well behind TTV growth
Underlying EBITDA up 3.9% to $466m vs $472m ests (1% miss), with the underlying cost margin improving to 9.6%, just shy of the record 9.5% set in FY23
Underlying PBT down 4% to $278m vs $284m ests (2% miss), landing in the lower half of the $275m to $295m guidance range after tracking near or above the top through Q3
Circa $60m leisure profit hit in Q4, with higher software amortisation, new leisure lease costs and net interest adding a further $30m drag on underlying PBT
EPS up 42.9% to 70.9c, outpacing NPAT growth as on-market buy-backs shrank the share count
Final dividend of 30 cps takes the full year to 42 cps vs 40c ests (5% beat), up 5%, representing 47% of underlying NPAT
Early FY27 trading is mixed, with record July leisure TTV and the strongest July profit since 2015, offset by corporate 1H27 profit expected below the prior year, and FY27 guidance held back until the November AGM
Company page: Flight Centre Travel Group (FLT)
Perseus beats on cash flow and dividend, lifts payout policy and buyback
[8:48 am] Record gold prices drove a beat across the top line and cash generation, with the surprise coming in shareholder returns rather than earnings.
Revenue up 19% to US$1.48bn vs US$1.44bn ests (3% beat), with higher realised gold prices offsetting lower production at Yaouré and Edikan on planned ore source transitions
EBITDA up 16% to US$860.5m vs US$790m ests (9% beat), though cost of sales rose on higher royalty rates in Côte d'Ivoire and Ghana plus more waste and lower grades from the new pits
NPAT up 14% to US$480.5m vs US$482m ests (in line), absorbing a US$235.4m tax expense against US$142.7m a year earlier after the Yaouré tax holiday ended on 31 December 2025
Operating cash flow up 24% to US$666.4m vs US$548m ests (22% beat), lifting cash and bullion to US$1.03bn alongside a US$400m undrawn facility
Full year dividend of 14.0 cents vs 11.7 cents ests (20% beat), up 87% on the prior year including a 9.0 cent final, for a 2.7% yield
Dividend policy rebased to a minimum 20% of operating cash flow after non-controlling interest payments, replacing the prior 1% yield floor
New buyback of up to $350m from around 24 September after $126m completed in FY26, plus a proposed $100m distribution from Meyas Sand sale proceeds
FY27 guidance unchanged at 420koz to 480koz production, broadly in line with the 447koz est, while AISC of US$1,835 to US$2,070 per ounce sits around 5% below the US$2,046 est
Resource base expanded, with Measured and Indicated up 37% and Proved and Probable up 40% on FY25, and Nyanzaga on track for first gold in January 2027
Company page: Perseus Mining (PRU)
Canada retaliates dollar for dollar as US trade war deepens
[8:43 am] Ottawa has matched Trump's 50% tariffs with duties of its own, and the escalation ladder still has plenty of rungs left.
Canada will tariff more than 700 US goods worth about $20bn from 8 September, with rates of 15% to 50% matching Trump's latest duties dollar for dollar
Steel and aluminium tariffs double to 50%, with the rest concentrated in paper, construction materials, home appliances, dairy and seafood, sectors chosen because Canada has domestic alternatives
Targeting is politically calculated, with Industry Minister Mélanie Joly saying the levies were picked to hit specific US states ahead of the midterms
The scale is still modest, covering roughly 6% of US goods exports to Canada, while the latest US tariffs cover about 5% of US imports from Canada
The bigger threats sit ahead, with Trump flagging 50% tariffs on Canadian cars, trucks, auto parts and steel from 1 January 2027, and Ottawa holding energy, potash and electricity exports in reserve
ECB primed for September hike but stops short of flagging more
[8:41 am] Sources say the ECB is ready to lift rates again to contain the inflation spillover from the Iran war, without committing to a longer tightening cycle.
Policy rate set to rise to 2.50% from 2.25% at the 9-10 September meeting, following June's first hike in nearly three years
Inflation running at close to 3%, driven by rising natural gas prices and elevated petrol prices, both acute for the energy-importing euro zone
Governors see no need to signal further tightening beyond September, with long-term inflation expectations still anchored at the 2% target, while markets price one or two more hikes
Euro zone activity is holding up better than expected on output data and business surveys, suggesting the tightening so far is not straining growth
August inflation data lands next week, ahead of updated ECB staff projections at the September meeting, and the June hike was already embedded in those forecasts
Apple refreshes Mac mini and Mac Studio with M6 and M5 Ultra chips
[8:40 am] New desktops land into pent-up demand after a memory chip shortage forced Apple to lift prices and left machines out of stock for months.
Mac mini now starts at US$899 on the new M6 chip, up from the original US$599 base that was scrapped in May and an interim $799 following the AI-driven memory squeeze
Mac Studio spans US$2,499 to US$5,499 on M5 Max and M5 Ultra, with a fully configured M5 Ultra build reaching US$18,299, lifting the mix toward higher-margin professional configurations
Both machines are out of stock at Apple and most authorised retailers, often for weeks or months, so the refresh should convert quickly into orders rather than sitting on shelves
Pre-orders open now with retail from 22 September, shipping on macOS 27 Golden Gate, ahead of an iPhone event on or around 9 September that includes Apple's first foldable
Leadership transition lands in September, with Cook handing over to John Ternus, followed by an updated HomePod mini and a smart home display built around the revamped Siri
Source: Bloomberg
US widens sanctions threat on Iran as Hormuz shipping risk lingers
[8:37 am] Washington is escalating economic pressure on Tehran while stopping short of pulling the trigger, leaving oil and shipping markets in a holding pattern.
Bessent threatened secondary sanctions on countries refusing to cut economic ties with Iran but imposed no major new penalties, calling it a "warning shot" and giving everyone "the opportunity to remedy bad behaviour"
A major sanctions announcement targeting an unspecified financial institution is flagged for the end of this week, alongside threats to expel Iranian money laundering facilitators from the US dollar system
China, India, Turkey, Iraq and the UAE are seen as most exposed, though Bessent declined to say whether Chinese banks would be targeted, and the UAE has already suspended all trade and financial transactions with Iran
Beijing pushed back, with the Foreign Ministry saying its cooperation with Iran sits within international law and that "economic warfare and maximum pressure provide no solution"
Trump says all mines have been removed or detonated in the Strait of Hormuz under a "zero tolerance" policy, but a tanker was struck and disabled off Oman and a Saudi Bahri tanker was hit in a Red Sea incident
Iran's rial has fallen to a record low beyond 2 million per US dollar, with Tehran saying it is "fully prepared" and will not respond purely defensively
Oil down, yields down
[8:35 am] Brent dipped 4.8% to US$85.95 a barrel overnight, driving a sharp pullback for bond yields.
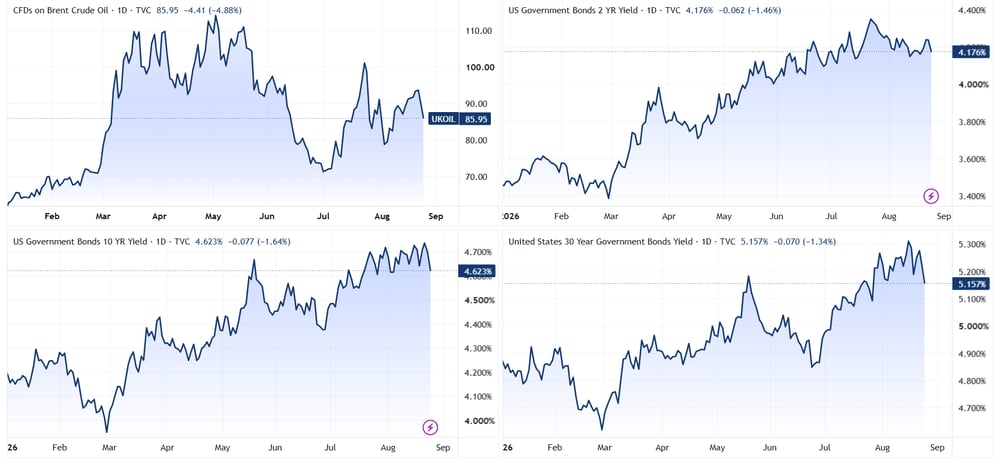
Brent (top left), US 2-year yield (top right), US 10-year yield (bottom left), US 30-year yield (bottom right) | Source: TradingView
Good morning!
[8:24 am] ASX 200 futures are up 29 pts (+0.31%). Here's what happened overnight:
Chip stocks carried the US market higher, ahead of Nvidia's result tomorrow
S&P 500 (+0.32%), Dow (+0.30%), Nasdaq (+0.66%), Russell 2000 (+0.50%), Equal-weight S&P 500 (-0.07%)
Philadelphia Semiconductor Index up 1.4% but still down 8.1% in the last six sessions
Brent dipped 4.8% to US$85.95 a barrel, driving a meaningful pullback for bond yields
Canada matched Washington dollar for dollar, announcing retaliatory tariffs on C$27.6bn of US goods from 8 September as the trade fight escalated