ASX 200 Live Today - Tuesday, 18th August
The ASX 200 is set to fall for a fifth straight session as global long-dated bond yields break out. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Tuesday, August 18. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Reporting season is heating up and we've got you covered. Our reporting season calendar has over 250 stocks plus earnings and dividend estimates.
ASX 200 breakeven as CSL and BHP offset broader weakness
[2:30 pm] The ASX 200 is trading around breakeven, which is around the midpoint of today's trading range (+0.37% vs. -0.21%). A very results-driven day, with gains from BHP (+2.8%) and CSL (+15.4%) offsetting weakness across most major banks, staples, telcos and retail stocks.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
BHP | BHP | 2.8% | $63.92 | -0.1% | 40.4% |
CBA | Commonwealth Bank | -1.2% | $163.06 | -6.1% | 1.5% |
RIO | Rio Tinto | -0.9% | $166.84 | -7.3% | 13.6% |
NAB | National Australia Bank | -0.7% | $39.18 | -5.0% | -7.3% |
WBC | Westpac | -1.3% | $34.62 | -3.1% | -10.1% |
ANZ | ANZ Group | -0.7% | $37.63 | 1.4% | 3.2% |
WES | Wesfarmers | -0.7% | $84.27 | -6.2% | 4.0% |
MQG | Macquarie Group | -1.9% | $255.69 | -2.8% | 26.0% |
CSL | CSL | 15.4% | $155.39 | 15.2% | -10.4% |
WDS | Woodside | 1.0% | $33.17 | 1.9% | 39.8% |
GMG | Goodman Group | 4.1% | $30.80 | 2.4% | -0.7% |
BHP (+2.8%) delivered a pleasing FY26 result, where the main surprises were:
Net debt of US$8.7bn, below the US$10-20bn target range
Fully franked final dividend of US 99 cps at a 72% payout, the largest in four years
FY26 total dividend of US 172 cps vs. Morgans and Macquarie ests of 157.7 and 160 cps respectively (9% and 7.5% beat)
FY26 dividend payout ratio of 66% vs. 63% ests
The result is clearly the driver of outperformance, as peers like Rio Tinto (-0.9%) and Fortescue (-0.1%) are trading lower, while most copper names are down 1-2%.
Healthcare is at an interesting juncture. The index was already up 28.3% since 3 June heading into today's results from CSL and Cochlear, so the stocks were arguably overextended going in. CSL still delivered beats across all key metrics, with strong immunoglobulin momentum in 2H26 (growth of 14%) and FY27 guidance ahead of consensus. Cochlear's FY26 underlying NPAT came in at the top of its own $290-330m guidance, while FY27 guidance of $330-350m underlying NPAT was in line. So neither delivered a 'wow' result, but both offered some much-needed stabilisation coming off peak YTD declines of 45% for CSL and 65% for Cochlear. It's one of those tricky situations where the chart looks bullish and momentum is strong, but fundamentally, both stocks are still far from their classic growth rates.
Outside of results, bond yields are the talk of the town. Overnight, the US 10-year broke out to 4.73%, its highest since January 2025, while the 30-year is now 5.31%, the highest since June 2007. Canadian 30-year yields are also at their highest since 2010, and German long-dated yields are at 2011 highs. The Aussie 10-year remains rangebound but pushed above 5.0% in the past day. It's an uneasy environment for equities when yields start moving out to uncomfortable levels, implying higher for longer rates and sticky inflation.
Cochlear FY26 earnings call highlights: Weaker developed-market demand
[2:15 pm] Management held a call at short notice to explain lower sales and profit, fielding questions on the developed-market slowdown, Middle East risk and a cost-base reshaping.
On the core theme behind the downgrade, CEO Dig Howitt: "Hearing loss isn't being seen as a high priority intervention when either people become under pressure financially or when hospital systems come under pressure, they are deprioritising hearing loss"
On the adults and seniors slowdown: "If we look back before COVID, we saw adults and seniors growing at 10%-11% per year ... the adults and seniors growth rate has gone from probably lower than 5% this year, which will be the lowest," now more correlated with US consumer sentiment "lower than it's been at any time over that period"
On European hospital systems: "Cochlear implant surgeries are getting deprioritised relative to other surgeries," with waiting lists, cancellations and strikes across the UK, Germany, Italy and Spain
On the Middle East: "With the war in the Middle East, we are seeing some order cancellations ... there are some questions over the collection of some of our receivables," with a potential provision sitting inside the guidance range
On reduced manufacturing output: production cut by more than the fall in sales given inventory levels, sending unrecovered overhead "straight through the P&L" this year
On the cost reshaping: "We're not spending more. We are reallocating the costs that we've got," with $25-35m of restructuring to hit 1H26, pulling forward FY27 and FY28 expenses
Company page: Cochlear (COH)
HUB24 FY26 earnings call highlights: IDPS outflow drag but super and budget settings as tailwinds
[2:14 pm] Management fielded questions on the second-half flow slowdown, FY27 margins and the trustee in-sourcing on the FY26 results call.
On the net flow slowdown, CEO Andrew Alcock: "There is an uptick in outflows in discretionary funds under administration, i.e., our IDPS book ... It logically suggests that the budget settings are driving people thinking differently about how they invest in the future. I expect that's just a time basis"
On where the outflows are heading: "There is some uncertainty out there about the future of different structures for different types of people who have those sorts of investment products, and typically high-net-wealth people ... it is people getting reset at this point in time"
On superannuation as an offset: "Superannuation will become more attractive, and we're yet to see that come through ... I would expect that over time, more people will top up their super more than before, and that's a very large part of our business"
On FY27 margins, CFO Kitrina Shanahan guided to "flat to slightly growing underlying EBITDA margins" at both group and platform level, with total expense growth in the "low to mid-teens" range
On custody revenue margin: "I'd still expect there to be anywhere around the half a bps to a bps of margin compression" as balances grow into higher fee tiers and caps
On gross flow dynamics behind the flat net number: "Our gross flows are at industry record levels currently ... to hit those net flow numbers, you need to increase your gross flows by $4 billion or $5 billion a year to hit the same numbers"
Company page: HUB24 (HUB)
Sims FY26 earnings call highlights: Near-term SLS softness but frames GPU repurposing as the next big opportunity
[2:12 pm] Management fielded questions on the data centre refresh slowdown, the sustainability of non-ferrous margins and the emerging GPU repurposing opportunity on the FY26 results call.
On the first-half FY27 SLS softness, CEO Stephen Mikkelsen: "The DDR4s that we are selling in the first half, the ones that have come out, they are of lower speed, which is kind of intuitively correct. Because if your refresh cycle is being delayed because of various blockages, you are going to be pulling out the less valuable stuff first"
On whether the slowdown is structural: "There are no DDR4s in the world that need to be taken out of data centers. In fact, that installation happened two or three years ago. So it is not less DDR4s, it is simply the timing of when are they going to come out"
On the GPU opportunity: "I see GPUs opportunity as larger than the DDR4 opportunity and the DDR5 opportunity" citing complexity that is "an order of magnitude higher than what we do today," extremely large volumes and very high unit value
On GPU economics: "The rev share on a GPU will absolutely be lower in percentage terms than the rev share on a DDR4 ... clearly, we're not going to get a 25%-30% rev share on those because the value of them is just extraordinarily higher. But the opportunity for absolute margin is very strong"
On the non-ferrous earnings base driving the metal result: "We do not see anything driving down the value of non-ferrous," with Mikkelsen noting Zorba "comes at a very low marginal cost" and tends to fall "straight to the bottom line"
On whether ANZ has troughed: "It is hard to see the ferrous market getting much worse from the impact that China's having on it ... I feel that this is the bottom earnings for ANZ"
Revolut eyes Australian mortgage market to challenge Big Four
[2:10 pm] The European fintech is weighing a move into Australia's contested home lending market after securing its first Asia Pacific banking licence last month.
CEO Matt Baxby flagged mortgages as a "natural progression" into relationship-based products, targeting a market where the Big Four control at least 70% of banking
Revolut enters with 1.2 million existing Australian customers already using it for payments and foreign exchange, having launched savings accounts and credit cards after gaining its licence
Australian revenue up 74% to A$70.8m in 2025, with net profit of A$7.4m and net interest income up 110% to A$17.1m
Runs a subscription model with four plans from A$5.99 to A$99.99 a month, uncommon in Australia, offering tiered savings rates and reduced fees
UBS analyst John Storey called it a more credible threat than prior challengers given its deposit-led, technology-heavy model, though near-term earnings risk to Australian banks remains limited
Source: Reuters
Copper supply squeeze intensifies as key LME spread flares out
[2:08 pm] Short-term supply tightness on the London Metal Exchange spiked as traders continue diverting metal to the US ahead of a possible tariff decision.
So-called tom/next spread blew out to a US$75/t premium for one-day contracts, the widest since US$100 in January when LME prices hit a record
Squeeze driven by hundreds of thousands of tons shifting to the US ahead of any Trump administration import tariff decision, leaving warehouses elsewhere running low
Spot prices Monday traded as much as US$545/t above three-month futures, with stress building for short holders before Wednesday's August contract expiry
Copper up more than 13% this year on data centre and renewable energy demand, lifting earnings at Rio Tinto and BHP, where the metal topped half of group revenue for the first time
Some signs of easing, with LME warehouses recording their first net copper inventory build since 17 June, helped by additions in Malaysia
Source: Bloomberg
Consumer sentiment lifts but stays weak as RBA pause offers relief
[2:07 pm] The Westpac–Melbourne Institute Consumer Sentiment Index rose in August as the RBA's decision to hold provided some clarity, though pessimists still outnumber optimists.
Headline index up 6% to 88.9 in August from 83.9 in July, still a weak read and well below last year's levels
Gain concentrated among mortgage holders and in responses received after the 11 August RBA decision, with pre-meeting responses little changed on July
'Family finances vs a year ago' sub-index up 12.6% to 80.0, the largest monthly gain of any component, as cost of living pressures eased further
'Time to buy a dwelling' index up 12.1% to 95.7, the highest since November 2025, with Sydney and Melbourne both edging back above 100
Unemployment Expectations Index rose 4.4% to 135.7, partly unwinding last month's more comforting labour market view (higher reads mean more consumers expect unemployment to rise)
House Price Expectations Index fell to a fresh three-year low of 110.8, with outright owners most likely (43.5%) to expect prices to fall
Review of today's results movers
[12:57 pm] A bit of a food for thought post (more to come).
BHP (+2.6%): A clean FY26 result, with net debt falling below its US$10-20bn target range. The big surprise here was the dividend, broadly ahead of analyst expectations, at a higher payout ratio (FY26: 66% vs. 63% ests).
Revenue up 15% to US$58.8bn vs US$57.96bn ests (1% beat)
Underlying EBITDA up 27% to US$32.9bn vs US$32.2bn ests (2% beat), with copper contributing 54% at a 70% margin
Underlying attributable profit up 30% to US$13.2bn
Net debt of US$8.7bn, below the US$10-20bn target range
Fully franked final dividend of US 99 cps at a 72% payout, the largest in four years
FY26 total dividend of US 172 cps vs. Morgans and Macquarie ests of 157.7 and 160 cps respectively (9% and 7.5% beat)
The most intriguing slide is BHP's ambitions to grow copper production by ~50% to 2.5Mt by the mid 2030s. Though its FY27 copper production guidance points to a 12% decline from 1,953kt to 1,650-1,800 kt.
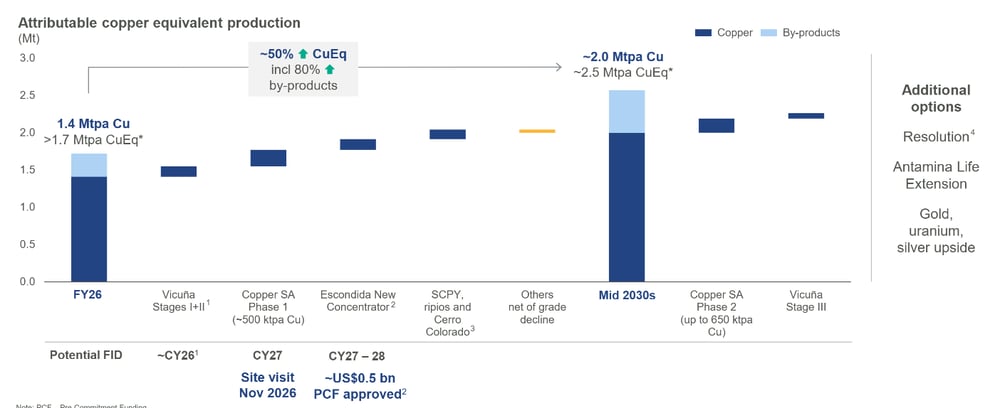
Source: BHP FY26 results presentation
CSL (+16.2%): If CSL closes around these levels, it will mark its biggest one-day gain in more than two decades, ahead of the 12.5% rally on 19 January 2017. The FY26 result was more about stabilisation, after five straight reporting seasons where the shares fell on the result.
Total revenue down 1% to US$15.8bn vs US$15,423m ests (2% beat)
Underlying NPATA down 2% to US$3.1bn vs. Macquarie ests of $3.05bn (1.6% beat)
Reported net loss after tax of US$2.6bn, after US$7.1bn of pre-tax impairments and US$799m of restructuring costs
Transformation program delivered ~US$176m of cost savings, ahead of target
FY26 total dividend flat at US$2.92 per share
Ahead of Macquarie ests of US$2.88, below Morgans ests of US$2.97
FY27 revenue guided in-line with FY26
FY27 underlying NPAT growth of approximately 5% vs. consensus of 2% growth
"We think the market will particularly like the Ig performance with FY26 revenue growth of 4% year-on-year and 2H26 growth of 14% year-on-year," RBC Capital analysts wrote in a note this morning.
"The stock has had a strong run into this result, however we expect the FY27 guidance beat to consensus and strong Ig performance in 2H26 to drive outperformance in the stock today."
Top ASX 200 gainers and losers
[11:40 am] Reliance Worldwide rallies on a takeover offer, CSL and Cochlear both top FY26 earnings expectations, while Sims and Hub24 results read well at face value, both fell shy of certain in-line items (Hub24 Q4 inflows was softer-than-expected).
Ticker | Company | % Chg | Price |
|---|---|---|---|
RWC | Reliance Worldwide | 23.68% | $4.47 |
CSL | CSL | 17.12% | $157.64 |
PME | Pro Medicus | 12.44% | $197.74 |
SRG | SRG Global | 10.36% | $4.00 |
JDO | Judo Capital | 9.84% | $1.01 |
CGF | Challenger | 7.07% | $10.38 |
COH | Cochlear | 6.71% | $140.06 |
A2M | A2 Milk Company | 5.59% | $6.90 |
GMG | Goodman Group | 5.19% | $31.11 |
DRR | Deterra Royalties | 4.38% | $4.41 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
SGM | Sims | -12.74% | $22.53 |
HUB | Hub24 | -8.96% | $78.47 |
BEN | Bendigo & Adelaide | -8.48% | $10.21 |
360 | Life360 | -4.98% | $23.27 |
IRE | Iress | -4.43% | $6.68 |
NWL | Netwealth Group | -4.00% | $23.06 |
ZIP | Zip Co | -3.89% | $2.60 |
ELV | Elevra Lithium | -3.60% | $8.84 |
VUL | Vulcan Energy Resources | -3.56% | $2.85 |
IPX | Iperionx | -3.53% | $3.42 |
Results wrap: BHP and CSL lead the movers on results day
[10:18 am] A heavy day of FY26 results delivered plenty for investors, with dividend surprises, guidance beats and one standout rebound story.
BHP Group (+3.9%): Strong result with underlying EBITDA up 27% to US$32.9bn (2% beat) and record iron ore output, but the standout was a total FY26 dividend of US 172 cps, well ahead of a consensus payout ratio of 63% at a 72% payout
CSL (+15.4%): Market cheered a result with most numbers tracking broadly in-line or slightly ahead, with FY27 guidance for ~5% underlying NPAT growth topping consensus of ~2%, and it feels like the first positive result the market has seen in years
HUB24 (-5.9%): Slightly bothered by the lack of platform net inflow upside for FY26, though FY28 Platform FUA guidance of $186-200bn is strong and the stock has clawed off session lows of -13.5%
Reliance Worldwide (+24.3%): Surged on Brookfield's improved $4.75 per share indicative proposal, a 31.6% premium to the last close, even as adjusted NPAT fell 15.3% and the final dividend was pulled
SRG Global (+7.1%): Record result beating upgraded guidance, with revenue up 27% (2% beat) and upgraded FY27 EBITDA guidance of $195-205m (2% above ests)
Sims (-13.8%): Sold off despite a record result and 10% earnings beat, with sales revenue of $8,007.5m missing by 2% and the market wary after the June guidance upgrade had already been well flagged
Also moving: Pro Medicus (+4.0%), Cochlear (+2.8%) on a volatile open, and SKS Technologies (-3.0%)
Pro Medicus lifts underlying NPAT 24%, signs $407m of new contracts
[9:51 am] Pro Medicus delivered a strong FY26 with double-digit revenue and earnings growth, a record run of contract wins and renewals, and a higher dividend.
Revenue up 22.9% to $261.7m vs $261.6m ests (in line)
Underlying EBIT up 24.4% to $196.1m vs $191.0m ests (3% beat)
EBIT margin up 90 bps to 74.9%
Underlying NPAT up 24.1% to $144.7m, with reported NPAT up 130.3% to $265.3m
On a constant currency basis, underlying NPAT up 32.5% to $154.5m, exceeding the company's 30% EBIT and NPAT growth targets
Total FY26 dividend up 25.5% to 69c fully franked, with a final dividend of 37c,
Remains debt-free with cash and financial assets up 19.7% to $252.3m
Signed 10 new contracts worth a minimum $407m and renewed 6 of 6 contracts worth $141m on 5-year terms, all with higher minimums and increased fees per transaction
Trinity implementation largely complete and ready for full-year contribution in FY27, with US market share around 11%
Company page: Pro Medicus (PME)
BHP flags resilient commodity demand despite geopolitical headwinds
[9:48 am] BHP's FY26 economic outlook points to resilient global growth and commodity demand, supported by AI-driven investment and electrification, though Middle East conflict is lifting costs.
Global economic growth expected to moderate to around 3% in CY26 from 3.5% in CY25, before improving in CY27, supported by fiscal policy, digital infrastructure, electrification and AI investment
China growth expected to stay broadly within the official 4.5-5% target range, aided by a reacceleration of fiscal support in H2 CY26, with strong exports offsetting soft domestic demand and a property sector drag
India expected to remain the fastest-growing major economy, underpinned by infrastructure investment and industrialisation, though momentum is moderating on higher energy costs
Copper prices rose to new record highs and steel raw material prices recorded positive year-on-year growth, with AI-related investment and electrification adding to demand
Cost environment shifted materially on the Middle East conflict, with higher energy prices lifting inflation and disruption through the Strait of Hormuz pressuring sulphuric acid, diesel and ammonia markets, affecting projects such as Jansen
BHP positions itself as well placed to navigate the disruption given its structurally advantaged cost positions and disciplined cost management
Company page: BHP Group (BHP)
Equity Trustees receives $24.55 per share takeover proposal from TPG Global
[9:48 am] Equity Trustees has received an unsolicited, non-binding indicative proposal from TPG Global to acquire the company by way of a scheme of arrangement.
Indicative cash offer of $24.55 per share, less any dividends declared or paid, representing a 42% premium to the last close of $17.31
Proposal made by TPG Global on 17 August 2026 to acquire 100% of EQT shares
Subject to conditions including due diligence, TPG Investment Review Committee approval, a Scheme Implementation Deed, a unanimous Board recommendation and regulatory approvals from FIRB, ACCC and APRA
Board recommends shareholders take no action, with no certainty the proposal will lead to a binding offer
Company page: Equity Trustees (EQT)
CSL delivers "year of reset", flags return to growth after $7.1bn impairments
[9:42 am] CSL posted a modest FY26 result and a statutory loss driven by large impairments, while announcing a fresh buy-back and guiding to a return to growth in FY27.
Total revenue down 1% to US$15.8bn vs US$15,423m ests (2% beat)
Behring revenue down 1% to $11.4bn, with Ig sales flat at $6.2bn on US channel normalisation
Vifor up 3% to $2.4bn
Seqirus down 8% to $2.0bn on non-recurring avian flu revenue
Underlying NPATA down 2% to US$3.1bn
Reported net loss after tax of US$2.6bn, after pre-tax impairments of $7.1bn and $799m of restructuring costs
Transformation program delivered ~$176m of cost savings, ahead of target
Final dividend of US$1.62, with total FY26 dividend of US$2.92 unchanged year-on-year
Ahead of Macquarie ests of $2.88 but below Morgans ests of $2.97
FY27 guidance for revenue in line with FY26 and underlying NPAT growth of approximately 5%, ahead of consensus of ~2% EPS growth and Macquarie ests of flat growth
CSL has rallied fairly hard into the result, up 49.5% from the 3 June low but still down 21.4% year-to-date. Short interest remains negligible at 1.19%, though elevated vs. the last three years (averages around ~0.5%).
Company page: CSL (CSL)
HUB24 delivers record FY26 with EBITDA up 30%, FUA hits $164bn
[9:35 am] HUB24 posted a record result driven by strong platform net inflows and continued market share gains, with margins expanding across the group.
Total revenue up 23% to $501.1m vs $500.5m ests (in line)
Group Underlying EBITDA up 30% to $211.4m vs $206.9m ests (2% beat)
Underlying NPAT up 40% to $137.3m vs $133.2m ests (3% beat)
Total FUA up 20% to $164.3bn, with Platform FUA up 24% to $139.5bn, in line with Macquarie ests of $139.5bn
Record platform net inflows of $18.9bn, in line with Macquarie ests of $18.9bn
Platform market share lifted to 9.9% at 31 March 2026 from 8.6%, with active advisers up 11% to 5,649
Total FY26 dividend up 39% to 78.0 cps fully franked vs 78.4 cps ests (in line)
FY28 Platform FUA target of $186-200bn (midpoint $193bn) versus Macquarie ests of $190.5bn, excluding PARS
Company page: HUB24 (HUB)
Amplitude Energy posts third straight year of record results
[9:31 am] Amplitude Energy delivered record FY26 production, revenue and cash flow, driven by strong Orbost output as it advances its East Coast Supply Project.
Sales revenue up 7% to $285.8m, on higher volumes and a 5% lift in average realised gas price to $10.36/GJ
Underlying EBITDAX up 12% to $191.8m, at a 67% margin
Adjusted cash from operations up 19% to $191.0m, with operating cash flow up 102% to $180.3m
Underlying profit after tax up 394% to $45.0m
Reported loss after tax of $27.2m, largely reflecting write-off of Elanora and Isabella exploration costs
Record production up 3.5% to 27.6 PJe (75.5 TJe/d), towards the upper end of 26.6-28.1 PJe guidance
Net debt cut to $37.6m from higher cash of $137.5m and reduced drawn debt of $175.2m
FY27 production guided to 26.6-28.5 PJe, with capex of $250-310m
CEO Jane Norman: "Amplitude Energy has delivered record financial results for the third consecutive year, underpinned by solid operational performance and continued cash flow improvement"
Company page: Amplitude Energy (AEL)
Sims delivers record FY26 as US metal and Lifecycle Services surge
[9:25 am] Sims posted a sharp FY26 earnings jump, powered by strong North American metal trading and an outsized contribution from its data centre-linked Lifecycle Services arm.
Sales revenue up 6.9% to $8,007.5m vs $8,178.8m ests (2% miss)
Underlying EBIT up 167.6% to $468.0m vs $426.9m ests (10% beat)
Sims provided a trading update in June, guiding to FY26 underlying EBIT of $420-435m, an upgrade from the prior $350-400m. So today's result has already topped the upgraded guidance
Underlying NPAT up 247.9% to $289.1m vs $262.3m ests (10% beat)
Total dividend up 47.8%, with a 20.0 cent fully franked final
Return on invested capital of 11.7%, up from 4.5% in the pcp
SLS Underlying EBIT surged to $172.7m from $32.6m, with processed repurposed units up 90.9% to 16.8m on hyperscaler demand
SA Recycling contributed $235.5m to underlying EBIT, up 96.3%, while NAM rose 69.7% to $135.9m
ANZ EBIT down 22.7% to $55.8m as elevated Chinese steel exports pressured ferrous margins
SLS first-half underlying EBIT guided to $75-90m, with non-ferrous conditions expected to stay supportive into FY27
CEO Stephen Mikkelsen on SLS: "It has evolved from a traditional asset recovery business ... into a strategic partner in the supply chain supporting Data Centre Infrastructure Services"
Company page: Sims (SGM)
Third consecutive year of quantum earnings growth for SKS Technologies
[9:23 am] SKS Technologies delivered another record FY26 with double-digit gains across every metric, driven by a surge in data centre work.
Revenue up 33% to $347.93m vs $343.1m ests (1% beat)
EBITDA up 80.8% to $42.43m vs $37.9m ests (12% beat)
After-tax profit up 93.2% to $27.11m vs $24.3m ests (12% beat)
EPS of 23.45 cents vs 21.0 cents ests (12% beat)
Total dividend up 66.7% to 10 cents, with a 6.5 cent final
Data centre revenue up 47.6% to $207.70m, with traditional revenue up 16.0% to $140.30m
Work on hand up 56% to $312m, pipeline settling at $1.69bn with around 87% tied to data centre tenders
FY27 guidance for revenue around $500m vs $485m ests (3% beat) and PBT of $60m
Company page: SKS Technologies Group (SKS)
BHP posts record copper and iron ore, lifts dividend to four-year high
[9:15 am] BHP delivered a strong FY26 driven by record iron ore output and copper becoming the largest earnings contributor, cutting net debt and boosting shareholder returns.
Revenue up 15% to US$58.8bn vs US$57,961m ests (1% beat)
Underlying EBITDA up 27% to US$32.9bn vs US$32,204m ests (2% beat), with copper contributing 54% at a 70% margin
Attributable profit up 9% to US$9.8bn, with underlying attributable profit up 30% to over US$13bn
Free cash flow up 83% to US$9.8bn, with net operating cashflow up 17% to US$21.8bn
Net debt of US$8.7bn, below the US$10-20bn target range, with gearing of 13.4% and ROCE of 26.1%
Capex up 5% to US$10.3bn, funding a copper pipeline targeting ~40% production growth by FY35
Fully franked final dividend of US 99 cps at a 72% payout, the largest in four years
FY26 total dividend of US 172 cps vs. Morgans and Macquarie ests of 157.7 and 160 cps respectively (9% and 7.5% beat)
Company page: BHP Group (BHP)
Region Group grows FFO and AFFO, guides to further 3% growth in FY27
[9:13 am] Region Group delivered steady FY26 earnings growth from its essential retail portfolio, supported by supermarket outperformance and disciplined capital management.
Statutory NPAT of $268.8m
FFO up 3.2% to 16.0 cps
AFFO up 2.9% to 14.1 cps, with 100% distributed to security holders
NTA up 4.0% to $2.57 per security
Comparable NOI growth of 3.3% and comparable MAT growth of 3.3%, driven by supermarket MAT growth of 4.1%
Portfolio occupancy up to 98.1% from 97.5%, with 380 specialty leases at 4.0% leasing spreads and 4.4% average annual rent increases
Over $1bn of debt refinanced at improved margins, WACD of 4.5% with 100% of debt hedged or fixed, and pro forma gearing below the midpoint of the 30-40% target range
FY27 guidance for 3.0% growth to FFO of 16.5 cps and 3.0% growth to AFFO of 14.5 cps, with a payout ratio of ~100% of AFFO
Company page: Region Group (RGN)
Cochlear lands at top of revised guidance as implant revenue stalls
[9:06 am] Cochlear delivered FY26 at the upper end of downgraded guidance, with flat cochlear implant revenue, a lower gross margin and foreign exchange headwinds weighing on profit.
Sales revenue up 2% in constant currency to $2,343m vs $2,331m ests (1% beat), with second-half growth of 6%
Gross margin down to 71% from 74% on sales mix, manufacturing variances and foreign exchange
Underlying NPAT of $322m, at the upper end of the revised $290-330m guidance
Cochlear implant units up 5% to 56,692, though implant revenue was flat in constant currency at $1.4bn on higher emerging market mix
R&D up 15% funding the drug-eluting electrode and totally implantable implant, with the Nucleus Nexa System reaching over 95% of developed market implant sales by June
Free cash flow up $141m to $264m, though a $109m non-cash impairment was taken on innovation fund investments led by Epiminder
FY27 guidance for low single-digit constant currency revenue growth and underlying NPAT of $330-350m (midpoint $340m), with the 70% dividend payout policy maintained
Here's how Cochlear's result stacks up against Macquarie's ests (31-Jul-26):
Revenue: $2,343m actual vs $2,323m Macquarie (1% beat)
Underlying NPAT: $322m actual vs $307m Macquarie (5% beat)
FY27 revenue guided to low single-digit CC growth (implying roughly $2,390-2,420m) vs Macquarie's $2,330m (~3% beat)
FY27 underlying NPAT guidance of $330-350m vs. Macquarie's $325m (~5% beat)
Worth noting: Cochlear is down 49% year-to-date but up 38% since 3 June. Short interest has slightly eased in the past ~6 weeks from highs of ~10% to 8.9%, but still very elevated.
Company page: Cochlear (COH)
RWC enters process deed with Brookfield on $4.75 per share proposal
[9:03 am] Reliance Worldwide has entered a process deed with Brookfield after receiving an improved $4.75 cash per share indicative proposal, opening the door to a scheme of arrangement.
Cash offer of $4.75 per share represents a 31.6% premium to the last close of $3.61
Values RWC at an enterprise value of ~$4.1bn, an FY26 EV/Adjusted EBITDA multiple of 12.1x post-AASB16
Follows earlier rejected Brookfield offers of $4.15, $4.25 and $4.50 per share, with the improved bid coming after an eight-week due diligence period
Exclusivity restrictions apply for four weeks to 15 September 2026, with both parties working towards a Scheme Implementation Deed
Board recommends shareholders take no action, with the proposal still subject to confirmatory due diligence and a binding SID
Company page: Reliance Worldwide (RWC)
RWC swings to slim profit as one-offs bite, Brookfield bid halts dividend
[9:01 am] Reliance Worldwide posted lower adjusted earnings on tariffs, higher copper costs and soft volumes, while an unsolicited Brookfield takeover proposal saw the Board pull the final dividend.
Group net sales of $1,305.6m vs $1,321m ests (1% miss), down 0.7%, or up 3.0% on an adjusted basis
Adjusted EBITDA down 12.8% to $242.1m vs $242m ests (in line), with margin down to 18.5% from 21.1%
Adjusted NPAT down 15.3% to $125.1m vs $119m ests (5% beat)
Reported NPAT of $6.3m, net of US$103.3m post-tax one-off charges tied to APAC metals restructuring
Net debt down to $243.4m from $331.6m, leverage of 1.11x, now below the target range
No final dividend declared and buy-back suspended following Brookfield's non-binding indicative proposal to acquire RWC
FY27 guidance for group sales up mid to high-single digits, with adjusted EBITDA margin broadly consistent with FY26
Company page: Reliance Worldwide (RWC)
Challenger lifts NPAT 3%, upsizes buy-back to $450m
[8:54 am] Challenger delivered FY26 result in-line with its guidance on strong annuity sales, boosted shareholder returns and set out a new reporting framework from FY27.
Normalised NPAT up 3% to $468m, with statutory NPAT up to $506m from $192m
Normalised EPS up 3% to 68.1 cps, in line with guidance
Annuity sales up 19% to $6.2bn, with annuity book growth of 10.7%
Normalised ROE of 11.6%, remaining above target, with PCA ratio of 1.38 times
Full-year ordinary dividend up 7% to 31.5 cps fully franked, plus a 1.5 cps special dividend
Upsized share buy-back to $450m, with a further $300m on-market buy-back announced today
FY27 Core Basic EPS guidance of 45-49 cps, with the 47 cps midpoint 6% above FY26 Core EPS of 44.2 cps
Company page: Challenger (CGF)
SRG Global posts record result, upgrades FY27 guidance
[8:49 am] SRG Global delivered a record FY26 beating upgraded guidance, swung back to net cash and lifted its FY27 earnings outlook on record work in hand.
Revenue up 27% to $1,675.5m vs $1,649m ests (2% beat)
Underlying EBITDA up 34% to $170.1m vs $167m ests (2% beat), with EBITDA to cash conversion of 101%
EBIT(A) up 41% to $131.8m
EPS(A) up 34% to 13.8 cents vs 12.9 cents ests (7% beat)
Total FY26 dividend up 27% to 7.0 cps fully franked vs. 7.0 cps ests (in-line)
Transitioned to net cash of $6.2m from proforma net debt of $52.5m post TAMS, with record work in hand of $5.1bn up 42%
Upgraded FY27 guidance to $195-205m EBITDA (midpoint $200m, 2% above $196m ests) and $150-160m EBIT(A)
Company page: SRG Global (SRG)
Deterra delivers record MAC volumes, cuts net debt in half
[8:43 am] Deterra posted a solid FY26 result driven by record iron ore royalty volumes and a sharp deleveraging following non-core asset sales.
Revenue from continuing operations up 6% to $236.2m
MAC revenue up 7% to $234.4m on record production of 151.8Mwmt (up 8%) and record sales of 140.1Mdmt (up 9%), partly offset by a realised iron ore price down 2% to $135.8/dmt
Underlying EBITDA up 6% to $222.2m at a 94% margin
NPAT up 5% to $164.2m
Total FY26 dividend up 5% to 23.2 cps fully franked, representing 75% of NPAT with the payout target maintained
Net debt cut to $132.5m from $270.6m, with undrawn facility capacity of $357.0m after divesting non-core precious metals assets for US$82m (~28% pre-tax IRR)
Thacker Pass lithium royalty advancing with US$1.2bn drawn of the US$2.2bn DOE loan, over 95% detailed engineering complete and mechanical completion targeted late CY27
Company page: Deterra Royalties (DRR)
Today's reporters: BHP, Cochlear, CSL and more
[8:41 am] We're in for a heavy day of results, spanning big hitters like BHP and CSL, plus various industrials, healthcare and financials. Here's a list of the names reporting today.
Amplitude Energy (AEL)
Aspen Group (APZ)
BHP Group (BHP)
Challenger (CGF)
Cochlear (COH)
Cogstate (CGS)
CSL (CSL)
EML Payments (EML)
HealthCo Healthcare & Wellness REIT (HCW)
Judo Capital (JDO)
Macmahon (MAH)
Pro Medicus (PME)
Region Group (RGN)
Reliance Worldwide Corp. (RWC)
Sims (SGM)
SKS Technologies Group (SKS)
Smart Parking (SPZ)
SRG Global (SRG)
Wagners (WGN)
China recovery loses steam as output, retail sales and property all soften
[9:39 am] China's economy lost momentum entering the second half, with yesterday's industrial output and retail sales missing forecasts and the property slump dragging on, renewing pressure for more stimulus.
Factory output up 4.5% year-on-year in July, slowing from 5.3% in June and missing the 4.8% consensus
Retail sales up 0.6%, down from 1% in June and well short of the 1.5% forecast, partly payback from last year's consumer goods trade-in scheme
Fixed-asset investment down 6.7% in the first seven months versus a 6% expected decline, worsening from a 5.7% fall in the first half
New home prices down 3.2% year-on-year in July and down 0.1% month-on-month, with only 17 of 70 surveyed cities recording monthly gains
Q2 GDP grew 4.3% year-on-year, the slowest pace in more than three years, keeping the economy reliant on exports to offset weak consumption
Source: Reuters
US-Iran ceasefire collapses as MoU expires with no deal
[8:34 am] The 60-day US-Iran Memorandum of Understanding lapsed on Monday with neither side willing to extend, as Trump demanded surrender and Iran threatened a shift to a fully offensive posture.
60-day MoU signed 17 June expired with no final deal, both sides accusing the other of violations, with Iran declaring there was no ceasefire to extend
A senior Iranian official told Reuters Tehran will move to a "fully offensive" military posture and could launch a "timely and precise" attack to break the US naval blockade if diplomacy fails
Trump ruled out extending the interim deal, called on Iran to "put up the white flag of surrender" and threatened to bomb US ally Oman if it "gets in the way" of a Hormuz deal
Trump claimed a direct backchannel to Iran's IRGC via former DNI Tulsi Gabbard and an Iraqi Kurdish intermediary, though the IRGC denies contact
Hormuz traffic remains crippled at roughly 3 vessels over 24 hours versus about 110 daily pre-war, with CENTCOM reporting 64 commercial vessels redirected, 3 disabled and 2 boarded
Trump ordered a "substantial" cut to US-South Korea military drills citing Seoul's lack of help on Iran, a move flagged as a risk to Asia-Pacific alliance confidence
Anthropic revenue run rate tops US$65bn ahead of IPO
[8:28 am] Anthropic's annualised revenue has surged more than sevenfold since late last year as it moves toward a public listing expected as soon as later this year. The data buoyed chipmakers, with names like SpaceX (+4.4%), Micron (+4.1%) and Intel (+0.9%) trading broadly higher.
Revenue run rate hit US$65bn by end-July, up more than 7x from around US$9bn in late 2025
Latest completed quarter revenue of more than US$11.5bn vs US$787m a year earlier (more than 14x higher)
Reported positive adjusted operating income for the quarter
Both Anthropic and OpenAI have filed confidential IPO paperwork, with Anthropic tipped to debut ahead of OpenAI
OpenAI's run rate recently topped US$40bn, though the two firms may not measure the metric the same way
Source: Bloomberg
US 30-year yield hits highest since 2007
[8:25 am] The selloff in long-dated US Treasuries deepened as investors demanded more compensation for inflation and fiscal risk, driving borrowing costs to near two-decade highs.
US 30-year yield rose ~6 bps to 5.31%, the loftiest since 2007, with the move echoed in Canada (highest since 2010) and Germany (2011 levels)
Gap between 2- and 30-year yields widened to 113bps, the steepest since April, as softer data trimmed expectations for a September Fed cut
Pressure driven by near US$2 trillion annual US deficits, heavy long-dated bond supply and inflation stuck above target, with CPI still running at 3.4% y/y
Corporate borrowing to fund the AI investment boom plus waning demand from traditional long-bond buyers are compounding the move
Citadel flagged the Fed's reluctance to tighten despite above-target inflation as an ongoing risk for markets, calling next month's meeting a "line-ball call" with more than 55% of core goods prices still rising
Source: Bloomberg
Good morning!
[8:11 am] ASX 200 futures are down 36 pts (-0.40%). Here's what happened overnight:
Major US benchmarks lower for a second-straight session as the US-Iran MoU expired with no deal or talks underway
S&P 500 (-0.52%), Dow (-0.51%), Nasdaq (-0.32%), Russell 2000 (-0.35%)
Equal-weight S&P 500 (-0.89%) after four straight all-time highs
Energy was the only sector to finish higher
Bond yields are pressuring equity markets, with the US 10-year breaking out to the highest since Jan-25 and US 30-year yield trading at a fresh 19-year high
Bond yield backup driven by surging government debt (~US$2tn annual deficits), rising oil prices (Brent up 2.5% to US$91.09), sticky inflation (US July CPI at 3.4%) and the Fed’s reluctance to hike rates
Chipmakers traded higher after Anthropic's revenue run rate topped US$65bn, reinforcing the view that AI infrastructure spending has further to run