In a nutshell:
Tech carried Wall Street as chipmakers rallied for a sixth straight session, offsetting a selloff in bank shares
Oil slid to a two-week low on signs Iran could reopen Hormuz within a week and Saudi Arabia could resume Yanbu exports
US and Iranian officials met for three hours on the UN sidelines in talks Trump called very productive
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,765 | -0.00% |
Dow Jones | 51,864 | -0.36% |
NASDAQ Comp | 27,244 | +0.45% |
Russell 2000 | 2,890 | +0.51% |
Global Indices | ||
 S&P/TSX | 36,336 | +0.91% |
 Shanghai Composite | 3,952 | +0.06% |
 DAX | 25,579 | +0.02% |
 Hang Seng | 25,088 | +0.18% |
 Nifty 50 | 74,529 | -0.44% |
 Nikkei 225 | 65,019 | +1.38% |
 FTSE 100 | 10,708 | -0.29% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,364.14 | +0.49% |
 Copper | 6.82 | +2.03% |
 WTI Oil | 89.85 | -2.73% |
Currency | ||
 AUD/USD | 0.7116 | +0.03% |
Cryptocurrency | ||
 Bitcoin (USD) | 86,192 | -0.27% |
 Ethereum (AUD) | 3,856 | -1.08% |
Miscellaneous | ||
US 10 Yr T-bond | 4.968 | +0.10% |
VIX | 14.21 | -4.44% |
US Sectors
Sector | % Chg |
|---|---|
| Materials | +1.90% |
| Consumer Staples | +1.20% |
| Information Technology | +0.63% |
| Health Care | +0.54% |
| Industrials | +0.19% |
| Real Estate | -0.19% |
Sector | % Chg |
|---|---|
| Consumer Discretionary | -0.19% |
| Utilities | -0.29% |
| Communication Services | -1.01% |
| Energy | -1.01% |
| Financials | -1.98% |
S&P 500 Session Chart
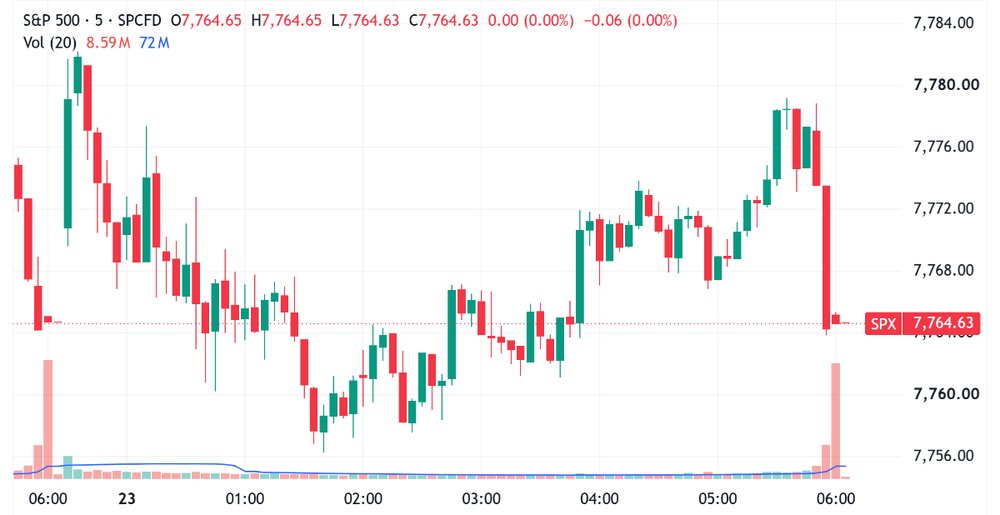
S&P 500 chopped sideways to close right on breakeven (Source: TradingView)
Overnight Markets
Major US benchmarks finished mixed in another tech-led session, where breadth was soft and the Dow slipped on bank and energy softness
Equities bounced after Trump said US officials had a "very good" meeting with Iranian envoys, a chip gauge rising for a sixth day as banks sold off (BBG)
S&P 500 financials fell 2% as AI agent competition fears hit wealth managers, with Schwab down 6.1%, while a flattening 2s10s yield curve weighed on banks (RT)
Brent touched its lowest level since September 8, trading near $98 a barrel, after a senior Iranian official said Hormuz could reopen within seven days if the US eases pressure (RT)
Treasury yields were little changed, the 10-year holding near 4.96% as investors awaited fresh clues on the economy (CNBC)
SoftBank drew more than $20bn of preliminary demand for what is shaping up as one of the largest junk bond deals ever, as investors chase record yields (BBG)
Stocks
Meta partnered with PayPal to let customers shop online using its Muse AI agents, after the app's climb to the top of the App Store drove an 11% rally on Monday (YF)
AutoZone shares rose about 5% after Q4 profit beat ests while revenue fell short, with the auto parts retailer flagging accelerating sales in 2027 (YF)
Tariffs
Trump said he supports banning US diesel exports, with Bessent examining whether a full or partial ban is workable given refining capacity (YF)
TD Cowen said a shift in US import policy on Chinese cars at this week's Trump-Xi summit is very unlikely, with the bilateral trade truce expiring in November (YF)
William Blair warned of volatility in ex-China rare earth stocks around the Trump-Xi talks, with Trump expected to press Beijing on magnet and critical mineral exports (YF)
Geopolitics
Trump told the UN he expects a deal with Iran right after November's midterms, saying he faces a choice between a deal and wiping out the Islamic Republic (YF)
Iran's Araghchi set out Hormuz reopening terms to US envoy Witkoff, including lifting the naval blockade and releasing frozen assets, IRIB reported (CNN)
A senior Iranian official denied reports of a seven-day Hormuz reopening offer, speaking to CNBC partner MS Now (CNBC)
Zelensky said he discussed an energy ceasefire with Trump and is ready for a trilateral meeting with Putin, but got no concrete answer on extra interceptors (CNN)
Trump said Russia has lost control of its diesel industry because of the war, ahead of talks where he was expected to push Kyiv toward an energy truce (CNBC)
Britain will provide air-to-air refuelling for Saudi jets against the Houthis for a matter of weeks, PM Andy Burnham said (CNBC)
Saudi Arabia began restarting its East-West oil pipeline after drone attacks halted it, aiming to restore exports through the line later this week (BBG)
Saudi Aramco loaded about 14 million barrels on seven supertankers inside the Gulf on Sunday, tanker data showed, lifting Hormuz exports after the Yanbu disruption (RT)
Saxo's Ole Hansen sees little further oil downside until Hormuz supply increases, particularly for refined products where shortages are most acute (RT)
Central Banks
Richmond Fed's Barkin said supply shocks are not proving short-lived, leaving the door open to further hikes after last week's increase (YF)
Economy
Taiwan export orders jumped 71.4% year-on-year to a record $103bn in August, topping $100bn for the first time and beating ests of 63.6% (RT)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Silver Miners | 97.41 | +3.89% |
| Gold Miners | 97.83 | +3.60% |
| Copper Miners | 89.98 | +2.85% |
| Uranium | 43.74 | +1.77% |
| Strategic Metals | 70.97 | +1.00% |
| Lithium & Battery Tech | 71.33 | +0.71% |
| Steel | 106.73 | +0.61% |
Industrials | ||
| Construction | 93.48 | +0.93% |
| Global Jets | 29.12 | +0.38% |
| Agriculture | 28.55 | -0.45% |
| Aerospace & Defense | 214.0 | -0.99% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 210.81 | +1.76% |
Renewables | ||
| Hydrogen | 45.5775 | +1.22% |
| Solar | 46.5 | -0.45% |
Technology | ||
| Semiconductor | 572.78 | +2.40% |
| Cybersecurity | 46.23 | +0.57% |
| Robotics & AI | 36.01 | +0.53% |
| Data Center & Digital Infrastructure | 28.79 | +0.35% |
| Electric Vehicles | 34.3682 | +0.29% |
| FinTech | 25.995 | +0.17% |
| Cloud Computing | 28.95 | +0.07% |
ASX Today
Where are we now? The ASX 200 sits ~1% above its 15 September low, which capped a 6.5% pullback from the 6 August high. The market is trying to carve out a low as peak central bank hawkishness starts to fade and oil moves in the right direction. That said, it still has to get through the back end of a seasonally weak September, and breadth under the hood has been notably poor. Over the past month, local Tech has tanked 13.5%, while Discretionary, Real Estate and Materials are each down 6-7%. Put simply, participation remains thin and more evidence is needed before we can say the market is out of the woods
Ballard Mining lifts the Mt Ida global resource 56% to 1.84Moz at 2.8g/t, with the cornerstone Baldock deposit up 35% to 1.36Moz at 3.5g/t on 125km of drilling since February. Discovery cost of $36/oz. Feasibility study and maiden reserve on track for mid-CY27 (BM1)
Capricorn Metals completes the Karlawinda Expansion Project on schedule and in 12 months, achieving the targeted 6.5Mtpa steady state throughput. Expanded operation to produce around 150koz a year on a mine life of more than 10 years from existing reserves (CMM)\
Nufarm guides FY26 underlying EBITDA to $370-380m, up ~25% on pcp at the midpoint, with leverage falling to ~2.0x at 30 September from 2.7x a year earlier. On track for $50m of run-rate cost savings by end-FY27 as it closes the Alsip and Kwinana sites (NUF)
What To Watch Today
Copper hit a fresh all-time high, rising 1.6% to US$6.92/lb to extend a six-session run of 8%. The V-shaped recovery has taken prices ~0.8% above where they traded before US refined copper tariff headlines sparked a sharp ~5% pullback on 10 September. Copper miners have been slower to catch up, with the Global X Copper Miners ETF up 2.8% overnight but still 5.8% below its 9 September high
Gold reversed an intraday ~1.1% dip to close 0.35% higher at US$4,357/oz. Price action remains choppy, but the rebound sparked a strong move in the miners, with the VanEck Gold Miners ETF up 3.6% to a near two-week high, though still ~7% below its 25 August peak
Key Events
Stocks trading ex-dividend:
Wed 23 Sep: Genesis Energy (GNE) – $0.063, IPD Group (IPG) – $0.079, St Barbara (SBM) – $0.05
Thu 24 Sep: Bisalloy Steel Group (BIS) – $0.13, Briscoe Group Australasia (BGP) – $0.081, PRL Global (PRG) – $0.03, Salter Brothers Emerging Companies (SB2) – $0.02, Wiseway Group (WWG) – $0.006
Fri 25 Sep: Teaminvest Private Group (TIP) – $0.015
Other ASX corporate actions today:
Dividends paid: Aurizon (AZJ), Australian Clinical Labs (ACL), BHP Group (BHP), Contact Energy (CEN), Dusk Group (DSK), GR Engineering Services (GNG), L1 Group (L1G), Motorcycle (MTO), NZME (NZM), Regis Healthcare (REG), Santos (STO), Smartgroup Corporation (SIQ), Summerset Group (SNZ)
Earnings: None
IPOs: None
Economic calendar (AEST):
9:00 am: Australia S&P Manufacturing and Services PMI
6:00 pm: UK S&P Manufacturing and Services PMI