In a nutshell:
A post-election AI trade unwind spilled into the broader market, sending Wall Street to its worst session since the April 2025 tariff crash and the Nasdaq into correction
Investors priced in Democratic scrutiny of data centres, hitting chipmakers, neoclouds, Musk-linked stocks and AI software winners alike
Bank of England raised rates to 4% in its first hike since 2023, while Fed officials Hammack and Barkin backed further gradual tightening
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,354 | -4.36% |
Dow Jones | 51,523 | -3.44% |
NASDAQ Comp | 24,315 | -5.52% |
Russell 2000 | 2,732 | -4.39% |
Global Indices | ||
 S&P/TSX | 35,605 | -2.03% |
 Shanghai Composite | 3,690 | +0.10% |
 DAX | 26,325 | -0.43% |
 Hang Seng | 24,797 | +3.67% |
 Nifty 50 | 79,310 | +2.60% |
 Nikkei 225 | 61,078 | -1.79% |
 FTSE 100 | 10,783 | -0.43% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,090.4 | +0.74% |
 Copper | 6.18 | -3.43% |
 WTI Oil | 90.69 | +2.92% |
Currency | ||
 AUD/USD | 0.693 | -1.08% |
Cryptocurrency | ||
 Bitcoin (USD) | 75,821 | -5.41% |
 Ethereum (AUD) | 3,225 | -7.58% |
Miscellaneous | ||
US 10 Yr T-bond | 4.837 | -1.16% |
VIX | 26.93 | +61.50% |
US Sectors
Sector | % Chg |
|---|---|
| Consumer Staples | -0.67% |
| Utilities | -0.71% |
| Real Estate | -1.82% |
| Communication Services | -1.86% |
| Health Care | -2.50% |
| Materials | -2.70% |
Sector | % Chg |
|---|---|
| Financials | -2.74% |
| Energy | -2.81% |
| Consumer Discretionary | -3.74% |
| Industrials | -4.12% |
| Information Technology | -7.30% |
S&P 500 Session Chart
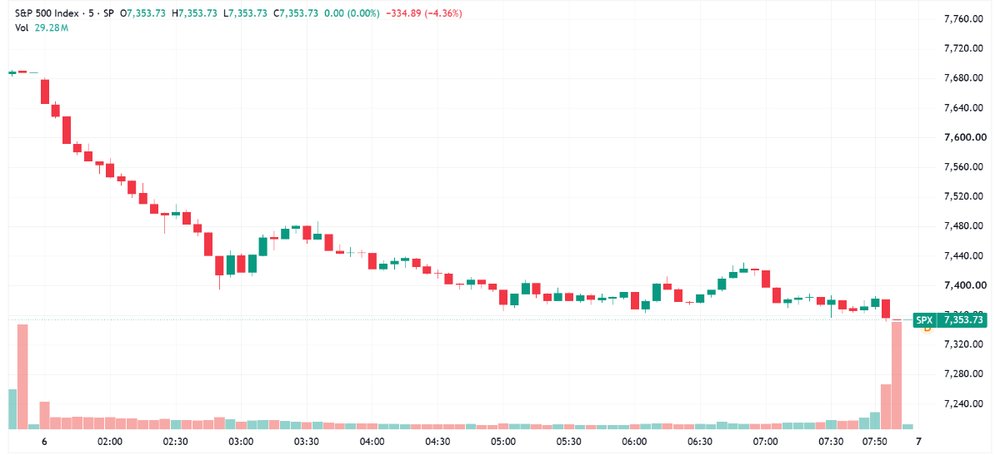
S&P 500 trends aggressively lower to close at worst levels (Source: TradingView)
Overnight Markets
Major US benchmarks sharply lower as a post-midterm rotation out of chipmakers snowballed into a broad rout, with all 11 S&P 500 sectors in the red and the Nasdaq 100 shedding about $1.9tn in value
Philadelphia Semiconductor Index is down 10% and on track for a fifth straight weekly drop, its longest losing streak since April 2025, as investors turned sceptical on the AI trade after the Democrats’ midterm sweep
Some of the standout fallers include: Nvidia (-9%) Broadcom (-9.4%) AMD (-15%) SpaceX (-8.3%) Marvel (-15%) Micron (-15%)
Brent crude gained 4% to US$98 a barrel, recovering part of Wednesday’s 9% slide, the oil has still lost 11% this week
Gold climbed to around US$4,120 an ounce, holding back above US$4,000 after a two-day rally
VIX posted its biggest one-day jump (+61%) in more than two years, while the Dow headed for its worst second session after a midterm in data back to 1896 (YF)
Treasuries rallied as the tech selloff fuelled haven demand, with yields falling as much as 9bp across maturities to the lowest levels since early September (BBG)
Bond traders bet the Democratic sweep will contain Trump’s tax and spending plans and cap Treasury supply, after months of deficit jitters pushed yields to multi-year highs (BBG)
Apple drew solid demand for an approximately $7bn high-grade bond sale, adding to a flurry of AI-era tech issuance after Alphabet, Meta and Oracle tapped debt markets this week (BBG)
Goldman Sachs said the scale of the Democratic victory carries major implications for AI and data centre regulation, as the post-midterm rotation hit Asian chipmakers SK Hynix and Samsung (BBG)
SimCorp’s Melissa Brown said investors appear to be recognising that some newly elected members of Congress and governors want to slow the pace of AI infrastructure development (RT)
Eurasia Group said renewed escalation in the Iran conflict would likely lift Brent into a US$110 to US$125 a barrel range, despite this week’s sharp declines (CNBC)
Yardeni Research’s said 10-year Treasuries yielding around 5% offer an attractive real return, though he expects stocks to keep outperforming bonds over the long term (BBG)
Stocks
Nvidia was by far the heaviest drag on the S&P 500 as the AI chip wipeout deepened for a second day, with Advanced Micro Devices among the steepest decliners (AP)
Qualcomm slumped after fiscal Q4 smartphone chip sales fell short of ests on sluggish demand and declining Apple-related revenue, adding to pressure on chipmakers already hit by post-midterm regulation fears (RT)
Arm Q2 FY27 revenue up 27% to US$1.44bn, ~5% ahead of ests, licensing up 50% to US$773m, EPS beat by ~11%. Q3 revenue guidance only in line with ests and shares fell ~11% (YF)
Apple is set to raise US$7.5bn from a seven-part high-grade bond sale, drawing about US$31bn of orders as investors seek a break from AI-related debt despite the selloff (BBG)
Tesla and SpaceX shed about $130bn in combined market value as Democratic gains in Texas, where both companies are based, raised political and regulatory risks for Elon Musk’s businesses (BBG)
Geopolitics
Iran reported three more tankers damaged in the Strait of Hormuz, while two sources told Reuters they expect Trump to order a resumption of hostilities now the midterms are over (RT)
Trump faces a decision on the next phase of the unpopular eight-month war against Iran after the conflict contributed to the Republicans’ midterm drubbing (AP)
Tariffs & Trade
US tariffs on Canadian kitchen cabinets are set to double to 50% on 1 January, with the Canadian industry association warning many manufacturers would shut (RT)
China says buying more US farm goods hinges on tariff cuts, requiring both sides implement their agreed US$30bn-for-US$30bn reciprocal tariff reduction arrangement, says the commerce ministry (IVST)
The new Democratic Congress is set to target tariffs, healthcare and Trump's allies after sweeping both chambers in the midterms (YF)
Central Banks
Bank of England raised Bank Rate 25bp to 4%, its first hike since August 2023, with all nine policymakers backing tighter policy and Catherine Mann voting for a half-point move (BBG)
Bank of England forecast UK inflation near 5% by mid-2027 and warned further hikes may be needed if the US-Iran conflict keeps energy prices elevated (RT)
Cleveland Fed’s Beth Hammack said rates need to move to a restrictive stance to return inflation to 2% in a timely manner, favouring more frequent, smaller adjustments (BBG)
Richmond Fed’s Tom Barkin said more rate hikes are coming but at a gradual pace, citing unemployment near record lows and inflation that remains too high (CNBC)
Markets broadly expect another Fed hike in December after the central bank held at 3.75% to 4% last week, with Governor Lisa Cook and Hammack dissenting in favour of a rise (RT)
ECB President Christine Lagarde said incoming indicators will determine whether a December hike is necessary, after the ECB held its deposit rate at 2.5% last week (RT)
Economy
US initial jobless claims fell 6,000 to 189,000 in the week to 31 October versus ests of 196,000, holding near 57-year lows (RT)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Gold Miners | 85.74 | +1.36% |
| Silver Miners | 77.34 | -0.99% |
| Strategic Metals | 50.54 | -2.30% |
| Lithium & Battery Tech | 60.28 | -2.59% |
| Steel | 96.26 | -3.49% |
| Uranium | 30.975 | -5.28% |
| Copper Miners | 70.4 | -5.58% |
Industrials | ||
| Agriculture | 26.165 | -1.08% |
| Global Jets | 28.37 | -3.70% |
| Aerospace & Defense | 68.054 | -4.08% |
| Construction | 85.923 | -5.97% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 209.99 | -5.04% |
Renewables | ||
| Solar | 44.075 | -3.75% |
| Hydrogen | 32.25 | -9.49% |
Technology | ||
| FinTech | 24.14 | -3.50% |
| Data Center & Digital Infrastructure | 24.74 | -4.66% |
| Cloud Computing | 26.15 | -5.42% |
| Electric Vehicles | 27.81 | -5.52% |
| Robotics & AI | 30.64 | -6.61% |
| Cybersecurity | 43.82 | -6.73% |
| Semiconductor | 131.9 | -12.15% |
ASX Today
Briscoe Group’s third-quarter sales rose 1.98% to NZ$174.4m, its fourth consecutive quarter of growth, led by a 3.99% lift in sporting goods and a 5.77% rise in online sales. The retailer expects full-year net profit of up to NZ$55m, with earnings weighed down by costs from its new North Island distribution centre and SAP upgrade (BGP)
James Hardie posts Q2 FY27 net sales of US$1,428.2m, up 24% and at the top end of guidance, with adjusted EBITDA up 44% to US$454.7m and margin 450bps higher at 31.8%, above the guided range. Reaffirms FY27 sales and EBITDA guidance and lifts its free cash flow target to more than US$650m (JHX)
Macquarie Group delivers 1H27 net profit of $2,478m, up 50% on 1H26 and down 22% on 2H26, with EPS of $6.52. Annualised ROE of 13.8% compares with 14.0% in FY26. Declares a $3.25 interim dividend, 35% franked, at a 50% payout. Shemara Wikramanayake’s final result before Greg Ward takes over (MQG)
What To Watch Today
Good morning, Kerry here (Joe’s done the rest) – Today’s going to be the inverse of yesterday, and possibly more painful for some pockets of the market.
The selloff in a nutshell. Goldman Sachs’ trading desk says yesterday’s post-election rebound has been completely wiped out, with AI-linked chips and infrastructure copping the brunt as hedge funds dump hyperscalers they’d only just bought back and leverage unwinds, with prime brokerage clients’ gross exposure sitting at the 97th percentile over five years. The debate has shifted from long-term AI demand to the pace and funding of the buildout, with rising financing costs and post-midterm political and regulatory pressure on data centres dragging the SOX down 10%.
Carnage, carnage everywhere. Our overnight ETF watchlist had sectors like Biotech, Copper Miners, Cloud and Uranium all down more than 5%. Pretty much all of them have given back yesterday’s gains. On the S&P 500 (-4.3%), Staples (-0.67%) and Utilities (-0.71%) managed to offer some decent relative outperformance. While the VanEck Gold Miners ETF (+1.3%) managed to eke out a small gain. Even though Brent bounced around ~4% to US$98 a barrel, Energy equities still tanked 2.8% as broader growth concerns outweighed the gains from the underlying commodity. On the flip side, it’ll be interesting to see just how well local Staples hold up, and whether or not a pivot for safe havens will drive any buying for the Big Four Banks.
Key Events
Stocks trading ex-dividend:
Fri 6 Nov: New Murchison Gold (NMG) – $0.003
Mon 9 Nov: Clime Capital (CAM) – $0.005, Future Generation Australia (FGX) – $0.038, NAOS Ex-50 Opportunities Company (NAC) – $0.016, NAOS Small Cap Opportunities Company (NSC) – $0.01
Tue 10 Nov: None
Wed 11 Nov: ResMed (RMD) – $0.066
Other ASX corporate actions today:
Dividends paid: Gowing Bros (GOW), N1 Holdings (N1H), Cobram Estate Olives (CBO)
IPOs: None
AGMs: Coles (COL), Spark New Zealand (SPK), Nine Entertainment (NEC), Qantas (QAN), Jumbo Interactive (JIN)
Economic calendar (AEDT):
No major economic events today