In a nutshell:
Major US benchmarks lower and near worst levels as tech megacaps led a broad AI selloff causing the Nasdaq's steepest daily drop since early June, while the Dow finished flat with consumer staples and energy outperforming
Meta’s first cash outflow in more than a decade and plans to issue non-voting shares reignited AI funding fears, sending chipmakers to their steepest drop since July
Brent topped US$112 a barrel, a five-month high, after deadly Houthi attacks in Saudi Arabia and Iranian claims that seven tankers were hit in Hormuz
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,663 | -1.21% |
Dow Jones | 52,868 | +0.02% |
NASDAQ Comp | 26,009 | -2.60% |
Russell 2000 | 2,784 | +0.11% |
Global Indices | ||
 S&P/TSX | 35,973 | -0.97% |
 Shanghai Composite | 3,658 | -1.48% |
 DAX | 25,372 | -1.07% |
 Hang Seng | 22,935 | -3.03% |
 Nifty 50 | 73,249 | -0.62% |
 Nikkei 225 | 62,908 | -2.65% |
 FTSE 100 | 10,725 | -0.26% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,024.21 | -2.82% |
 Copper | 6.36 | -2.72% |
 WTI Oil | 99.1 | +2.01% |
Currency | ||
 AUD/USD | 0.702 | +0.00% |
Cryptocurrency | ||
 Bitcoin (USD) | 81,172 | -4.26% |
 Ethereum (AUD) | 3,392 | -4.44% |
Miscellaneous | ||
US 10 Yr T-bond | 4.953 | -3.75% |
VIX | 19.03 | +14.09% |
US Sectors
Sector | % Chg |
|---|---|
| Consumer Staples | +3.11% |
| Utilities | +1.98% |
| Health Care | +1.33% |
| Financials | +1.18% |
| Real Estate | +0.92% |
| Materials | +0.33% |
Sector | % Chg |
|---|---|
| Energy | -0.74% |
| Industrials | -0.91% |
| Consumer Discretionary | -1.71% |
| Information Technology | -3.00% |
| Communication Services | -3.02% |
S&P 500 Session Chart
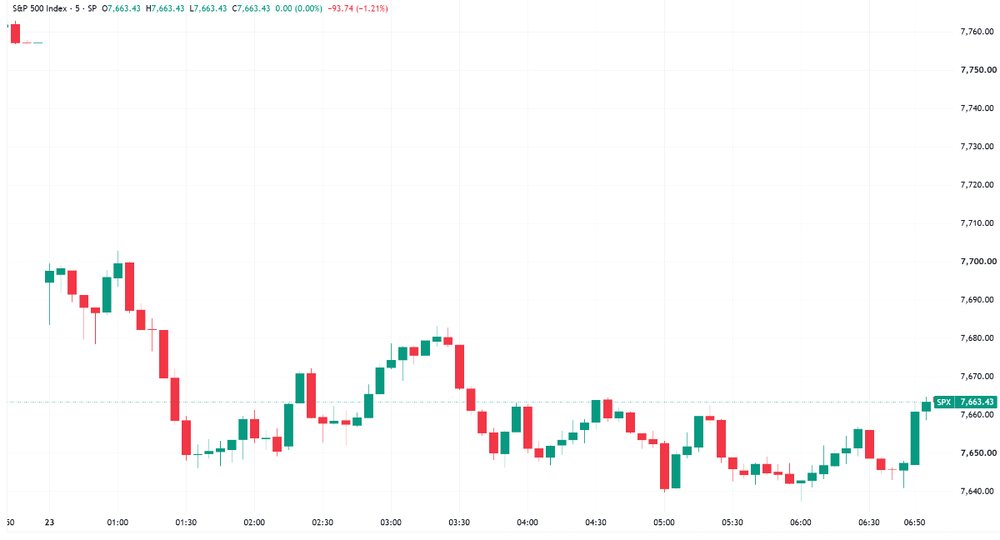
S&P 500 opened lower and traded gently down throughout the session to finish just off worst levels (Source: TradingView)
Overnight Markets
Major US benchmarks mostly lower, finished off worst levels as tech megacaps led a broad AI selloff, with the Dow ending little changed and the Nasdaq dragged by semiconductors reversing Wednesday’s gains
Precious and base metals are trading sharply lower, with gold down 2.8% to US$4,021/oz, its lowest in more than two months. Silver has slumped nearly 6% to US$54.56/oz, its weakest level since December 2025, taking its fall since late August to 21%, while copper has slipped 2.6% to US$6.40/lb, a one-month low
Philadelphia Semiconductor Index (SOX) fell more than 6.7%, its steepest drop since July, while an equal-weighted S&P 500 rose and was on track for its best relative day since 2024 (BBG)
US 10-year yields fell below 5% for the first time in a month, while 2- and 30-year yields dropped 15 bps and 12 bps, respectively, to their lowest in a month. The cost of options hedging against a deeper bond rally hit its highest since March (BBG)
Brent traded above US$112 a barrel and WTI near US$99 after a drone strike near Saudi Aramco’s Shaybah field killed two people, though operations were unaffected (BBG)
Meta’s credit risk hit a record high as plans to lift capital spending revived fears that tech giants will issue more debt to fund the AI buildout (BBG)
Goldman’s prime brokerage said hedge fund short sales outpaced long purchases about five to one this month, with short leverage in the 99th percentile of the past five years, flagging squeeze risk (BBG)
Alternative Credit Council said fears over private credit were divorced from market reality, citing a 17% year-on-year rise in industry assets under management to $4.1tn (BBG)
Kospi fell more than 3%, Nikkei 2.7% and Hang Seng 3.1% as SK Hynix, Samsung and Tokyo Electron slid on revived fears over the AI investment boom (AFP)
Stocks
Meta shares slid 7% despite third-quarter results beating ests, after the Facebook parent posted its first cash outflow in more than a decade on AI spending and unveiled a two-for-one split via non-voting shares to raise capital for the AI buildout (RT)
Tesla Q3: adjusted EPS 48c beat ests by ~12%, revenue $28.05bn just ahead of ests, core auto revenue down 3% year-on-year and energy revenue down 16% to $2.88bn. Shares fell as investors questioned a cut to 2026 capex guidance to $20bn from more than $25bn (CNBC)
Procter & Gamble Q1 FY27 revenue up 4% to $23.3bn, ~2% ahead of ests, organic sales up 4% versus 2.4% ests and core EPS of $2.00 beat by ~6%. Shares rose as defensives caught a bid (CNBC)
Lockheed Martin Q3 sales up 11% to $20.7bn, ~1% ahead of ests, EPS of $7.97 beat by ~6% and backlog hit a record $292bn. Raised 2026 guidance for a second straight quarter, shares among the S&P 500's top gainers (CNBC)
Nvidia chief Jensen Huang told CNBC that capital to fund the AI investment boom was becoming scarce due to higher interest rates and a glut of existing spending commitments, adding fuel to Thursday’s Nasdaq slide (NBC)
Moderna shares plunged as much as 26%, a record intraday drop, and partner Merck also fell after data on the companies’ closely watched personalised melanoma vaccine disappointed Wall Street (BBG)
Spotify monthly active users rose 11% year-on-year to 788m and fourth-quarter revenue guidance topped ests, lifting shares (CNBC)
Geopolitics
Iran’s state TV said seven oil tankers were struck or hit naval mines in the Strait of Hormuz overnight, potentially the most vessels damaged in a single day since the war began (AP)
Iran’s Revolutionary Guard navy threatened to strike US military bases if Washington keeps guiding commercial ships through Hormuz, as the US sends more military assets to the region (AP)
Trump accused Iran on Truth Social of fabricating tanker hits and mines to push oil prices higher before the 3 November midterm elections (RT)
Central Banks
Treasuries rallied across the curve, trimming yields by as much as 13bps, helped by haven demand and fading expectations for Fed rate hikes next year (BBG)
Turkey’s central bank cut its one-week repo rate by 100bps to 36%, in line with ests, as inflation fell to 29.7% year-on-year in September, below 30% for the first time since late 2021 (Investing.com)
Tariffs
Doubts over a US tariff on refined copper fuelled the metal's retreat from September's record $14,875 a tonne, as Comex prices fell to near parity with the LME (BBG)
Economy
US initial jobless claims fell 6,000 to 194,000 in the week to 17 October, a three-month low and below ests of 200,000 (BBG)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Steel | 99.96 | -3.29% |
| Strategic Metals | 51.6 | -3.32% |
| Lithium & Battery Tech | 60.68 | -3.99% |
| Uranium | 34.09 | -4.11% |
| Gold Miners | 81.69 | -5.80% |
| Copper Miners | 73.13 | -6.27% |
| Silver Miners | 75.99 | -6.65% |
Industrials | ||
| Global Jets | 26.77 | +1.36% |
| Aerospace & Defense | 204.48 | -0.64% |
| Agriculture | 27.92 | -0.71% |
| Construction | 86.59 | -0.78% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 209.54 | -0.95% |
Renewables | ||
| Solar | 41.35 | -2.84% |
| Hydrogen | 36.39 | -4.69% |
Technology | ||
| Cybersecurity | 47.56 | +1.34% |
| Cloud Computing | 29.66 | +0.10% |
| FinTech | 24.9394 | +0.03% |
| Data Center & Digital Infrastructure | 24.95 | -2.58% |
| Robotics & AI | 32.68 | -2.71% |
| Electric Vehicles | 29.4839 | -3.96% |
| Semiconductor | 475.69 | -6.79% |
ASX Today
Alkane Resources posts Q1 FY27 consolidated production of 40,740oz gold equivalent with guidance unchanged. Tomingley contributed 21,506oz at an AISC of $2,340/oz and $52m of operating cash flow, tracking inside FY27 guidance of 78-84koz at $2,600-2,900/oz (ALK)
Black Cat Syndicate produces 16,740oz of its own gold at an AISC of $3,735/oz in Q1 and maintains FY27 guidance of 80-90koz at $3,500-3,900/oz. Cash and investments fall from $105m to $78m on growth capex and drilling. Chris Stone starts as Managing Director (BC8)
Mineral Resources maintains FY27 guidance across all divisions, with Onslow shipping 9.2M wmt at an FOB cost of $53/wmt, below the $54-58 guidance range. Record lithium sales of 170k dmt SC6 and net debt down $0.2bn to $4.1bn. ASIC closed its investigation with no enforcement action (MIN)
Ora Banda Mining produces 33,305oz in Q1 at an AISC of $4,214/oz, with unit costs elevated by an extended mill shutdown and weather, though FY27 guidance is maintained. Waihi underground development started ahead of schedule and the revolving credit facility lifts to $300m, taking liquidity to $507m (OBM)
Temple & Webster reports revenue down 8% on pcp from 1 July to 19 October as it cuts promotional depth and lifts prices, though contribution margin dollars are up 16%. Run-rate revenue growth has improved to -4% from -13% at the August update. Reaffirms FY27 EBITDA of $33-40m (TPW)
Zip Co reconfirms FY27 cash EBTDA guidance of $340m after 1Q TTV of $4.6bn, up 18%, and total income of $376.1m, up 17%. Cash EBTDA of $65.0m includes $10.1m of costs tied to a US fraud event, with adjusted cash EBTDA up 19.5% to $75.1m (ZIP)
What To Watch Today
Kerry here! ASX futures are a littler lower as we continue to see miners sell off, and defensives catch a bid.
AI in the dumpster. The SOX fell 6.7% to its lowest level since late July, when the sector was smashed by a mix of escalating capex concerns, lofty valuations, debt worries and macro headwinds. Arguably, all of those drivers look a lot worse now. Except for valuations, where semiconductor earnings are up ~175% year-on-year, yet the sector's price-to-earnings has collapsed to around 14x, which tells you the market really doesn’t believe the profit outlook.
Yields tumble, for the wrong reasons. Something we’ve flagged a few times across the wrap and blog is that bond yields have topped out because growth expectations are easing, not because of inflation. So if growth was the thing holding markets together, what happens when those expectations start to fall?
Defensives back in favour. Another classic flight to safety on Wall Street, with staples, utilities, healthcare and financials all up more than 1%. Getting defensive makes sense, but paying ~43x earnings for something like Walmart is a tough ask. On the ASX, the defensive pivot has been building since mid-October. Over the past month, staples, utilities and healthcare have rallied 8.5%, 6.6% and 6.2% respectively. And with yields falling, you have to wonder whether a rate-sensitive sector like REITs (Charter Hall in particular) can catch a bid too.
And there goes the commodities trade. Easing growth expectations and a faltering AI trade sent commodities into a sea of red, led by silver (-5.8% to US$54.60/oz), gold (-2.8% to US$4,025/oz) and copper (-2.7% to US$6.49/lb). Our overnight ETF watchlist was sharply lower too, led by Silver Miners (-6.6%), Copper Miners (-6.2%) and Gold Miners (-5.8%). Expect that selling to carry into Friday’s session. Copper prices are still around 13% higher year-to-date, yet the Global X Copper Miners ETF is back to breakeven (and down ~20% over the past two months). That suggests copper equities have started pricing in the same things driving yields lower, namely slower growth and higher costs.
Key Events
Stocks trading ex-dividend:
Fri 23 Oct: Spheria Emerging Companies (SEC) – $0.011
Mon 26 Oct: Alcoa Corporation (AAI) – $0.101
Tue 27 Oct: Bank of Queensland (BOQ) – $0.20
Wed 28 Oct: None
Thu 29 Oct: Autosports Group (ASG) – $0.03, Benjamin Hornigold (BHD) – $0.062, Waterco (WAT) – $0.13
Other ASX corporate actions today:
Dividends paid: ARB Corp (ARB), Civmec (CVL), EQT Holdings (EQT), Horizon Oil (HZN), PRL Global (PRG)
IPOs: None
AGMs: Aussie Broadband (ABB), McMillan Shakespeare (MMS), Reliance Worldwide Corporation (RWC)
Economic calendar (AEDT):
9:00 am: Australian S&P Manufacturing and Services PMI
5:00 pm: UK Retail Sales
7:00 pm : Eurozone S&P Manufacturing and Services PMI
12:45 am: US S&P Manufacturing and Services PMI