ASX 200 Live Today - Monday, 17th August
The S&P/ASX 200 is set to fall for a fourth straight session as reporting season heats up. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Monday, August 17. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Reporting season is heating up and we've got you covered. Our reporting season calendar has over 250 stocks plus earnings and dividend estimates.
ASX 200 lower as miners fail to offset weakness from banks, REITs and retailers
[2:20 pm] A bit of a 'thinking out loud' closing post, as we wrap up a dicey day on markets.
ASX 200 currently down 33 pts (0.37%), on track to record a fourth-straight day of losses and down six of the last seven sessions
Materials (+1.58%) snapping a three-day losing streak, with broad gains across the commodity complex, but headlined by lithium, gold and copper names
PLS Group up 4.3%, IGO up 3.5%
All Ords Gold Index up 3.2%, highest since 22-Apr and up 23.4% since 30-Jul
Aeris Resources up 3.7%, Sandfire up 2.3%, Firefly Metals up 2.1%
Discretionary (-3.0%) tumbles as JB Hi-Fi slides 11.7%
JB Hi-Fi's FY26 result itself was relatively in-line
Total sales growth for JB Hi-Fi Australia by quarter ran from 6.0% in Q1 to 6.5% in Q2, 4.0% in Q3 and just 0.3% in Q4, while its FY27 trading update (1-31 July) had total sales down 0.5%, so momentum is very, very weak
Financials (-1.4%) also weighed by NAB's disappointing Q3 update, which featured:
Cash earnings of $1.83bn vs $1.87bn ests (2% miss), up 2% on the 1H26 quarterly average ex the large notable item
NIM of 1.79% vs 1.83% ests (4bps miss), or up 2bps ex markets and treasury
Credit impairment charges of $299m vs $250m ests, heavier than expected on higher collective provision charges
So far, we've seen Westpac and NAB both tumble 4-5% on weak quarterlies, ANZ rallied 4.5% on a better-than-expected Q3 and CBA finished 0.6% lower on the day of its FY26 result (12-Aug)
Breadth was fairly weak outside of these sectors, with Real Estate (-1.2%), Utilities (-0.7%), Staples (-0.6%), Healthcare (-0.5%) and Tech (0.4%) trading lower
Overall, the ASX 200 is pulling back amid a sharp correction for heavyweight banks. CBA rallied around 12% between 1 July and 4 August (within ~1.5% of all-time highs). It has since dipped around 7.8%.
Elsewhere, copper is up 1.7% to US$6.80/lb on Monday, trading pretty much in-line with its record 5-Aug close. Meanwhile, copper equities are trading marginally higher, most of which are 5-10% away from early-mid June highs.
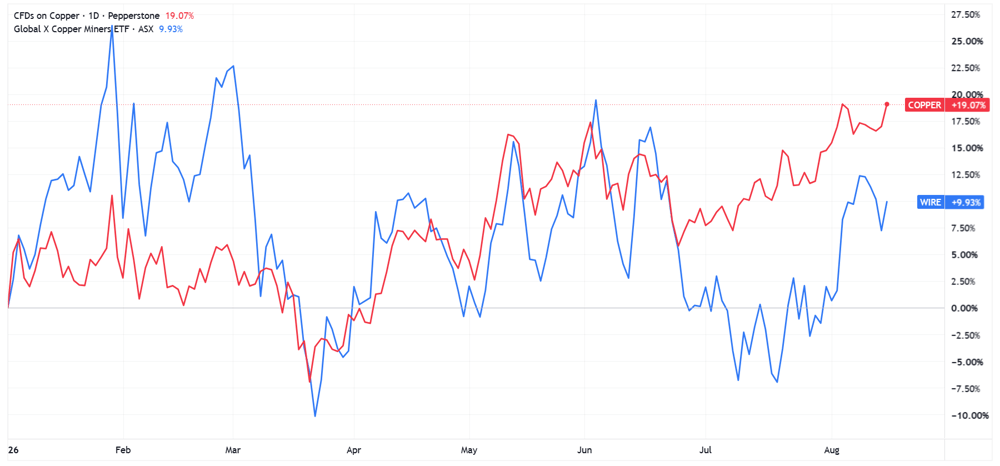
Global X Copper Miners ETF (blue) vs. copper (red) | Source: TradingView)
This dynamic reminds me of Cannacord's commentary from last month, which noted: "Copper prices have remained relatively robust, even as the physical market remains relatively tepid and surplus exchange inventories remain near two-decade highs ... We believe the ambiguity is serving to maintain a speculative element in pricing, along with a still-strong narrative around data centre construction. We note that the copper equities do not buy this narrative, over the last month, the copper producers in our coverage universe have declined by 13%". Something's eventually got to give.
ACL FY26 earnings call highlights: Billing and efficiency drivers as pathology volumes stay soft
[1:56 pm] Management framed FY26 as margin gains delivered through deliberate portfolio and cost decisions, with billing initiatives and a soft market recovery seen driving the next phase.
On the fee cuts absorbed: "we absorbed roughly $14 million of net Medicare fee cuts from the B12 and urine tests ... We made it back"
On the structural nature of the savings: "these are all structural changes to the cost base. They are not one-off savings"
On the billing opportunity, from the outgoing CEO: "It's quite an untapped opportunity for the business, and we've got the system set up now, and we see further upside into future years"
On price elasticity: "the walkout rates are probably ... about 8%, it is quite low. Those people would have been not paid anyway ... They will not be funded next door at a competitor either"
On the demand backdrop, from the incoming CEO: "the pathology yield per GP consult has continued to improve ... meaning when attendances recover, the volume benefit to us will be amplified"
On the FY27 wage headwind, from the CFO: "The combined impact of collectors and health professionals in terms of impact from gender under-valuations, about $7 million in FY 2027"
On the margin runway: "the pipeline that we have in place puts us in really good stead for continued margin expansion from 2028 and beyond"
Company page: Australian Clinical Labs (ACL)
Korea Eximbank to lend Glencore $1bn for copper supply
[1:56 pm] South Korea's state lender is tying financing to copper offtake as it moves to secure raw materials for the AI build-out.
Korea Eximbank will lend US$1bn to Glencore International AG, a wholly owned Glencore subsidiary, with proceeds used for general working capital
Glencore has agreed to supply copper to Korean companies over the loan period, with no volume detail provided
Move framed as "preemptive" economic security, with South Korea reliant on copper imports for power grids, data centres and renewables
Source: Bloomberg
Aurizon FY26 earnings call highlights: Re-contracting bites and freight nears breakeven
[1:16 pm] Management framed FY26 as a strong year underwritten by network and coal, while pointing to a coal earnings step-down on right-sized contracts and a pathway to containerised freight breakeven.
On coal recontracting, from the Group Executive Coal: "across the basket of contracts we've renegotiated since July 25, we've not seen a material change in our haulage rate"
On why customers are right-sizing, from the CEO: "you've really got a policy setting and supply side settings driving Australian supply into a higher demand market ... the royalty situation is not conducive to investment"
On the coal earnings mechanism: "the capacity charge that is actually being reduced ... coal earnings reduce even though the haulage task doesn't change"
On the coal transformation program: "we intend to hold cost flat again in nominal terms, which will be the third consecutive year"
On the seaborne coal thesis: "India is expected to be the largest driver of seaborne coking coal demand over the coming decades ... the average age of coal-fired electricity assets in Asia, it is just 15 years, compared with an expected retirement age of 40 years"
On containerised freight breakeven, from the Group Executive Bulk and Containerised Freight: "We need to grow volumes again by 25% in FY 2027 to hit that ... half of that growth to come from new contracted volumes"
Company page: Aurizon Holdings (AZJ)
Copper stocks broadly higher
[1:15 pm] Copper names are trading conservatively higher, with most names up 2-3%, despite copper prices trading within an arms reach of all-time highs.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
AIS | Aeris Resources | 3.7% | $0.42 | -2.3% | -30.0% |
HGO | Hillgrove Resources | 3.2% | $0.07 | 4.8% | 35.4% |
HCH | Hot Chili | 2.5% | $1.67 | -0.3% | 20.1% |
SFR | Sandfire Resources | 2.4% | $21.34 | 0.9% | 18.8% |
29M | 29Metals | 2.3% | $0.32 | -0.9% | -39.8% |
FFM | Firefly Metals | 2.3% | $1.90 | -1.5% | -7.7% |
CYM | Cyprium Metals | 2.0% | $0.50 | 5.3% | -5.5% |
CSC | Capstone Copper Corp | 1.5% | $15.66 | 1.7% | 3.3% |
BHP | BHP Group | 1.3% | $62.16 | -2.0% | 36.5% |
RIO | Rio Tinto | 1.0% | $169.29 | -4.9% | 15.3% |
AR1 | Austral Resources | 0.0% | $0.07 | -5.7% | 15.8% |
CPM | Cooper Metals | 0.0% | $0.06 | -7.7% | 7.1% |
MC2 | Marimaca Copper | -1.6% | $8.05 | -0.2% | -35.6% |
JB Hi-Fi FY26 earnings call highlights: soft July as tech price rises and stock shortages bite
[1:11 pm] Management pointed to memory-driven PC price rises, availability constraints and a value-seeking consumer, while backing a recovery into the key second-quarter promotional events.
On July trading, from the CEO: "July is one month and there are some unique factors in July ... we don't enjoy recording negative comps, and we'll be absolutely driving to get back to positive sales growth"
On PC price rises: "In some brands, that can be in excess of 50% price rises ... the demand for hardware used in the AI data centers is sucking up a lot of the memory supply"
On the consumer response: "customers are making a choice around where they're willing to spend money ... they're trading down by spending a similar amount as they did last year to get a product with less specs"
On entry-level products: "it's a real challenge to get a device in at some of those entry price points ... an entry-level tablet, as an example, which might have had a 25% price increase, there's not really an alternative for that"
On demand versus supply: "It's a combination of supply challenges and probably a bit of a weaker demand environment"
On the second-quarter outlook: "we're still very optimistic for those 2Q promotional events ... I think we're close to getting through the bulk of the availability challenges"
On JB Hi-Fi Australia gross margin: "confident in JB Hi-Fi Australia that we can still target that 22% gross margin"
Company page: JB Hi-Fi (JBH)
BlueScope FY26 earnings call: US strength and cost-out as returns ramp up
[1:10 pm] Management framed FY26 as the pivot from peak investment to shareholder returns, pointing to North American spread strength, a leaner cost base and resilient Australian demand.
On the returns pivot, from the CEO: "Shareholders have been patient through the investment phase, and that patience is now being rewarded"
On North America: "it's hard to come up with a better place to make and sell steel globally ... you've got a very large market. It's a very resilient market ... very strong supply side discipline"
On the North American spread tailwind, from the CFO: "We expect to see further benefit of the significant benchmark spread increase flow into FY 2027 due to the nature of longer pricing lags and other pricing mechanisms that cover around a quarter of North Star's sales book"
On Australian resilience: "The fact that the Australian business is still profitable, it has demonstrated enormous resilience, and it says to me that we have tremendous upside in the business"
On data centre demand: "about 20% of that would be made up by data centres ... data centres is driving a degree of strength into the U.S. demand environment"
On the cost program: "we've exceeded our targeted additional A$150 million cost-out program ... delivering a simpler, leaner BlueScope"
On why a special dividend over a buyback: "It is the most straightforward and clear way of delivering value directly to our shareholders. It is highly visible"
Company page: BlueScope Steel (BSL)
Copper back near record highs
[1:07 pm] Copper prices are up 1.9% on Monday to US$6.81/lb, a record close if prices can settle around these levels.
Spot traded as much as $478 a ton above the three-month contract, the widest backwardation since the 2021 squeeze
LME-tracked inventories down to just above 200,000 tons, the smallest since February
Recent supply setbacks add to tightness, with Codelco abandoning its growth target, BHP lowering its copper guidance and Antofagasta cutting output guidance
IMDEX flags record start to FY27 as South America shapes up as growth engine
[12:15 pm] At the earnings call, management pointed to accelerating momentum out of FY26, structural demand drivers and a deliberate year of investment ahead.
On momentum, from the CEO: "July was a record revenue month for Imdex, surpassing June, which in itself had been a record revenue month for Imdex"
On the regional shift: "the South American region, which would currently be the second-largest exploration region in the world by AUD dollar spend, is probably likely to be the largest region, by AUD dollar spend within the next 12-24 months"
On the structural driver: "the underlying supply challenge remains structural and firmly in place. Reserves continue to decline, discovery rates remain challenged, and ore bodies are getting deeper and more complex"
On the softer growth language: "the market wants to spend 15%, but in the last year, they only really spent 8% or 9% ... what will actually land in the ground in that 12-month window will likely be a little bit less"
On FY27 margins, from the CFO: "FY27 is going to be a year of investment for us, and that is going to set us up really well for margin accretion into the future"
On cost pressure: "I do think the ripple effects from Hormuz and some of these other areas are still yet to roll through the industry more globally, including Australia"
Company page: IMDEX (IMD)
Growthpoint leans on leasing strength and supply constraints as rates bite
[12:15 pm] Management framed FY26 as disciplined execution against a higher-for-longer backdrop, pointing to record leasing, structural supply barriers and insulation from AI-driven office risk.
On the supply backdrop: "The economic rents required to justify new development, particularly in the office sector, remain well above in-place rents, which is acting as a meaningful barrier to the creation of new supply"
On stock withdrawal: "we are seeing existing stock withdrawn for alternative uses, particularly living and data center conversions across a number of office markets"
On AI exposure: "around 85% of our income is derived from head office and government or public service tenancies, which we believe provides insulation from major AI disruption"
On tenant demand from AI: "63% of our tenants expect to require the same or more space as a result of AI"
On leasing momentum, from the Head of Property: "88% of the leases completed were either the same amount of space or more ... We only had three tenants reducing in size across the renewals"
Company page: Growthpoint Properties Australia (GOZ)
NAB tumbles on Q3 trading update, banks trade broadly lower
[12:10 pm] We missed the NAB Q3 this morning, which missed on most key metrics.
The below ests refer to Morgan Stanley's 3-Aug forecasts.
Cash earnings of $1.83bn vs $1.87bn ests (2% miss), up 2% on the 1H26 quarterly average ex the large notable item
NIM of 1.79% vs 1.83% ests (4bps miss), or up 2bps ex markets and treasury
Credit impairment charges of $299m vs $250m ests, heavier than expected on higher collective provision charges
CET1 ratio of 11.93% vs 11.93% ests (in line), up from 11.65% at March
Home loan applications down 15% vs. the second quarter, with Australian home lending in line with system ex the Advantedge run-off
Australian business lending up 2%, including 4% growth from Business & Private Banking
On the backdrop: "Business credit growth has remained robust at this stage, but the Australian home lending market softened in 3Q26 with our applications down 15% compared with 2Q26"
NAB is down 4.8% at the time of writing, while the broader S&P/ASX 200 Financials Index is down 1.1% (now down six of the last seven sessions).
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
NAB | National Australia Bank | -4.8% | $39.39 | -5.9% | -6.8% |
ANZ | ANZ Group | -2.4% | $37.97 | 1.6% | 4.2% |
JDO | Judo Capital | -1.4% | $0.91 | -10.6% | -48.8% |
MQG | Macquarie Group | -0.7% | $260.12 | -1.1% | 28.1% |
WBC | Westpac | -0.3% | $35.28 | -3.6% | -8.4% |
BEN | Bendigo & Adelaide Bank | -0.1% | $11.17 | -1.5% | 5.5% |
BOQ | Bank Of Queensland | -0.1% | $6.46 | -2.9% | -1.6% |
CBA | Commonwealth Bank | 0.3% | $167.63 | -4.8% | 4.4% |
Discretionary stocks tumble on JB Hi-Fi read through
[11:58 am] JB Hi-Fi tumbled 11.5% on its FY26 result, largely driven by a sharp deceleration in Q4 sales and negative FY27 trading update. The stock is on track to have its worst one-day move since the 7 April 2025 tariff meltdown.

JB Hi-Fi Australia sales growth by quarter (Source: JB Hi-Fi FY26 results presentation)
The broader discretionary index is down 2.5%, with notable declines from Super Retail (-6.0%), Harvey Norman (-4.5%) and Wesfarmers (-3.1%).
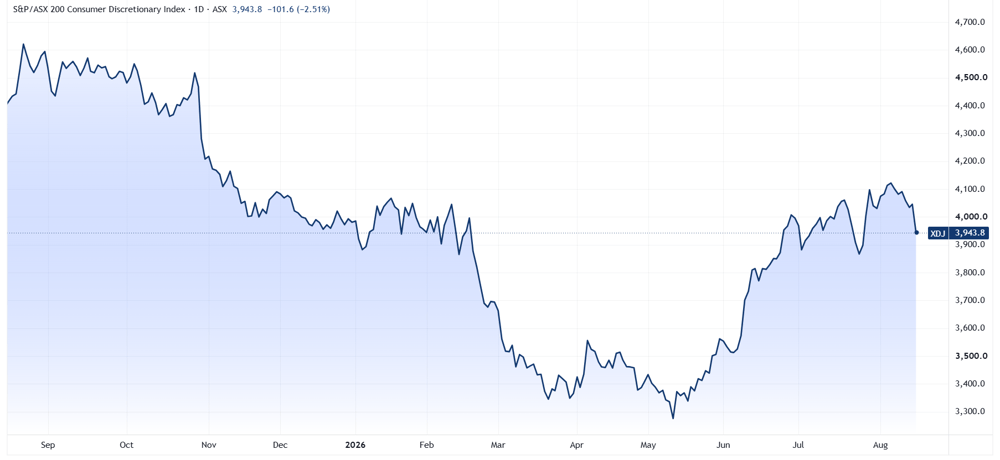
S&P/ASX 200 Discretionary Index (Source: TradingView)
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
JBH | JB Hi-Fi | -11.5% | $72.35 | -14.0% | -24.8% |
SUL | Super Retail Group | -6.0% | $12.47 | -8.3% | -22.1% |
HVN | Harvey Norman | -4.5% | $4.61 | -8.1% | -33.9% |
HLO | Helloworld Travel | -4.1% | $1.51 | -3.5% | -20.6% |
WES | Wesfarmers | -3.1% | $85.92 | -3.9% | 6.0% |
PMV | Premier Investments | -2.6% | $12.20 | -9.0% | -11.9% |
APE | Eagers Automotive | -2.4% | $22.88 | -4.9% | -6.4% |
TAH | Tabcorp | -2.2% | $0.90 | 2.9% | -8.2% |
GYG | Guzman Y Gomez | -1.9% | $24.12 | -2.1% | 10.4% |
FLT | Flight Centre Travel Group | -1.8% | $12.89 | -4.9% | -14.0% |
WEB | Web Travel Group | -1.7% | $3.45 | -0.3% | -27.8% |
ARB | Arb Corporation | -1.3% | $19.25 | -6.1% | -39.4% |
LOV | Lovisa | -1.3% | $24.40 | -9.6% | -16.8% |
DMP | Domino's Pizza | -1.1% | $19.20 | -1.0% | -8.7% |
QAN | Qantas Airways | -1.0% | $9.91 | -6.1% | -4.8% |
VGN | Virgin Australia | -0.9% | $2.71 | -4.4% | -22.9% |
NCK | Nick Scali | -0.9% | $16.33 | -5.3% | -30.5% |
TLC | Lottery Corporation | -0.5% | $5.36 | -1.0% | 4.0% |
BRG | Breville Group | -0.2% | $33.48 | -3.0% | 13.5% |
CTD | Corporate Travel Management | -0.1% | $16.07 | 0.0% | 0.0% |
ALL | Aristocrat Leisure | 0.0% | $64.38 | -1.1% | 11.5% |
CKF | Collins Foods | 0.2% | $8.18 | 0.4% | -22.8% |
LNW | Light & Wonder | 0.9% | $137.04 | 11.4% | -11.6% |
Analysts turn cautious on BHP ahead of full-year results
[11:47 am] Buy ratings on the miner have fallen to a record low heading into Tuesday's FY26 numbers, with copper volume concerns weighing on sentiment.
Just four of the 30 brokers tracked by Bloomberg rate BHP a buy, with CLSA, Citigroup and Morgans among those dropping bullish calls over the past year
Copper guidance downgraded last month, with output expected to fall to as low as 1.65 million tons in FY27 on declining South American grades
Concern that shrinking volumes leave BHP unable to fully capture record copper prices
Shares trade at around 17 times forward earnings versus a five-year average of about 11, having risen 35% this year
Citi prefers Glencore for copper exposure, holding a neutral relative rating since at least October
Source: Bloomberg
ASX 200 slips for a fourth day
[11:01 am] The S&P/ASX 200 is down 0.33%, on track to record a fourth-straight day of declines. The index has now fallen 2.0% since the 6 August record high, though recent weakness has been relatively results-driven.
Materials (+0.85%) bouncing after a three-day skid, buoyed by strength across lithium, gold, rare earths and copper equities
Financials (-1.0%) rocked by another downbeat quarterly. This time, from NAB (-3.9%), where its Q3 net interest margins fell more-than-expected, down 2 bps to 1.79%
Discretionary (-2.2%) weighed by JB Hi-Fi (-13.7%), where its FY26 result was relatively in-line with market expectations, but flagged sales deceleration into Q4 and negative FY27 trading update. This is also driving names like Wesfarmers (-2.9%), Harvey Norman (-5.1%) and Super Retail Group (-5.8%) lower
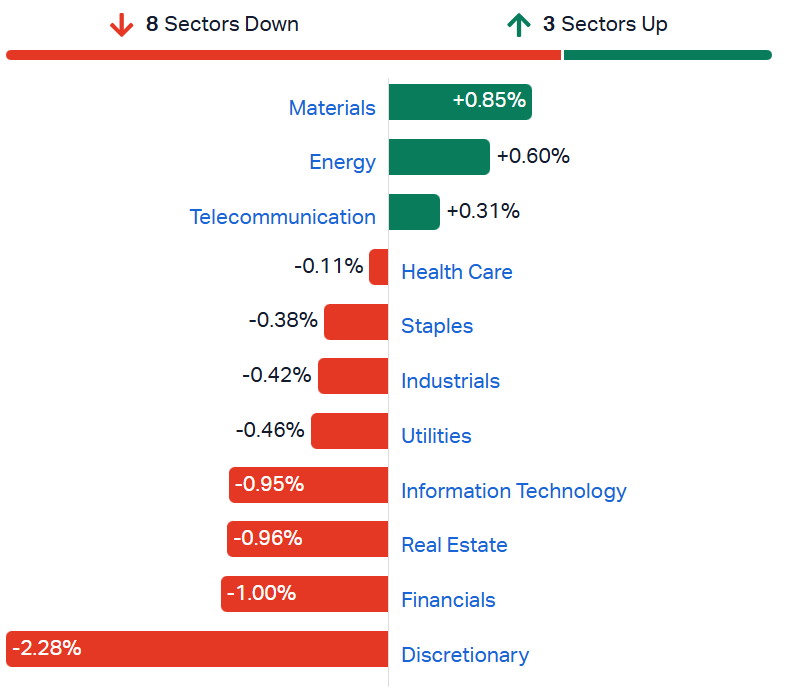
S&P/ASX 200 sectors (Source: Market Index)
Top ASX 200 gainers and losers
[10:27 am] Rare earth, lithium, gold and uranium stocks bounce, while JB Hi-Fi, Aurizon and Iress tumble on FY26 results.
Ticker | Company | % Chg | Price |
|---|---|---|---|
IPX | Iperionx | 5.78% | $3.48 |
LYC | Lynas Rare Earths | 5.75% | $17.30 |
PRN | Perenti | 4.63% | $2.38 |
BGL | Bellevue Gold | 4.50% | $1.56 |
SDF | Steadfast Group | 4.32% | $5.55 |
LTR | Liontown | 4.08% | $1.33 |
PLS | PLS Group | 4.00% | $5.07 |
IMD | Imdex | 3.90% | $4.00 |
PDN | Paladin Energy | 3.85% | $10.52 |
OBM | Ora Banda Mining | 3.82% | $1.36 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
JBH | JB Hi-Fi | -13.26% | $70.88 |
AZJ | Aurizon | -11.06% | $3.70 |
IRE | Iress | -8.85% | $7.21 |
SUL | Super Retail Group | -5.81% | $12.49 |
HVN | Harvey Norman | -5.29% | $4.57 |
SUN | Suncorp Group | -5.13% | $18.69 |
NAB | National Australia Bank | -4.45% | $39.53 |
WTC | Wisetech Global | -3.33% | $41.94 |
SGP | Stockland | -3.25% | $4.17 |
JDO | Judo Capital | -3.24% | $0.90 |
Australian Clinical Labs lifts earnings on efficiency as revenue slips
[9:52 am] Margin gains and cost discipline drove profit growth despite subdued pathology volumes, Medicare cuts and inflation.
Revenue down 0.7% on lower market growth, Medicare funding cuts to B12 and urine tests, and collection centre optimisation
Underlying EBIT up 1.7% with 20bps of margin expansion to 9.4%
Underlying NPAT up 4.3%, driven by earnings improvement, cost management and lower depreciation
Underlying EPS up 8.5% to 18.3c, helped by the buyback
Final fully franked dividend of 9.25 cps, at a 69% payout of underlying NPAT, record date 3 September and payable 23 September
$47.1m returned to shareholders via dividends and 9.3m shares bought back
FY27 revenue guided to $745-765m and underlying EBIT to $67-73m, implying a 9.0-9.5% margin, but excluding the final stage of gender undervaluation for collectors from 1 January 2027
On the backdrop: "Amid subdued GP attendance volumes, Medicare fee changes and persistent inflationary pressure, we maintained a clear focus on our strategy, improving margins year on year to 9.4%"
Company page: Australian Clinical Labs (ACL)
GR Engineering wins $275m EPC contract for Develop's Yitirrti plant
[9:50 am] The contractor will design and build the processing plant at the Pilbara copper-zinc-silver project, keeping it on track for first concentrate in the June quarter of 2028.
Awarded the $275m EPC contract to build the Yitirrti (formerly Sulphur Springs) processing plant, with nameplate capacity of 1.5Mtpa producing separate copper-silver and zinc concentrates
Total Yitirrti capital cost estimated at $450m, including the plant
Project forecast to deliver a 37% internal rate of return and a 23-month payback
Funded through Develop's US$400m (about $570m) Trafigura debt facility, $123m cash on hand at 30 June and cashflow from Woodlawn and Pioneer Dome
Trafigura has committed to offtake covering copper and zinc concentrates, with construction and underground development already well advanced
Company pages: GR Engineering Services (GNG), Develop Global (DVP)
Iress lifts first-half earnings but misses on revenue and profit
[9:35 am] Cost discipline drove sharp margin expansion and a higher dividend, though headline figures came in below expectations.
Continuing revenue up 2.5% in constant currency to $250.0m vs $257.5m ests (3% miss)
Continuing Cash EBITDA up 47.1% in constant currency to $61.1m, unclear if comparable to $72.1m ests (15% miss)
Margin up more than 740bps to 24.5%
UPAT up 18.4% to $38.8m vs $41.4m ests (6% miss)
Statutory NPAT up 85.0% to $32.0m vs $36.7m ests (13% miss)
Fully franked interim dividend of 14.0 cps, up 27.3%, vs 14.0 cps ests (in line)
FY26 guidance for reported revenue of $499-505m and Cash EBITDA of $119-124m, with constant-currency Cash EBITDA growth of 21-26%
FY26 revenue growth guided to 1-2% in constant currency vs 3.4% ests, softer on lower non-recurring revenue
FY26 constant-currency Cash EBITDA growth guided to 21-26% vs 13.2% ests, well ahead
FY26 reported Cash EBITDA guided to $119-124m vs $124.8m ests (3% miss at midpoint)
Company page: Iress (IRE)
L1 Group posts 97% underlying profit growth on strong performance and merger synergies
[9:30 am] The first result since the Platinum merger was lifted by exceptional fund performance and a large one-off performance fee, with integration running ahead of schedule.
Total revenue up 49% to $385.9m
Underlying NPAT up 97% to $188.8m, including a one-off $79.3m performance fee from the closure of the unlisted L1 Wholesale Gold Fund
Underlying EBITDA up 102% to $287.4m, with operating expenses down about 15% driving strong operating leverage
FUM up 17% to $19.1bn, with net flows improving in every quarter and L1 Capital affiliates now managing about 73% of group FUM, up from 55% at merger
Merger synergies of $31.7m realised, with the target lifted from $35m to $43m and a further about $11m expected in FY27
Final dividend of 2.0 cps fully franked, bringing FY26 total to 3.0 cps
Debt-free balance sheet with $635m in cash and seed investments
Flagship performance included the L1 Long Short Strategy up 45.4%, Global Long Short up 57.8% and Gold Strategy up 83.2%
Company page: L1 Group (L1G)
oOh!media flags stronger second half as Q3 paces up double digits
[9:28 am] Soft billboard demand and the loss of Auckland Transport weighed on the first half, but Australian momentum is accelerating into a period dominated by the I Squared takeover.
Group revenue of $340.9m, adjusted underlying EBITDA of $48.1m and adjusted underlying gross margin of 37.5%
Billboards revenue down 2% to $117.5m as brand-led demand weakened through Q2
Street & Rail up 3% to $111.6m, with Australia up 18% offset by a 57% New Zealand decline after the Auckland Transport exit
Retail up 1% to $59.2m, the first growth in six halves, with Airports up 5% to $33.6m
Operational Excellence program and REO exit delivering $12m in annualised savings, with a further $1-2m run rate identified
Fully franked 2 cps interim dividend declared as part of the I Squared scheme, net debt of $129.3m and gearing of 1.0x
Q3 pacing up 14% in Australia, with more than 100% of last year's Q3 closing revenue already booked
I Squared scheme announced 10 August at $1.70 per share, including the 2.00c fully franked dividend
On the category: "Out of Home continues to be the fastest growing media format, reaching a record 16.9% of total agency media spend"
Company page: oOh!media (OML)
JB Hi-Fi hits record FY26 sales, lifts dividend 22.5% as brands hold up
[9:26 am] Resilient demand across the group drove record turnover and a sharply higher payout, though July trading pointed to softer momentum in the core Australian business.
Total sales up 4.8% to $11.06bn vs $11.12bn ests (in line)
EBIT up 3.8% to $734.4m vs $734.9m ests (in line)
NPAT up 2.9% to $489.9m vs $492m ests (in line)
EPS up 2.9% to 448.1 cents vs 448.4 cents ests (in line)
Final dividend of 127.0 cps fully franked, up 21.0%, taking full-year ordinary dividend to 337.0 cps, up 22.5%, at 75% of NPAT
July trading softened, with JB Hi-Fi Australia total sales down 0.5% and The Good Guys down 1.7%, on supplier price rises and tech stock shortages
Company page: JB Hi-Fi (JBH)
Audinate delivers 15% US dollar revenue growth as Dante spans audio, video and control
[9:20 am] Platform investment in Iris and Dante Director pushed the group to an underlying EBITDA loss, though the loss came in narrower than ests as a completed restructure sets up FY27.
The below ests refer to Morgan Stanley forecasts from May 2026, most of which were in A$. We have converted this to USD at today's exchange rate of 71 cents.
Revenue up 14.9% to US$46.0m, or $64.8m at 0.71 vs $66.7m ests (3% miss), at the upper end of market guidance
Gross profit up 14.7% to US$37.7m, or $53.1m at 0.71 vs $54.9m ests (3% miss), with gross margin of 82.0% versus 82.1% in FY25
Underlying EBITDA a loss of $3.6m vs a $5.7m ests loss, a narrower loss than expected, against a $0.7m profit in FY25
Dante ecosystem now over 8 million devices shipped across 542 OEM partners, with 137 design wins secured
FY27 outlook for US dollar gross profit growth in line with or slightly ahead of FY26, margins around 82% and A$ operating costs held flat, supporting improved operating profit
Implies ~US$43.2m in FY27 gross profit or ~A$60.9m vs. A$62.7m ests (~3% miss)
On the AI question: "since Dante moves audio and video signals onto IP networks, Dante APIs and platform services create a natural foundation for AI and workflow automation"
Company page: Audinate Group (AD8)
Aurizon's FY26 dividend jumps 46% on record Bulk result
[9:14 am] Higher regulated revenue and a record Bulk performance drove earnings and cash generation higher, funding a sharply increased payout alongside a completed buy-back.
Revenue up 6% to $4.19bn vs $4.16bn ests (in line)
EBITDA up 9% to $1.72bn vs $1.72bn ests (in line)
Underlying NPAT up 24% to $433m vs $429m ests (1% beat)
Statutory NPAT up 19% to $362m
Full-year DPS of 23.0 cps, up 46%, vs 22.5 cps ests (2% beat), final 10.5 cps 90% franked
FY27 EBITDA guided to $1,725-1,775m vs $1,797m ests (3% miss at midpoint), with Coal lower on reduced volumes and yield
Company page: Aurizon Holdings (AZJ)
Aurizon recontracts major BMA coal haulage deal in Queensland
[9:14 am] The rail operator has renewed its long-standing partnership with BHP Mitsubishi Alliance for metallurgical coal haulage in the Bowen Basin, replacing its 2015 contract.
New performance-based contract for up to 37 million tonnes per annum, effective 1 July 2028
Term of up to 12 years subject to performance and extension arrangements, potentially running to 2040
Covers BMA's Goonyella Riverside, Broadmeadow, Peak Downs, Saraji and Caval Ridge met coal mines
BMA represents close to a quarter of the coal tonnes Aurizon carries in Queensland
Takes total coal haulage recontracted since July 2025 to more than 60 million tonnes annually, covering all customer contracts tendered over the period
Company page: Aurizon Holdings (AZJ)
IMDEX posts record FY26 as margins expand and market share gains continue
[9:11 am] Revenue growth outpaced a soft exploration market on further share gains, with earnings leverage lifting normalised margins.
Revenue up 21% to $520m vs $519m ests (in line)
Normalised EBITDA up 29% to $163m vs $159.8m ests (2% beat), margin expanding to 31%
Reported EBITDA up 38% to $179m and reported NPAT up 44% to $79m
Normalised NPAT up 37% to $59m vs $58.3m ests (1% beat)
Full-year dividend of 3.44 cps, fully franked, with 1.75 cps final at a 30% payout ratio, in line with ests
Share of wallet a record $2.40 per $100 of exploration spend, up from $2.20 in FY25
On the outlook: "IMDEX enters FY27 with more growth levers available than at any time in its history"
Company page: IMDEX (IMD)
GWA lifts profit and dividend on volume growth across all markets
[9:11 am] Operational discipline drove earnings and margin higher despite mixed conditions, delivering a third straight year of group volume growth.
Revenue up 0.9% to $422.3m
Normalised EBIT up 2.5% to $78.2m, with margin up 0.3ppts to 18.5%
Normalised NPAT up 4.9% to $48.8m
Statutory NPAT up 10.6% to $48.0m
Fully franked final dividend of 8.5cps, taking the full-year payout to 16.5cps, up 6.5%
FY27 cash conversion expected above the 80-85% target range on a proactive inventory pull-forward
Company page: GWA Group (GWA)
BlueScope FY26 earnings surge
[9:05 am] Stronger US steel spreads and a record Southeast Asia result drove a materially higher full-year outcome, with first-half FY2027 guidance landing comfortably ahead of consensus.
Underlying EBIT of $1.27bn vs. $1.264bn UBS ests (0.5% beat), on stronger US spreads and record Southeast Asia performance
Reported NPAT up 857% to $802m
Underlying NPAT of $851.2m vs. $849m UBS ests (0.25% beat)
Final ordinary dividend of 65 cps plus 70 cps special (both unfranked), unclear if comparable to UBS ests of 165 cps
1H27 underlying EBIT guided to $860-960m vs $923m ests (1.4% miss at the midpoint)
Company page: BlueScope Steel (BSL)
Macmahon sells down Homeground village in $20bn Gladstone infrastructure play
[9:00 am] Macmahon has agreed to a partial sale of its Gladstone workforce accommodation asset alongside a co-operation deal tied to a major Central Queensland development program.
Selling up to 50% of the Homeground village to Allcap Securities based on the asset's $52m book value, starting with a 20% interest and an option for a further 30% by December 2029
Retains 80% initially and ongoing exposure to Homeground's performance, having long viewed it as non-core
Allcap to direct accommodation demand within 70km of Gladstone to Homeground, which has 1,392 existing rooms
Deal anchored to Project Velocity, an approximately $20bn integrated freight and logistics program including a new container terminal, inland port, about 580km of rail and BESS energy infrastructure
On the rationale: "an opportunity to progressively realise value from Homeground, which we have consistently regarded as a non-core asset, while retaining meaningful exposure to its future performance"
Company page: Macmahon Holdings (MAH)
GPT lifts management earnings as portfolio NPI growth stays strong
[8:59 am] Like-for-like income growth across all three sectors and a rising funds-management contribution drove the first half, with full-year guidance reaffirmed.
FFO of $338.8m or 17.7cps,
1H26 distribution of 12.25cps vs 12.3c ests (in line)
Investment portfolio like-for-like NPI growth of 5.8%, with office up 8.0%, retail up 4.6% and logistics up 4.0%
Investment portfolio occupancy of 97.6%, or 98.2% excluding recently acquired Grosvenor Place
Assets under management up 4.6% since December to $41.6bn, with gross transactions of about $1.7bn
Net tangible assets of $5.61 per security, net gearing of 31.5% and liquidity of $1.0bn
FY26 guidance reaffirmed at FFO of about 35.4cps (about 4% growth, 5.7% ex-trading profits) and distribution of 24.5cps, in line with ests
On strategy: "the growing contribution from management earnings reflects our success in attracting investors to deploy alongside us"
Company page: The GPT Group (GPT)
a2 Milk FY27 guidance points below consensus on softer margins
[8:57 am] The infant formula recovery is a first-half drag, leaving group earnings materially skewed to the second half and the margin guide short of where the market sits.
FY27 revenue guided to mid single digit growth, implying roughly $2,035-2,075m vs $2,133m ests (around 3-5% below)
EBITDA margin guided to approximately 15%, implying EBITDA of roughly $305-311m vs $341m ests (around 9-11% below)
1H27 revenue expected broadly in line with 1H26 and 1H27 EBITDA margin materially down on 1H26, with revenue and earnings weighted to 2H27
IMF sales expected broadly similar to FY26 as China label gradually recovers and English label offtake improves through 1H27 on higher marketing spend
NZX-listed A2 shares are down 9.9% this morning to NZ$7.41.
Company page: The a2 Milk Company (A2M)
a2 Milk delivers double-digit revenue growth despite 4Q China supply hit
[8:56 am] Every market and category grew in FY26, though a fourth-quarter supply chain disruption dented China label infant formula and weighed on second-half earnings.
Group revenue up 12.4% to $1,974.9m vs $1,974m ests (in line), with USA up 28.6%, China & Other Asia up 11.2% and ANZ up 10.2%
EBITDA of $284.4m vs $285m ests (in line), with underlying EBITDA up 5.4%
NPAT of $207.5m vs $204m ests (2% beat), underlying NPAT up 7.0%
Underlying EPS up 6.8% to 32.5 cents
Total FY26 dividend lifted to 21.0 cents from 20.0 cents, unimputed and fully franked, plus a $300m special dividend, at a ~74% payout ratio
Infant formula grew 5% in a flat China market, Other Nutritionals up 42% and Liquid Milk up 22% on ANZ and USA share gains
FY27 outlook for mid single digit revenue growth and around 15% EBITDA margin
On the China setback: "the key contributing factors have been resolved, and we are focused on executing our recovery plan"
Company page: The a2 Milk Company (A2M)
US readies 'economic isolation' plan for Iran as Hormuz attacks mount
[8:53 am] Treasury Secretary Scott Bessent has flagged unprecedented economic measures against Tehran, keeping oil-market risk elevated as ship attacks continue and peace talks stall.
Bessent promised measures never seen "in the history of economic isolation," as part of a "one-two punch" alongside the continued naval blockade of Iran's ports
Covert oil shuttling through Hormuz is running above 4 million barrels a day, with pipeline workarounds and stockpile releases helping cap prices despite the war
Meaningful new measures likely require secondary sanctions on buyers of Iranian oil such as China, which buys more than 90% of Iran's exports and would risk Beijing retaliation and fresh energy-price uncertainty
Options canvassed include hitting Chinese banks financing the trade, sanctioning UAE exchange houses, secondary sanctions on trading partners, seizing overseas assets and targeting the shadow fleet
S&P 500 earnings blow past expectations in 'outlier' season
[8:53 am] Second-quarter profit growth is running well ahead of forecasts, lifting strategist targets for a market already at record highs.
S&P 500 earnings up 31% in Q2 year-on-year, the best growth outside recession recoveries since 1992 and ahead of the 23% projected
Net income margins approaching 16%, up from a prior ceiling around 14%, driven by tech and AI productivity gains
Full-year profit growth estimates lifted to 27%, from 15% at the start of 2026
Average year-end target raised to 7,894 points, roughly 1% above current levels
Index trading just below 22 times forward earnings, down from around 26 times at the start of the year
Around three-quarters of 1,500 reporters beat on both EPS and sales, with mid- and small-cap beat rates near record highs
Source: Bloomberg
Copper squeeze deepens as LME spread hits highest since 2021
[8:50 am] Spot copper is trading well above later-dated futures as LME stockpiles keep draining.
August contract hit a premium as high as $370 over September futures, the widest one-month spread since the 2021 squeeze
Cash-to-three-month spread reached $434 a ton, also the highest since 2021
LME stockpiles fell for a 42nd day to 204,975 tons, with nearly half already earmarked for withdrawal
LME introduced emergency measures to contain the spot rally
Three-month contract traded above $14,100 a ton, up nearly 14% for the year, with cash near a record $14,500
Squeeze fuelled by shipments to the US ahead of potential refined copper tariffs and tight Chinese feedstock
Hedge funds more than halve yen short since joint intervention
[8:49 am] Leveraged funds keep unwinding bearish yen bets after the US-Japan action, though the currency has clawed back most of its gains.
Leveraged fund yen shorts down 6.5% to 59,526 contracts in the week to 11 August
Funds have more than halved their yen short position since the coordinated intervention
Yen weakened about 1% this week to 159.35, erasing much of the official-action gains
Bullish pound bets built to the most since February, NZD shorts to the most since 2006
Source: Bloomberg
'FOMO insurance' drives options buying as record rally rolls on
[8:48 am] With the S&P 500 at fresh highs, investors are chasing upside calls rather than hedging the downside.
Demand for upside calls has outstripped demand for flat-market options for at least 170 S&P 500 stocks, the most since 2016, per Citadel Securities
Institutions buying bullish calls as "FOMO insurance" to capture upside without committing full capital
S&P 500 up around 23% since late March, closing at another record on Thursday
VIX at its lowest since January, signalling a cheap time to hedge
Source: Bloomberg
Berkshire lifts Delta and Alphabet stakes as Abel draws on cash pile
[8:48 am] Greg Abel's second full quarter as CEO saw back-to-back deals and fresh equity buying, trimming Berkshire's record cash hoard.
Added 17.5 million Delta shares, lifting the stake to $5.37bn at end-June
Added 48.1 million Alphabet shares, making it the third-biggest holding at $37.8bn
Cash fell to $365.5bn at midyear from a record $397bn at end-March
Spent $6.8bn on homebuilder Taylor Morrison and handed $10bn to Alphabet to support AI investments
Repurchased about $4.5bn of own stock and added a net $20bn of other equities
Source: Bloomberg
Good morning!
[8:36 am] ASX 200 futures are down 33 pts (-0.36%). Here's what happened overnight:
US benchmarks mostly eased from Thursday's record close after soft retail sales and consumer sentiment data, though the S&P 500 still notched a third consecutive weekly advance, its longest run since May
S&P 500 (-0.17%), Nasdaq (-0.28%), Dow (-0.20%) and Russell 2000 (+0.51%)
Equal-weight S&P 500 (+0.02%) eked out a forth straight all-time high
Oil pushed higher into the weekend after Washington threatened unprecedented economic measures against Iran and signalled the naval blockade of Iranian ports could run indefinitely
Broadcom led a wobble in AI credit after Bank of America flagged the scale of debt sitting behind the off-balance-sheet chip financing vehicle it built with Apollo and Blackstone