In a nutshell:
Major US benchmarks up for a third straight session, with stocks holding up amid a catalyst rich session featuring the Fed and mega cap tech earnings
Fed held rates in a 10-2 vote with two officials backing a hike, while Warsh announced fewer rate-setting meetings from 2027 and traders priced a December move
Microsoft rallied 4.5% after hours as Azure growth accelerated to 48%, while Alphabet tanked 9% as an earnings miss overshadowed Google Cloud revenue more than doubling to US$30.71bn
Brent crude near US$115 a barrel after a report the US told Gulf allies to prepare for a short, intense Iran campaign after next week’s midterms
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,744 | +0.28% |
Dow Jones | 52,475 | +0.19% |
NASDAQ Comp | 26,550 | +0.27% |
Russell 2000 | 2,831 | +0.41% |
Global Indices | ||
 S&P/TSX | 36,265 | +0.26% |
 Shanghai Composite | 3,681 | +0.91% |
 DAX | 25,704 | +0.44% |
 Hang Seng | 23,095 | +0.23% |
 Nifty 50 | 73,246 | -0.49% |
 Nikkei 225 | 63,954 | +1.08% |
 FTSE 100 | 10,695 | +0.07% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,068.91 | +0.21% |
 Copper | 6.65 | +0.37% |
 WTI Oil | 102.01 | +2.12% |
Currency | ||
 AUD/USD | 0.7052 | +0.38% |
Cryptocurrency | ||
 Bitcoin (USD) | 81,205 | +0.66% |
 Ethereum (AUD) | 3,339 | +0.63% |
Miscellaneous | ||
US 10 Yr T-bond | 5.045 | +1.04% |
VIX | 16.91 | -3.48% |
US Sectors
Sector | % Chg |
|---|---|
| Information Technology | +0.48% |
| Energy | +0.41% |
| Financials | +0.36% |
| Communication Services | +0.35% |
| Industrials | +0.28% |
| Health Care | +0.25% |
Sector | % Chg |
|---|---|
| Materials | +0.16% |
| Consumer Discretionary | +0.02% |
| Consumer Staples | -0.38% |
| Real Estate | -0.65% |
| Utilities | -0.88% |
S&P 500 Session Chart
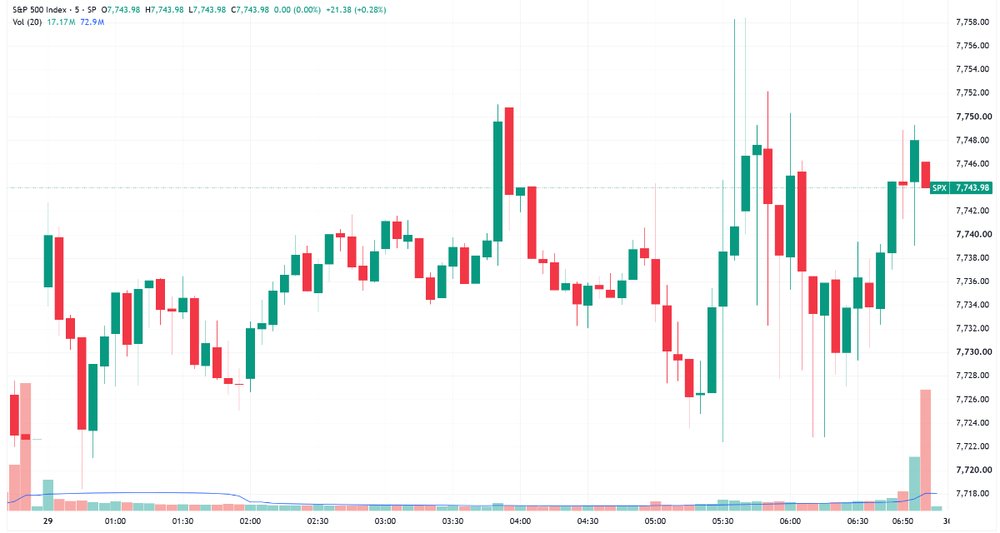
S&P 500 fluctuated around Fed decision and finished close to best levels (Source: TradingView)
Overnight Markets
Major US benchmarks mostly higher in a choppy session, with the S&P 500 fluctuating around the Fed decision as a chipmaker gauge rose for a fourth straight day ahead of Microsoft and Alphabet results
US 10-year Treasury yield rose about 2bps to 5.02% as investors digested the Fed’s decision to hold rates steady at its October meeting, odds for December hike rose to 85% from 78% the day before
Brent crude around $113 a barrel as traders weighed whether the US will resume strikes on Iran after next week’s midterms and a close Israeli election count (BBG)
UK gilts and stocks rose after Chancellor John Healey’s first budget stuck to fiscal discipline pledges, with banks and gambling stocks gaining on relief that sector taxes were less punitive than feared (BBG)
Insurers, pension funds and direct lenders are lifting exposure to data centre debt just as public credit markets show early signs of strain absorbing AI-linked issuance (BBG)
Equiti Group senior market analyst Nadia El Bilassy said AI demand has not paused, with investors’ main worry shifting from AI valuations to debt-funded financing as US borrowing climbs (RT)
World Bank tipped commodity prices to rise 23% in 2026, with energy up 32% and metals up 25% to a record as aluminium, copper and tin set new highs (RT)
Stocks
Microsoft Q1 FY27: revenue up 19% to $92.28bn, Azure up 48% to $33.17bn, EPS $4.89 beat ests by ~3%, Agents and Infra revenue of $76.8bn topped ests of $75.6bn in its first quarter under the new segment structure, shares up more than 4% after hours (YF)
Alphabet Q3: revenue $127.57bn missed ests of $128.2bn, EPS $2.12 missed ests by ~30%, Google Cloud revenue of $30.71bn beat the $29bn to $30bn ests range, operating income fell more than $2.5bn short of ests despite capex coming in lower at $51.4bn, shares down 9% after hours (TS)
Oracle shares jumped 10% after the company targeted fiscal 2030 revenue of at least $225bn, implying 35% average annual growth, and capped additional fundraising through fiscal 2030 at $20bn, a boost for a stock that had fallen 33% this year (CNBC)
Unilever Q3: underlying sales up 5.2% on higher volumes across Beauty & Wellbeing, Personal Care and Home Care, raised full-year underlying volume growth outlook to at least 3%, shares came under pressure (YF)
Central Banks & Fed Decision
Fed held rates at 3.75% to 4% in a 10-2 vote, with Governor Lisa Cook and Cleveland Fed President Beth Hammack favouring a quarter-point hike, while Warsh said politics played no role (YF)
Fed statement said gathering more information will help set the appropriate policy stance, stopping short of a clear signal on whether officials will hike again in December (BBG)
Warsh said one 2027 FOMC meeting will focus solely on strategy with no rate vote or statement, and expects two strategy meetings and six policy-setting meetings in 2028 (CNBC)
Bond traders priced more than a 90% chance of a December hike, while two-year Treasury yields fell as much as 4bps to 4.7% after Warsh flagged fewer rate-setting meetings (BBG)
Warsh pushed back on the view that the AI investment boom is insulated from higher rates, pointing to widening credit spreads and more selective investors (Axios)
Bank of Canada raised its policy rate 25bps to 2.5% in its first hike since July 2023, with Governor Tiff Macklem citing a period of global upheaval and a worsening inflation outlook (BNN)
None of the economists in a Bloomberg survey expect the BoJ to hike at its meeting ending Friday, with about 83% tipping the next increase in December (BBG)
Geopolitics
US military advised ships with no need to transit the Strait of Hormuz and Gulf of Oman to stay clear, as Iranian attacks on vessels hit a wartime high of almost 30 in October (BBG)
US officials told several Gulf Arab states to prepare for a short but intense military campaign against Iran after the November 3 midterm elections, the WSJ reported (CNBC)
Qatar presented Iran with a draft deal to end the eight-month war, with Tehran’s response expected by week’s end, though a senior Iranian official dismissed it as unacceptable ideas rather than an offer (RT)
Tariffs
Canadian official said trade talks with the US have made limited progress, with negotiations focused on Section 232 tariffs including up to 50% on Canadian steel and 25% on autos (RT)
US banned imports from three Chinese genomics companies including BGI Genomics and MGI Tech over alleged links to forced labour in Xinjiang, imposed during a fragile US-China trade truce (RT)
Economy
US goods trade deficit widened 2.1% to $134.9bn in September, the largest since March 2025 and above ests of $130.2bn, as AI-related capital goods demand pushed imports to a record (RT)
Australian CPI rose 4.3% year-on-year in September vs ests of 4.2%, while the quarterly trimmed mean rose 3.7% year-on-year vs ests of 3.6%, lifting bets on a fifth RBA hike at next week’s meeting (BBG)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Uranium | 36.55 | +1.92% |
| Gold Miners | 83.95 | +0.91% |
| Silver Miners | 77.53 | +0.70% |
| Strategic Metals | 54.35 | +0.28% |
| Copper Miners | 76.83 | +0.20% |
| Lithium & Battery Tech | 62.69 | +0.10% |
| Steel | 101.43 | -0.12% |
Industrials | ||
| Aerospace & Defense | 207.74 | +0.74% |
| Construction | 88.597 | +0.69% |
| Global Jets | 26.97 | -0.19% |
| Agriculture | 27.11 | -1.06% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 216.35 | +1.96% |
Renewables | ||
| Hydrogen | 37.44 | +1.57% |
| Solar | 40.98 | -2.48% |
Technology | ||
| Semiconductor | 521.94 | +2.13% |
| Robotics & AI | 34.03 | +1.64% |
| Data Center & Digital Infrastructure | 26.43 | +1.15% |
| Electric Vehicles | 30.75 | +1.12% |
| Cloud Computing | 30.32 | -0.20% |
| FinTech | 24.1354 | -0.23% |
| Cybersecurity | 51.905 | -0.85% |
ASX Today
JB Hi-Fi reports Q1 FY27 comparable sales down 1.4% in Australia and down 0.4% at The Good Guys, offset by 10.7% growth in New Zealand. Sales slowed in October ahead of Black Friday and Christmas as customers hold out for promotional events (JBH)
Lynas Rare Earths posts Q1 FY27 gross sales revenue of $310.1m, up 55% on the pcp and the highest since Q4 FY22. Total REO production lifted to 4,254t and NdPr to 2,082t, with closing cash and short-term deposits of $1,212m (LYC)
Lynas Rare Earths achieves a record average selling price of $102.1/kg in Q1 FY27, up 88% on the pcp on better market pricing, increased bundling of light and heavy rare earths and a wider premium above the market index. Floor price agreements now cover more than half of production (LYC)
Super Retail Group posts Q1 like-for-like sales growth of 0.2% at its AGM, with Supercheap Auto up 2.5% and rebel up 0.3% offsetting BCF down 1.1% and Macpac down 11.7%. Year-to-date earnings remain in line with management expectations (SUL)
Suncorp now expects FY27 GWP growth of around 3%, reflecting the loss of a large commercial contract worth $125m in GWP and a weaker New Zealand dollar, with growth weighted to the second half. The UITR margin is still expected in the top half of the 10-12% range and the rest of the FY27 outlook is unchanged (SUN)
Freightways lifts Q1 FY27 revenue 17.6% to NZ$408.3m, with EBITA up 12.9% to NZ$50.0m and NPAT up 12% to NZ$26.2m on higher fuel recovery and the VTFE acquisition. Lower demand for premium services weighed on margins and same-customer volumes are expected to stay subdued until fuel prices ease (FRW)
Key Events
Stocks trading ex-dividend:
Thu 29 Oct: Autosports Group (ASG) – $0.03, Benjamin Hornigold (BHD) – $0.062, Waterco (WAT) – $0.13
Fri 30 Oct: MA Credit Income Trust (MA1) – $0.016, Metrics Income Opportunities Trust (MOT) – $0.011, Metrics Master Income Trust (MXT) – $0.015, Metrics Real Estate Multi-Strategy Fund (MRE) – $0.01, Stanmore Resources (SMR) – $0.031
Mon 2 Nov: Djerriwarrh Investments (DJW) – $0.037, La Trobe Private Credit Fund (LF1) – $0.013, N1 Holdings (N1H) – $0.004, Pengana Global Private Credit Trust (PCX) – $0.013
Tue 3 Nov: WAM Global (WGB) – $0.066
Wed 4 Nov: None
Thu 5 Nov: Future Generation Global (FGG) – $0.042
Other ASX corporate actions today:
Dividends paid: Turners Automotive Group (TRA)
IPOs: None
AGMs: BWP Group (BWP), Challenger (CGF), Integral Diagnostics (IDX), JB Hi-Fi (JBH), Perpetual (PPT), Super Retail Group (SUL), Wesfarmers (WES), Woolworths (WOW)
Economic calendar (AEDT):
4:00 pm: Japan Consumer Confidence
11:30 pm: US GDP Growth Rate and Core PCE