In a nutshell:
Wall Street was mixed after Thursday's post midterm AI rout, with the S&P 500 and Nasdaq making gains as dip buyers returned to chipmakers, though both benchmarks still finished the week lower
October payrolls more than doubled ests, pushing market-implied odds of a December Fed rate hike back above 75% ahead of Tuesday’s US CPI print
Brent capped a steep 12% weekly fall to US$97 a barrel as Bloomberg reported the US and Iran are edging closer to a deal, with Tehran now open to discussing its nuclear program
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,377 | +0.31% |
Dow Jones | 51,286 | -0.46% |
NASDAQ Comp | 24,579 | +1.09% |
Russell 2000 | 2,754 | +0.89% |
Global Indices | ||
 S&P/TSX | 35,789 | +0.52% |
 Shanghai Composite | 3,649 | -1.10% |
 DAX | 25,820 | -1.92% |
 Hang Seng | 24,482 | -1.27% |
 Nifty 50 | 80,999 | +2.13% |
 Nikkei 225 | 57,435 | -5.96% |
 FTSE 100 | 10,674 | -1.01% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,070.41 | -0.42% |
 Copper | 6.22 | -0.50% |
 WTI Oil | 90.83 | +0.34% |
Currency | ||
 AUD/USD | 0.6874 | +0.12% |
Cryptocurrency | ||
 Bitcoin (USD) | 75,608 | -0.04% |
 Ethereum (AUD) | 3,232 | -0.17% |
Miscellaneous | ||
US 10 Yr T-bond | 4.859 | +0.45% |
VIX | 25.64 | -9.01% |
US Sectors
Sector | % Chg |
|---|---|
| Information Technology | +1.26% |
| Communication Services | +0.52% |
| Industrials | +0.13% |
| Consumer Discretionary | +0.07% |
| Energy | -0.07% |
| Health Care | -0.11% |
Sector | % Chg |
|---|---|
| Utilities | -0.42% |
| Materials | -0.59% |
| Real Estate | -0.64% |
| Financials | -0.68% |
| Consumer Staples | -1.21% |
S&P 500 Session Chart
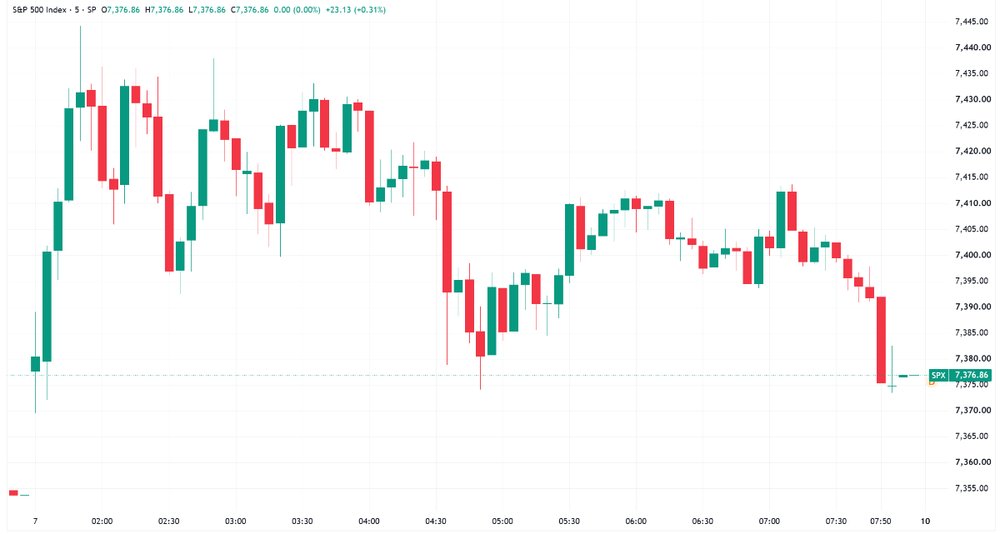
S&P 500 opens higher and whipsaws during trade to finish off best levels (Source: TradingView)
Overnight Markets
Major US benchmarks mostly higher, finished off best levels as dip buyers returned to chipmakers, with the Nasdaq 100 up 1.35% and a gauge of chip giants up 4.2%, though most S&P 500 members fell
S&P 500 fell 2.7% for the week, the Nasdaq lost 3.4% and the Dow shed 0.9%, with all three still up between 5.8% and 7.8% for the year
US bond yields rose Friday as strong jobs data revived December hike wagers, after midterm-driven haven buying pushed yields to their lowest since early September on Thursday
Brent settled near US$98 a barrel, capping its biggest weekly drop since 2022, as traders weighed Iran diplomacy and recovering Gulf exports, while oil traders sought US approval to use some sanctioned tankers (BBG)
A BMO survey found 48% of bond investors would buy a Treasury dip, the most in four months, while five-year breakevens fell to about 2.27% from 2.5% as oil slumped (BBG)
The six largest hyperscalers are expected to spend more than $850bn on AI this year, up 83%, as tech overtakes other non-financial sectors in investment-grade bond issuance (BBG)
CoreWeave’s five-year CDS eased 8% to about 1,155bp on Friday after topping 1,289bp, while Nvidia’s swaps are up 76% in a month as AI credit stress lingers (CNBC)
South Korea waived margin-loan collateral requirements for three months from Monday to curb forced selling after the Kospi’s rout, with margin balances already down 26% from June’s peak (Seoul Economic Daily)
Stocks
OpenAI closed about $11bn of new funding at a $1.25tn valuation, the first part of a round that could grow to as much as $20bn (BBG)
Berkshire Hathaway Q3: operating earnings fell 5.8% to $12.7bn, buybacks of about $9.6bn under CEO Greg Abel, cash pile rose to $377.4bn from the prior quarter despite the spending (BBG)
TSMC has begun drafting plans to make advanced 3D DRAM memory chips at the request of Nvidia, its biggest customer, The Information reported, a move that would widen its role in the AI supply chain (BBG)
Nvidia is requiring Southeast Asian customers seeking Nvidia Cloud Partner status to enrol in a program tracking the location of their AI chips, as Washington steps up scrutiny of smuggling into China (BBG)
Moderna Q3: revenue up 29% to $1.31bn, beat ests by ~48%, EPS $0.38 versus ests for a loss, raised 2026 revenue growth outlook to 15-25% from up to 10% (CNBC)
Tariffs
Trump is set to clash with the incoming Democratic-led Congress over tariffs, with Ron Wyden vowing to reassert congressional authority over trade, though curbing tariff powers will be neither easy nor quick (BBG)
Democrats plan to start rolling back Trump’s tariffs with Canadian goods, where duties range from 15% to 50% on steel, aluminium, dairy and appliances, but repeal would need 60 Senate votes (YF)
BloombergNEF now sees nine of 10 transition metals on track for sufficient supply capacity through 2050 and expects long-term downward pressure on lithium, nickel, cobalt and manganese prices (BBG)
Geopolitics
The US and Iran are edging closer to a breakthrough to end the war, with Tehran studying Qatari proposals on its nuclear program that were previously off the table, a diplomat told Bloomberg (BBG)
Trump said fresh strikes on Iran are highly unlikely to be needed if talks yield a strong agreement, while noting the US has identified 38 bridges it could destroy within an hour (RT)
The US military launched Task Force Iron Gate to curb Iran’s movement of weapons and sanctioned goods across its land borders and the Caspian Sea, extending its months-long naval blockade (RT)
Central Banks
Markets priced about a 78% chance of a December Fed hike after the jobs data, up from 67% on Thursday, with traders bringing forward the expected next-and-final hike to April from June (RT)
San Francisco Fed President Mary Daly said she expects the Fed will need to tighten policy further, describing Americans as stuck on a treadmill of high inflation (CNBC)
Economy
US nonfarm payrolls rose 165,000 in October versus ests of 65,000, topping all forecasts, while unemployment fell to 4.1% and the prior two months were revised higher (BBG)
Bloomberg Economics said hiring was strong and broad-based, with revisions showing the summer slowdown was milder than first reported, though labour tightness gauges still signal little inflationary impulse (BBG)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Uranium | 32.34 | +4.39% |
| Silver Miners | 79.36 | +2.63% |
| Gold Miners | 87.6 | +2.16% |
| Strategic Metals | 51.4 | +1.72% |
| Copper Miners | 71.25 | +1.45% |
| Lithium & Battery Tech | 60.91 | +1.21% |
| Steel | 96.3 | +0.07% |
Industrials | ||
| Aerospace & Defense | 68.98 | +1.28% |
| Global Jets | 28.72 | +1.27% |
| Construction | 85.806 | +0.22% |
| Agriculture | 26.11 | -0.19% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 213.63 | +1.73% |
Renewables | ||
| Solar | 45.58 | +3.38% |
| Hydrogen | 32.88 | +1.95% |
Technology | ||
| Semiconductor | 136.53 | +3.51% |
| Electric Vehicles | 28.5 | +2.48% |
| Robotics & AI | 31.05 | +1.34% |
| Data Center & Digital Infrastructure | 24.87 | +0.53% |
| FinTech | 24.202 | +0.26% |
| Cybersecurity | 43.56 | -0.59% |
| Cloud Computing | 25.85 | -1.15% |
ASX Today
ANZ’s full-year cash profit rose 31% to $7.59bn, or 10% excluding FY25 significant items, as $902m in gross cost savings cut expenses 7% and lifted cash return on tangible equity 109bps to 11.56%. The bank declared a final dividend of 83 cents per share, with franking raised to 80% from 75%, while its collective provision charge rose $108m to $222m as higher interest rates and cost-of-living pressures weighed on customers (ANZ)
Ventia expects second-half FY26 revenue to fall below the prior corresponding period on deferred telecommunications and energy work, but maintained guidance for 7-10% underlying NPATA growth. New CEO Mark Ralston will consolidate the company into three operating sectors from 1 December, targeting at least $60m in annualised savings by December 2027 at a one-off cost of about $30m (VNT)
Metals X has submitted a revised non-binding cash offer for London-listed First Tin, with the UK Takeover Panel extending the deadline for Metals X to make a firm offer or walk away to 5pm (London time) on 20 November. The company said there is no certainty an offer will be made (MLX)
What To Watch Today
Kerry is back tomorrow
Key Events
Stocks trading ex-dividend:
Mon 9 Nov: Clime Capital (CAM) – $0.005, Future Generation Australia (FGX) – $0.038, NAOS Ex-50 Opportunities Company (NAC) – $0.016, NAOS Small Cap Opportunities Company (NSC) – $0.01
Tue 10 Nov: None
Wed 11 Nov: ResMed (RMD) – $0.066
Thu 12 Nov: Dominion Income Trust 1 (DN1) – $0.687
Fri 13 Nov: None
Other ASX corporate actions today:
Dividends paid: None
IPOs: None
AGMs: Ansell (ANN)
Economic calendar (AEDT):
9:30 am: RBA Hunter Speech
12:30 pm: China Inflation Rate