In a nutshell:
Major US benchmarks all sharply higher and near best levels as Democrats won both chambers of Congress, removing election uncertainty and sparking a dip-buying rally in megacap tech
Brent fell to a two-month low near US$95 a barrel as the White House tied the midterm losses to the Iran war, lifting bets on a faster end to the conflict
AI data centre builders and chipmakers lagged on fears a Democratic Congress and new governors in key data centre states will bring tougher scrutiny of the AI buildout
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,689 | +1.58% |
Dow Jones | 53,356 | +3.03% |
NASDAQ Comp | 25,737 | +1.44% |
Russell 2000 | 2,855 | +1.53% |
Global Indices | ||
 S&P/TSX | 36,341 | +2.28% |
 Shanghai Composite | 3,686 | +2.16% |
 DAX | 26,438 | +2.22% |
 Hang Seng | 23,920 | +1.67% |
 Nifty 50 | 77,301 | +0.50% |
 Nikkei 225 | 62,189 | -1.42% |
 FTSE 100 | 10,829 | +1.79% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,065.23 | +3.40% |
 Copper | 6.39 | +0.19% |
 WTI Oil | 88.52 | -7.88% |
Currency | ||
 AUD/USD | 0.7007 | +0.59% |
Cryptocurrency | ||
 Bitcoin (USD) | 80,196 | +3.08% |
 Ethereum (AUD) | 3,455 | +5.79% |
Miscellaneous | ||
US 10 Yr T-bond | 4.894 | -1.17% |
VIX | 16.86 | -19.07% |
US Sectors
Sector | % Chg |
|---|---|
| Consumer Discretionary | +4.27% |
| Financials | +3.46% |
| Real Estate | +3.19% |
| Materials | +3.06% |
| Health Care | +3.04% |
| Communication Services | +2.95% |
Sector | % Chg |
|---|---|
| Consumer Staples | +2.95% |
| Information Technology | +0.55% |
| Utilities | +0.43% |
| Industrials | -1.11% |
| Energy | -4.77% |
S&P 500 Session Chart
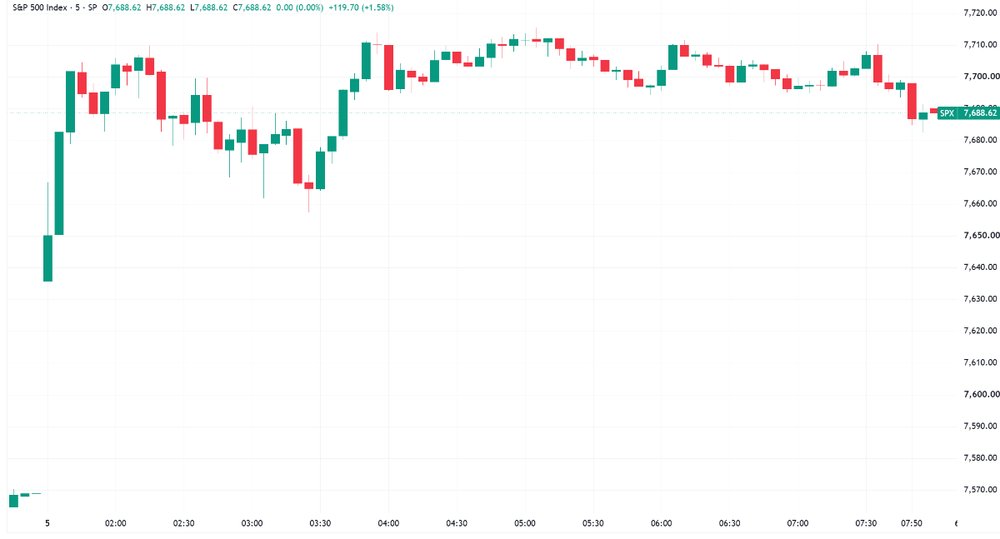
S&P 500 opens higher and trends sideways to close near best levels (Source: TradingView)
Overnight Markets
Major US benchmarks sharply higher, led by technology megacaps, as Democrats swept Congress and Trump said he would accept the midterm results, easing uncertainty and prompting investors to buy the recent dip
US bond yields furthered their recent fall as investors bet a divided Washington will constrain Trump's tax and spending plans and limit new issuance, with Wellington's Brij Khurana noting divided government has historically been good for Treasuries (BBG)
Brent sank to a two-month low near US$95 a barrel as traders bet the Democratic sweep will accelerate efforts to end the Iran war, with the election widely seen as a referendum on affordability (BBG)
The Bloomberg dollar gauge fell as much as 0.5%, the most in two months, sliding against all G10 peers on concerns the Democratic sweep could erode the US exceptionalism story (BBG)
Gold rose 3.4% to around US$4,060/oz and silver climbed to around $52/oz as the dollar slid and Treasuries rallied (TE)
Companies building and powering AI data centres pulled back after candidates in Texas and elsewhere campaigned on concerns the AI boom is lifting power bills and threatening high-paying jobs (BBG)
Quilter strategist Kit Rees warned any curbs on future AI development could put the brakes on US growth, given AI has been a major engine of the economy (RT)
US Treasury will offer $125bn of securities at next week's refunding to cover about $97bn of maturing debt, keeping auction sizes steady and noting it continues to evaluate future changes (Treasury)
Meta drew a record €53bn of orders for its debut euro-denominated bond sale as it seeks to raise as much as €9bn, following a $15bn US dollar deal (BBG)
China's tech-heavy Star 50 Index surged nearly 10%, its best session since July, after ETFs favoured by the national team drew 76.7bn yuan of inflows on Tuesday, the second largest on record (BBG)
Stocks
Amazon rose 6%, Microsoft 6.7%, Alphabet 3.2% and Meta 1.4% on bets a Democratic Congress will slow AI spending that is eating into free cash flow. Apple, a lighter AI spender, jumped more than 5.3%, with the five on pace to add nearly $1tn in market value (BBG)
Tesla and SpaceX fell as the Democratic sweep sharpened investor concern over the outlook for Republican megadonor Elon Musk's key holdings, with SpaceX down 3.8% and Tesla about 3.2% lower in premarket trade (BBG)
Chip stocks were muted despite AMD forecasting faster-than-expected 2027 growth on surging data centre sales, as Democrats made gains in key data centre states Texas and Georgia (RT)
McDonald's Q3: global same-store sales up 1.5% versus ests of 1.4%, US same-store sales down 0.2% versus an expected 0.5% drop, trends improved through the quarter and October app promotions drove strength into the holidays, shares up 6.3% (YF)
Uber Q3: revenue up 9.6% to $14.8bn, gross bookings up 20% to $59.82bn, adjusted EPS $0.88 beat ests by ~2%, Q4 adjusted EPS guidance of $0.95 to $0.99 sits below ests of $1 (Investing)
Novo Nordisk lifted its 2026 outlook for the third time as Wegovy pill sales beat forecasts, now guiding to adjusted sales and operating profit between 2% growth and a 2% decline at constant currency, from flat to a 6% fall, shares up as much as 5% (RT)
US Midterms & Iran
Democrats won control of both chambers of Congress, securing at least 228 House seats and at least 54 Senate seats (BBG)
Trump congratulated Democrats on their midterm election victories in a phone call with CBS News (TS)
Trump said he has no immediate plans to launch strikes on Iran following the midterm elections, in which Democrats won control of Congress in a landslide (BBG)
Vice President JD Vance posted on X that the Iran war is why Republicans were routed, while likely incoming Senate majority leader Chuck Schumer vowed Democrats will push to end the conflict (Axios)
Qatar and Pakistan continued mediation, with Qatari officials expecting responses from both the US and Iran on proposals to end the conflict, despite reports negotiations remain far from an agreement (TE)
Tariffs
Democrats' new majorities can force votes, call hearings and open investigations into Trump's tariffs once Congress convenes on 3 January, but any repeal bill would face a veto requiring two-thirds majorities to override (BBG)
Trade officials abroad may sense leverage over Trump for the first time since January 2025, after voters blamed tariffs and the Iran war for affordability problems, Bloomberg's Brendan Murray wrote (BBG)
Commerce Secretary Howard Lutnick has quietly pushed to restart Canada-US trade talks stalled since August, focused on Section 232 tariffs on steel, aluminium, lumber and autos (YF)
Central Banks
Traders curbed wagers on Fed rate hikes over the coming year as the election result contributed to a steep fall in oil prices on the prospect of an end to the Middle East war (BBG)
Capital Economics' Andrew Lilley said an expected brake on AI development could slow growth and give the Fed a reason not to hike, with money markets slightly trimming 2027 hike bets, LSEG data showed (RT)
Economy
US private payrolls rose 86,000 in October, beating ests of 69,000, after a downwardly revised 86,000 gain in September, ahead of Friday's official payrolls report where ests are for 65,000 (RT)
US ISM services PMI eased to 54.5 in October, a three-month low, versus ests of 54.8, with the prices index at 73.0 from 74.0 and new orders slowing to 55.9 (TE)
China's RatingDog services PMI unexpectedly slipped to 50.8 in October, a three-month low, versus ests of 51.7, as firms cut selling prices despite intensifying input cost inflation (BBG)
UK services PMI rose to an eight-month high of 52.8 in October, below the 53.1 flash reading, with S&P Global saying the report underscores why the BoE looks likely to hike on Thursday (RT)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Silver Miners | 78.16 | +9.67% |
| Gold Miners | 84.54 | +8.94% |
| Copper Miners | 74.54 | +3.95% |
| Strategic Metals | 51.63 | +3.82% |
| Lithium & Battery Tech | 61.87 | +2.95% |
| Steel | 99.75 | +0.56% |
| Uranium | 32.69 | -1.09% |
Industrials | ||
| Global Jets | 29.45 | +6.66% |
| Agriculture | 26.45 | -0.26% |
| Construction | 91.38 | -0.66% |
| Aerospace & Defense | 212.8095 | -1.55% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 221.13 | +2.63% |
Renewables | ||
| Solar | 45.835 | +5.76% |
| Hydrogen | 35.63 | +1.11% |
Technology | ||
| FinTech | 25.015 | +3.03% |
| Data Center & Digital Infrastructure | 25.95 | +2.45% |
| Electric Vehicles | 29.443 | +1.62% |
| Robotics & AI | 32.81 | +1.52% |
| Cloud Computing | 27.65 | +0.80% |
| Cybersecurity | 46.98 | +0.32% |
| Semiconductor | 450.41 | -3.14% |
ASX Today
National Australia Bank’s FY26 cash earnings fell 13.4% to $6.14bn including $949m of large notable items, and were flat at $7.09bn excluding them. Credit impairment charges rose 86% to $1.55bn including a $403m top-up to forward-looking provisions, while NIM rose 6 bps to 1.80% and the final dividend is held at 85 cents fully franked (NAB)
St Barbara has restarted ore processing at Touquoy in Nova Scotia, with full production expected by end of December and first gold pour in January 2027. FY27 guidance is 17,000–21,000 ounces at an AISC of A$2,070–2,560/oz, with $40–50m of growth capex across Touquoy and the 15-Mile hub (SBM)
What To Watch Today
Hi there – Kerry here. Get ready for an (almost) everything rally.
The blue wave: Lots of commentary out there about how strong the US market performs post-mid terms. In the case of a Republican president losing congress to Democrats (7 instances since 1954), the S&P 500 is up an average 2.1% a month later, 17.5% six months later, and up 15.5% a year later. Oil prices plunged as Trump now has no political capital to keep the war going (the country is shifted so far blue that they now have a mandate to end this war). So oil is coming back down to earth (even if downstream is still tight), and so does inflation (and therefore goodbye rate hikes, and hello a long hold). ASX futures are pointing to a near 200 pt bump at the open, and expect those yield-sensitive and consumer-facing sectors to lead. Our overnight ETF watchlist also featured massive gains for sectors like Gold Miners (+9.0%), Airlines (+6.7%), Homebuilders (+5.4%) and Copper Miners (+3.9%). On the flip side, sectors like energy, defence, uranium and chipmakers struggled.
Key Events
Stocks trading ex-dividend:
Thu 5 Nov: Future Generation Global (FGG) – $0.042
Fri 6 Nov: New Murchison Gold (NMG) – $0.003
Mon 9 Nov: Clime Capital (CAM) – $0.005, Future Generation Australia (FGX) – $0.038, NAOS Ex-50 Opportunities Company (NAC) – $0.016, NAOS Small Cap Opportunities Company (NSC) – $0.01
Tue 10 Nov: None
Wed 11 Nov: ResMed (RMD) – $0.066
Other ASX corporate actions today:
Dividends paid: United Overseas Australia (UOS), Washington H. Soul Pattinson (SOL)
Earnings: News Corp (NWS), Light & Wonder (LNW), James Hardie (JHX), National Australia Bank (NAB), Novo Resources (NVO)
IPOs: None
Economic calendar (AEDT):
11:30 am: Australia Balance of Trade
11:00 pm: Bank of England Interest Rate Decision