In a nutshell:
A weak September payrolls print took an October Fed hike off the table, with tech leading and the Nasdaq scoring an intraday all-time high
Iran hardened its stance on Hormuz over the weekend as more tankers were struck and Washington sent a third carrier to the region
Oil supply relief came from two fronts as the G7 agreed to tap 100 million barrels of reserves and OPEC+ held November output steady
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,723 | +0.73% |
Dow Jones | 51,177 | +0.49% |
NASDAQ Comp | 27,191 | +1.19% |
Russell 2000 | 2,833 | +0.94% |
Global Indices | ||
 S&P/TSX | 35,503 | +0.99% |
 Shanghai Composite | 3,842 | +0.31% |
 DAX | 25,231 | +1.17% |
 Hang Seng | 23,972 | -2.60% |
 Nifty 50 | 71,910 | -0.79% |
 Nikkei 225 | 68,309 | -0.94% |
 FTSE 100 | 10,462 | +0.32% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,140.19 | -0.90% |
 Copper | 6.49 | +0.15% |
 WTI Oil | 91.11 | -1.90% |
Currency | ||
 AUD/USD | 0.6948 | -0.12% |
Cryptocurrency | ||
 Bitcoin (USD) | 85,851 | +1.35% |
 Ethereum (AUD) | 3,895 | +0.72% |
Miscellaneous | ||
US 10 Yr T-bond | 5.277 | +0.76% |
VIX | 15.31 | -6.59% |
US Sectors
Sector | % Chg |
|---|---|
| Consumer Discretionary | +1.38% |
| Information Technology | +1.06% |
| Materials | +1.00% |
| Communication Services | +0.88% |
| Industrials | +0.78% |
| Utilities | +0.37% |
Sector | % Chg |
|---|---|
| Real Estate | +0.36% |
| Energy | +0.21% |
| Consumer Staples | +0.16% |
| Financials | +0.01% |
| Health Care | -0.04% |
S&P 500 Session Chart
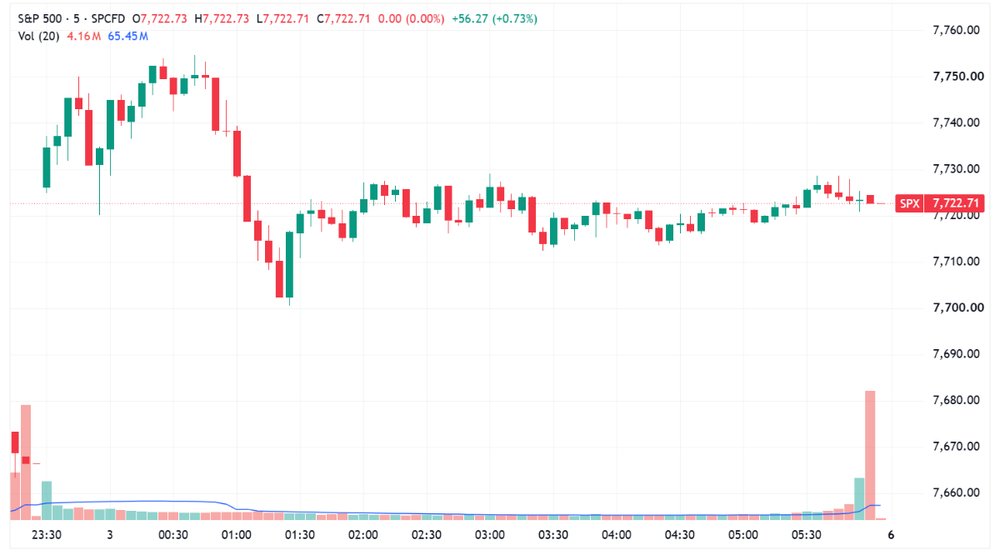
S&P 500 trades largely sideways after a small gap up (Source: TradingView)
Overnight Markets
Major US benchmarks higher, finishing off best levels after the Nasdaq touched an intraday record on a softer-than-expected jobs print
Nasdaq the only major average up for the week, up 0.45%, with the S&P 500 down 0.3% and the Dow down 1.3% amid a global bond rout
Bond yields reversed higher despite the jobs miss, with the US 2-year yield down as much as 9 bps, but finished the session up 3 bps to 4.82%
Bond traders pared Fed hike bets after the payrolls miss, pushing two-year Treasury yields down as much as 10bps to 4.69% (BBG)
Bessent downplayed the Treasury selloff, saying the rise in yields is in line with global trends and dismissing AI bubble concerns (BBG)
Contagion fears are returning to Europe's bond market, with traders on alert after a selloff led by French debt revived memories of the debt crisis (BBG)
JPMorgan's Feroli still expects a December Fed hike, saying slower wage growth argues against a hurried hiking cycle (RT)
Morgan Stanley put Nvidia back atop its semiconductor picks, citing its customer breadth and the importance of GPUs to agentic AI (CNBC)
Stocks
Nvidia hit a record intraday high of $237.87, lifting its market value to $5.72 trillion as AI infrastructure names led tech higher (YF)
Tesla Q3 deliveries down 2% year-on-year to 486,532, ~5% ahead of ests. Production was 464,391 and Semi volume production has begun, but the Roadster was delayed. Shares up ~5% (YF)
Nike Q1 FY27 revenue down 4% to $11.21bn, ~1% below ests, EPS $0.48. It guided FY27 revenue down high single digits and flagged job cuts, with shares down as much as 6% after hours (YF)
Broadcom banks are preparing to syndicate $60bn of AI chip financing, a $42bn senior tranche plus an $18bn Blackstone-led junior tranche, to fund chips for Anthropic and others (YF)
Iran & Energy
Iran says Hormuz will stay shut until the US meets seven conditions under June's Islamabad memorandum, chief negotiator Ghalibaf said Sunday (CNBC)
At least two tankers were struck near Oman and Iran over the weekend, one suffering engine room damage, UKMTO reported (CNBC)
Trump is sending the USS Theodore Roosevelt and about 10,000 sailors and Marines to the Middle East as Iran's inflation nears 90% (BBG)
Houthis claimed a missile and drone strike on an Aramco facility in Riyadh after a witness saw smoke and fire, though Saudi authorities did not confirm an attack (RT)
OPEC+ kept November output targets steady at a brief Sunday meeting of seven core members, who meet again on November 1 (RT)
G7 to release 100 million barrels of oil and diesel over four months, with a front-loaded diesel release within 20 days (CNN)
Tariffs & Trade
Central Banks
Fed's Goolsbee says a hike and a pause are both "on the table", calling the labour market steady and inflation the bigger priority (RT)
Fed seen skipping October but hiking in December, with futures pricing about a one-in-four chance of an October 27-28 move (RT)
El-Erian says the jobs report puts the Fed "definitely on hold" for October, with the focus staying on inflation (YF)
Hassett says Powell should "move on" from the Fed board after an internal report cited management failures in the headquarters renovation (BBG)
Economy
US payrolls rose just 29,000 in September against ~85,000 ests, unemployment ticked up to 4.2% and August was revised down to 133,000 (YF)
US average hourly earnings rose 0.1% month-on-month, 3% year-on-year, trailing August's 3.4% CPI (YF)
Eurozone inflation jumped to 3.8% year-on-year in September from 3.2%, above the 3.6% forecast and the highest since September 2023, with energy up 18.8% (CNBC)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Copper Miners | 85.91 | +3.01% |
| Steel | 103.53 | +1.69% |
| Lithium & Battery Tech | 69.28 | +1.55% |
| Gold Miners | 87.78 | +1.20% |
| Silver Miners | 86.5 | +1.02% |
| Uranium | 39.79 | +0.51% |
| Strategic Metals | 63.21 | +0.41% |
Industrials | ||
| Construction | 92.6343 | +1.14% |
| Agriculture | 28.21 | +0.28% |
| Global Jets | 28.14 | +0.18% |
| Aerospace & Defense | 207.79 | -0.12% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 205.29 | -0.33% |
Renewables | ||
| Hydrogen | 44.9889 | +2.43% |
| Solar | 44.05 | +2.28% |
Technology | ||
| Semiconductor | 588.9 | +2.18% |
| Robotics & AI | 36.03 | +1.69% |
| Electric Vehicles | 33.53 | +1.45% |
| Cybersecurity | 46.92 | +0.95% |
| Data Center & Digital Infrastructure | 27.27 | +0.74% |
| FinTech | 24.34 | -0.25% |
| Cloud Computing | 28.81 | -0.66% |
ASX Today
Ingenia Communities board is expected to grant Warburg Pincus limited due diligence after last week's $5.25 per share bid, having knocked back earlier approaches at $4.75 and $5.05. The US firm says it has support from at least 30% of the register and is pushing the board to recommend its proposal over the unpopular $1bn Peet acquisition (AFR)
Rio Tinto draws Singapore sovereign fund GIC into the ~$7bn auction of its Pilbara and Canadian power infrastructure, with JPMorgan mandated on a bid. Ares Management is also preparing an indicative offer, joining IFM, KKR, GIP and Apollo ahead of non-binding bids due mid-month. Rio is yet to decide what stake it retains (AFR)
Turners Automotive Group declares a Q1 FY27 dividend of 7 cents per share fully imputed, flat on the pcp, payable 29 October with a record date of 13 October (TRA)
What To Watch Today
Not a whole lot. A sizeable US payrolls miss drove October Fed hike bets down to 22.1% from 64.4% a week ago, yet US bond yields staged a rather incredible reversal, closing 1-3 bps higher after intraday declines of 6-10 bps. The likely driver was oil, which clawed back a ~4% decline to close 0.5% higher at US$102.66 a barrel. Nevertheless, the ASX is set to trade higher on strong overnight breadth, a slightly lower US dollar and flattish commodity prices. Miners were eager to trade higher, with the Global X Copper Miners ETF rose 3.0% with copper flat at US$6.61/lb, and the VanEck Gold Miners ETF added 1.20% even as gold fell 0.8%.It caps a wild week for the local market, which featured the Tuesday-Wednesday relief rally post RBA/CPI, then Thursday's 2% selloff and Friday's 0.79% bounce. Still, a very awkward and uncomfortable market. It's also a public holiday for NSW (Labour Day), so volume/liquidity could also run a little thin.
Key Events
Stocks trading ex-dividend:
Mon 5 Oct: Qualitas Real Estate Income Fund (QRI) – $0.01, Simonds Group (SIO) – $0.005, Verbrec (VBC) – $0.002
Tue 6 Oct: Harvey Norman Holdings (HVN) – $0.13, Katana Capital (KAT) – $0.005, Reece (REH) – $0.134, Ridley Corporation (RIC) – $0.053
Wed 7 Oct: MFF Capital Investments (MFF) – $0.11, Ryder Capital (RYD) – $0.03
Thu 8 Oct: ARB Corporation (ARB) – $0.35, Clime Capital (CAM) – $0.014, Naos Emerging Opportunities Company (NCC) – $0.021, WAM Capital (WAM) – $0.077
Fri 9 Oct: EQT Holdings (EQT) – $0.20
Other ASX corporate actions today:
Dividends paid: AMA Group (AMA), Fenix Resources (FEX), Genesis Minerals (GMD), Teaminvest Private Group (TIP)
Earnings: None
IPOs: Normandy Minerals (NMD)
AGMs: Djerriwarrh Investments (DJW), Mirrabooka Investments (MIR)
Economic calendar (AEDT):
12:00 am: US ISM Services PMI