In a nutshell:
Major US benchmarks finish higher and close to best levels, with the Dow (+1%) and Russell 2000 (+1.38%) the largest winners as traders rotated out of chipmakers and into defensive names
Chipmakers declined for a seventh straight session with the Philadelphia Semiconductor index (SOX) down 14% since 6 October on AI financing and competition worries
The US PPI print showed producer prices rose at the fastest annual pace since 2022, yet traders trimmed October Fed hike bets ahead of Chair Warsh’s final pre-meeting remarks
Iran stepped up attacks on Strait of Hormuz shipping, keeping Brent hovering around US$105 a barrel as US crude inventories fell by more than 8m barrels
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,744 | +0.33% |
Dow Jones | 52,178 | +1.08% |
NASDAQ Comp | 26,713 | +0.08% |
Russell 2000 | 2,767 | +1.38% |
Global Indices | ||
 S&P/TSX | 36,137 | +1.55% |
 Shanghai Composite | 3,707 | -1.59% |
 DAX | 25,383 | +0.33% |
 Hang Seng | 24,063 | -1.03% |
 Nifty 50 | 74,316 | +2.11% |
 Nikkei 225 | 64,426 | -4.90% |
 FTSE 100 | 10,840 | +1.08% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,170.81 | +1.59% |
 Copper | 6.52 | -1.38% |
 WTI Oil | 97.55 | +2.59% |
Currency | ||
 AUD/USD | 0.6917 | -0.05% |
Cryptocurrency | ||
 Bitcoin (USD) | 82,057 | +0.47% |
 Ethereum (AUD) | 3,544 | +1.64% |
Miscellaneous | ||
US 10 Yr T-bond | 5.089 | -1.95% |
VIX | 16.46 | -2.43% |
US Sectors
Sector | % Chg |
|---|---|
| Health Care | +1.84% |
| Materials | +1.71% |
| Financials | +1.38% |
| Consumer Discretionary | +1.16% |
| Real Estate | +1.00% |
| Communication Services | +0.62% |
Sector | % Chg |
|---|---|
| Industrials | +0.49% |
| Consumer Staples | +0.37% |
| Utilities | -0.21% |
| Information Technology | -0.54% |
| Energy | -1.55% |
S&P 500 Session Chart
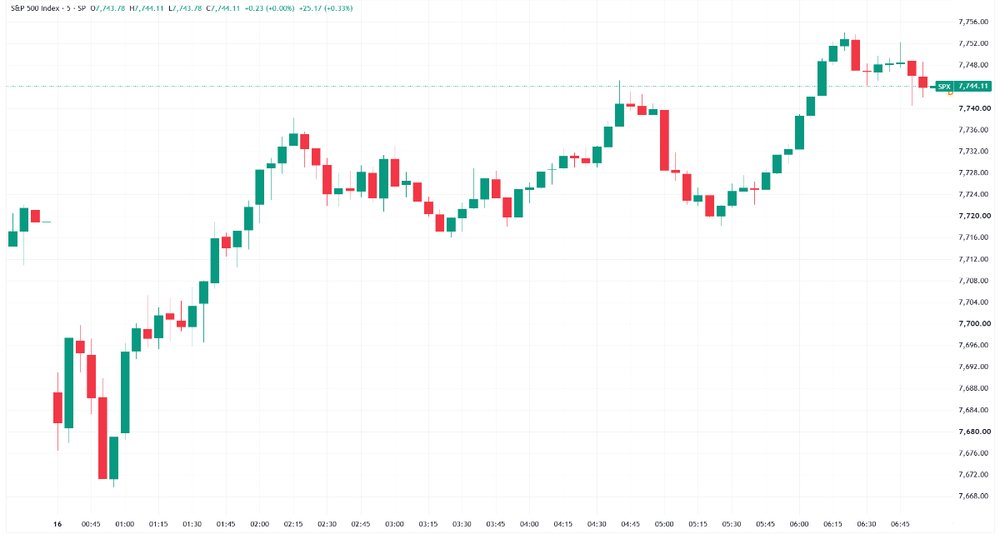
S&P 500 trends higher to finish just off best levels (Source: TradingView)
Overnight Markets
Major US benchmarks finished higher and close to best levels in a session that saw traders rotate out of chipmakers into consumer names such as Nike (+5%) and Walmart (+1.5%), Nasdaq finished break even but recovered from a 1.4% intraday drop
Breadth was strong, with the S&P 500 Equal-Weight index up 1.3% and eight of 11 sectors higher, while Utilities, Technology and Energy lagged
Capital piled into long-duration as investors sought safety from the AI rout. The US 10-year fell 11 bps to 5.07% and the 30-year also down 10 bps to 5.42%, now down 25 bps in the last five sessions
Brent settled around US$105 a barrel as investors weighed possible US moves to ease shadow fleet sanctions
Chipmakers declined for a seventh straight session with the Philadelphia Semiconductor index (SOX) 14% down since 6 October on AI financing and competition worries: Nvidia has fallen 9.2% since 6 October and Intel has shed 20% since 2 October
Twenty of the most valuable global AI and semiconductor stocks have shed more than $1tn this week on rate hike, AI financing and competition worries, with Nvidia, AMD and Intel all lower on Thursday (CNBC)
Bloomberg’s Charles Riley said the US stock market’s longest stretch of calm since 2020 is over as AI and rate fears collide (BBG)
Japan’s Nikkei 225 tumbled 4.9% and South Korean stocks also sank, with Morningstar’s Lorraine Tan warning any risk to AI spending growth could slow chip demand in Korea and Taiwan (AP)
Crossbridge Capital’s Manish Singh said AI demand is real but not every infrastructure builder will earn attractive returns, adding that “debt servicing is still the present” (BBG)
Stocks
TSMC Q3: net profit up 68.7% to a record NT$763.1bn, ahead of ests and a sixth straight record, operating margin of 58.7% topped the upper end of guidance, free cash flow more than tripled to NT$476.6bn, management cited agentic and open-source AI as sustaining strong demand (CNBC)
Nvidia CEO Jensen Huang told Bloomberg CoreWeave’s “strength is improving every day” and its cost of capital is falling, bolstering the shares after a heavy sell-off in its stock and bonds (BBG)
CoreWeave’s five-year credit default swaps jumped as much as 74.5bp to a record 1,194.5bp, pricing more than 60% odds of default within five years (BBG)
Anthropic told investors it was cash flow positive in Q3, with revenue up nearly 50% from the prior quarter to $16.8bn (Axios)
Tariffs
China will keep approving rare earth export licences to Europe regardless of whether the US-China trade truce is extended past January, Commerce Ministry spokesperson He Yadong said (CNBC)
Republican candidates in battleground races including Michigan’s Mike Rogers and Maine’s Susan Collins are distancing themselves from Trump’s tariffs ahead of the 3 November midterms (NBC)
Central Banks
Fed funds futures cut October hike odds to below 30% after the PPI release, almost 4 percentage points lower than Wednesday, according to CME FedWatch (YF)
Mizuho’s Alex Pelle said the data give little reason for the Fed to hesitate on further hikes, with futures pricing a 91% chance of at least one hike by December (CNBC)
Fed Chair Kevin Warsh holds a fireside chat with IMF Managing Director Kristalina Georgieva in Bangkok at 2.30pm AEDT today, ahead of the Fed’s 27 to 28 October meeting (Fed)
Geopolitics
Iran stepped up attacks on ships transiting the Strait of Hormuz, with traders weighing potential supply disruptions as WTI settled near US$98 (CNBC)
Economy
US PPI rose 1.3% month-on-month in September, the most since March 2022, and 6.3% year-on-year, while core rose 0.7% and 5%, with all four readings above every forecast in a Bloomberg survey (BBG)
Producer goods prices jumped 2.6%, the most since the series began in 2009, as gasoline surged 20.3%, against a 0.5% headline PPI forecast from economists polled by Reuters (RT)
US retail sales rose 0.8% month-on-month in September against 0.3% ests as gasoline prices soared 7.1%, while the control group gained just 0.1% versus 0.3% ests (RT)
Australia’s unemployment rate edged up to 4.7% in September, above expectations and the highest since October 2021, as almost 40,000 jobs were lost (AAP)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Gold Miners | 87.02 | +4.34% |
| Silver Miners | 82.3 | +3.48% |
| Uranium | 36.12 | +1.63% |
| Copper Miners | 80.83 | +0.01% |
| Strategic Metals | 55.74 | -0.07% |
| Steel | 101.76 | -0.68% |
| Lithium & Battery Tech | 65.57 | -1.22% |
Industrials | ||
| Global Jets | 26.56 | +2.79% |
| Construction | 88.38 | +1.32% |
| Aerospace & Defense | 206.92 | +1.31% |
| Agriculture | 28.28 | +0.07% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 207.41 | +2.05% |
Renewables | ||
| Solar | 42.75 | +0.26% |
| Hydrogen | 38.01 | -2.96% |
Technology | ||
| FinTech | 25.0105 | +3.78% |
| Cloud Computing | 29.52 | +2.22% |
| Cybersecurity | 46.8 | +0.52% |
| Data Center & Digital Infrastructure | 26.24 | -0.19% |
| Electric Vehicles | 31.12 | -0.26% |
| Semiconductor | 514.71 | -0.91% |
| Robotics & AI | 33.74 | -1.08% |
ASX Today
Australian Ethical posts Q1 FUM of $14.43bn, down from $14.50bn at 30 June, as soft Australian equities, $0.08bn of distributions and wholesale redemptions offset inflows. Super net flows of $0.13bn lifted super FUM to $10.53bn, while investment flows were negative $0.10bn (AEF)
Dusk Group says first 15 weeks of FY27 sales rose 5.7% on pcp and like-for-likes 7.2%, achieved with six fewer stores. Gross margin dollars were up 6.9% and 1H27 margin is expected above pcp on better promotions and sourcing. Early Christmas read in line (DSK)
PLS Group takes FID on the ~$1.9bn P2000 expansion at Pilgangoora, lifting spodumene capacity to ~2Mtpa from the September quarter CY29. Incremental post-tax NPV of $2.7bn and 29.5% IRR at US$1,620/t SC6, with unit costs of ~$620/t FOB, funded from existing cash and operating cashflow (PLS)
PLS Group lifts the Pilgangoora Ore Reserve 23% to 249.2Mt at 1.24% Li2O, a 31% increase in contained lithium to ~3.1Mt, including a maiden underground reserve of 46.5Mt at 1.50%. Supports a 20-year open pit life, or 25-plus years with underground (PLS)
PLS Group will also spend $600-650m on Pilgangoora infrastructure through to FY29, weighted to FY28, covering a sealed Wodgina Road East, a 1,200-bed village and a mine services facility. The road upgrade cuts daily concentrate haulage movements ~35%, with WA government co-funding (PLS)
Zip Co will seek shareholder approval at its 2026 AGM for a five-for-one share consolidation, cutting shares on issue to a level the board considers more appropriate for its size and market position. The board unanimously recommends the resolution (ZIP)
What To Watch Today
Kerry here – Wall Street staged a massive rotation out of chips and AI and into healthcare, banks, retailers and anything that benefits from lower long-term yields. US 10- and 30-year yields both fell about 11 bps, a big red candle, though they’re only nearing a one-month low.
Defensives in demand: The ASX may have been front-running the move, with local Staples (+3.4%), Financials (+2.1%), Utilities (+2.0%) and Telcos (+1.5%) all surging on Thursday. In the US, Healthcare (+1.8%) hit an all-time high, while the Homebuilders ETF rallied 3.1% off a 16-month low and the Airlines ETF gained 2.7% off a five-month low
Gold rallies, the rest of resources stall: Gold rallied 1.6% to US$4,170, with palladium, silver and platinum also sharply higher. That sparked a strong move in the Gold Miners ETF, up 4.3% overnight. Copper continues to struggle, down 0.8% to US$6.61/lb for a third straight loss, and other resource ETFs, including Copper Miners, Nickel and Rare Earths/Strategic Metals, finished flat
Key Events
Stocks trading ex-dividend:
Fri 16 Oct: Gowing Bros (GOW) – $0.03, WAM Microcap (WMI) – $0.053
Mon 19 Oct: FFI Holdings (FFI) – $0.125, Solaris Australian Equity Income Plus (SET) – $0.007, WAM Income Maximiser (WMX) – $0.007
Tue 20 Oct: Clover Corporation (CLV) – $0.013, Kingsgate Consolidated (KCN) – $0.1
Thu 22 Oct: N1 Holdings (N1H) – $0.004
Other ASX corporate actions today:
Dividends paid: Embelton (EMB), Flight Centre (FLT), Imperial Pacific (IPC), Kip McGrath Education Centres (KME), London City Equities (LCE), MLG Oz (MLG), NRW (NWH), SKS Technologies (SKS), St Barbara (SBM)
IPOs: Europa Metals (EUZ) – 12:00 pm, Overwatch Technologies (OWL) – 11:00 am
AGMs: Perenti Global (PRN) – 10:30 am
Economic calendar (AEDT):
2:30 pm: Fed Chair Warsh Speech