In a nutshell:
Major US benchmarks fell as Jensen Huang’s exit rattled the AI trade, though AMD, Broadcom and energy shares helped Wall Street claw back most of an early slide
Nvidia named CFO Colette Kress interim CEO after Huang’s exit, putting its roughly US$10bn Anthropic IPO commitment and next Tuesday’s earnings firmly in focus
Trump said the US doesn’t need a deal with Iran and sidelined Vance from talks, lifting Brent back towards US$94 as more tankers were hit in Hormuz
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,592 | -0.35% |
Dow Jones | 52,297 | -0.36% |
NASDAQ Comp | 25,366 | -0.39% |
Russell 2000 | 2,799 | -1.64% |
Global Indices | ||
 S&P/TSX | 36,137 | -0.75% |
 Shanghai Composite | 3,656 | -0.67% |
 DAX | 26,772 | +0.41% |
 Hang Seng | 24,009 | -1.26% |
 Nifty 50 | 81,911 | +0.04% |
 Nikkei 225 | 60,819 | -0.70% |
 FTSE 100 | 10,863 | +0.25% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 3,874.34 | -2.85% |
 Copper | 6.18 | -1.57% |
 WTI Oil | 88.98 | +2.83% |
Currency | ||
 AUD/USD | 0.6806 | -0.60% |
Cryptocurrency | ||
 Bitcoin (USD) | 71,291 | -4.06% |
 Ethereum (AUD) | 2,956 | -3.10% |
Miscellaneous | ||
US 10 Yr T-bond | 5.103 | +2.10% |
VIX | 18.93 | +8.23% |
US Sectors
Sector | % Chg |
|---|---|
| Energy | +1.50% |
| Communication Services | +0.37% |
| Utilities | -0.05% |
| Consumer Discretionary | -0.07% |
| Consumer Staples | -0.14% |
| Information Technology | -0.42% |
Sector | % Chg |
|---|---|
| Real Estate | -0.50% |
| Health Care | -0.66% |
| Financials | -0.72% |
| Industrials | -0.91% |
| Materials | -1.49% |
S&P 500 Session Chart
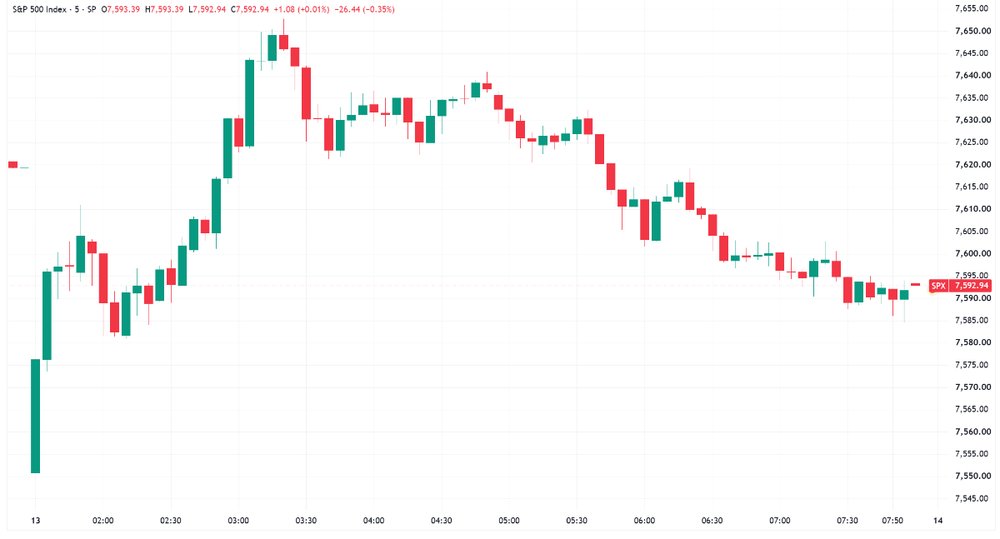
S&P 500 regained early losses, but trended lower to finish near the flatline (Source: TradingView)
Overnight Markets
Major US benchmarks lower and finished off worst levels after the S&P 500 and Nasdaq erased early losses as energy shares rallied on firmer oil, while Nvidia traded well off its session lows of -14% to finish around 5% down
US 10-year yield jumped back above 5% as bond trading resumed after Veterans Day, with higher oil and bets on further Fed hikes driving a 14 basis point jump in the 2-year yield
Brent crude rebounded to around US$96 a barrel, a near 4%, after Trump said the US doesn’t need a deal with Iran, reversing an earlier slide on signs of resurgent Saudi supply
Gold fell 2.7% to US$3,880 an ounce, now down 6.2% for the week, as stubborn US inflation and hawkish Fed commentary cemented bets on a December rate hike
Retail investors bought about US$111m of Nvidia shares in the first half hour of trade, the biggest opening bid on record for the stock, according to Vanda Analytics (RT)
A Bloomberg Opinion column argued Brent’s near 25% slide over 10 days reflects traders seeing no immediate risk of renewed US-Iran fighting rather than pricing in peace (BBG)
Real Macro founder Jeffrey Currie expects near-term oil prices to stay tame as Middle East volumes return, though high insurance and tanker rates are keeping longer-dated futures elevated (CNBC)
Stocks
Nvidia’s market value fell below US$4tn for the first time since 2025 after CEO Jensen Huang resigned over two affairs, one with a suspected Chinese spy, with CFO Colette Kress named interim CEO. Shares sank as much as 14% to the lowest since June 2025, erasing up to US$601bn (BBG)
Anthropic’s planned record IPO faces fresh scrutiny after Huang’s exit, with Nvidia committed to buying about US$10bn of a US$26bn private placement priced alongside the float. Anthropic has set a US$70 to US$78 range targeting a valuation of up to US$1.4tn (BBG)
Broadcom and AMD rallied on bets Nvidia’s rivals could gain a competitive advantage, with their gains nearly offsetting Nvidia as the heaviest weight on the S&P 500, which AP said suggests investors see the AI business expanding beyond one supplier (AP)
Geopolitics
Trump said the US doesn’t need a deal with Iran as it holds Tehran’s frozen funds and the Strait of Hormuz, directing Vice President JD Vance to focus on alleged corruption in Democrat-run states (CNBC)
Iran’s military said four oil tankers were hit by explosions in the Strait of Hormuz after ignoring warnings, with at least 10 ships hit in the first 10 days of November (RT)
Jensen Huang agreed to testify behind closed doors before Congress following his exit over an affair with a suspected Chinese spy, House China committee chair John Moolenaar said (YF)
Tariffs
Trump threatened to immediately double tariffs on Mexican goods unless Mexico stops what he called migrant caravans heading for the US, ratcheting up trade tensions with a major partner (BBG)
Congressional Democrats plan early votes next year to roll back Trump’s tariffs, with Richard Neal, set to lead the House committee overseeing trade, saying the strategy is coordinated with his Senate counterpart (BBG)
The Huang scandal has revived a push for tighter China chip export curbs ahead of next week’s Trump-Xi summit in Shenzhen, with analysts warning Beijing could respond via rare earth and magnet controls (CNBC)
Central Banks
San Francisco Fed President Mary Daly said further rate hikes will likely be needed, citing consistent inflation pressure beyond sectors directly hit by tariffs or oil as businesses increasingly contemplate price rises (BBG)
Cleveland Fed President Beth Hammack said policy needs to move to a restrictive stance but saw no case for a faster pace of hikes, contrasting with Governor Christopher Waller’s openness to a half-point move (RT)
Chicago Fed President Austan Goolsbee said inflation is moving the wrong way in persistent categories such as services and healthcare, adding everything is on the table when asked about a half-point hike (TS)
Economy
US initial jobless claims rose 9,000 to 200,000 last week, above ests of 195,000, while the four-week average held at 195,250, with claims at or below 200,000 for nine straight weeks (AP)
US existing home sales fell to a 3.75m annualised pace in October, below ests of 3.85m and down from a downwardly revised 3.97m in September (investingLive)
UK economy grew 0.7% quarter-on-quarter in the third quarter, in line with ests and its strongest expansion in two-and-a-half years, driven partly by AI investment (RT)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Steel | 99.08 | -1.12% |
| Lithium & Battery Tech | 59.42 | -2.70% |
| Copper Miners | 71.005 | -3.29% |
| Uranium | 32.355 | -3.82% |
| Gold Miners | 81.88 | -3.91% |
| Silver Miners | 74.54 | -4.08% |
| Strategic Metals | 50.865 | -4.26% |
Industrials | ||
| Agriculture | 26.3 | -0.23% |
| Construction | 87.9299 | -1.55% |
| Aerospace & Defense | 71.82 | -1.94% |
| Global Jets | 29.055 | -3.76% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 213.43 | -2.16% |
Renewables | ||
| Hydrogen | 33.9891 | -3.25% |
| Solar | 42.335 | -3.67% |
Technology | ||
| Cloud Computing | 26.47 | -0.11% |
| Semiconductor | 154.99 | -0.26% |
| Data Center & Digital Infrastructure | 25.65 | -0.85% |
| Cybersecurity | 45.15 | -1.23% |
| Electric Vehicles | 28.92 | -2.00% |
| Robotics & AI | 31.42 | -2.51% |
| FinTech | 23.93 | -2.84% |
ASX Today
A very, very quiet morning so far for corporate updates
What To Watch Today
This section will be taking a break as Kerry is on leave for the next two weeks
Key Events
Stocks trading ex-dividend:
Fri 13 Nov: Dicker Data (DDR) – $0.115
Mon 16 Nov: Plato Income Maximiser (PL8) – $0.006, Spheria Emerging Companies (SEC) – $0.011, WAM Alternative Assets (WMA) – $0.03
Tue 17 Nov: Global Masters Fund (GFL) – $0.15, L1 Global Long Short Fund (GLS) – $0.02, L1 Long Short Fund (LSF) – $0.039, Solaris Australian Equity Income Plus (SET) – $0.007, WAM Active (WAA) – $0.032, WAM Income Maximiser (WMX) – $0.007, WAM Leaders (WLE) – $0.048
Wed 18 Nov: None
Thu 19 Nov: Rand Mining (RND) – $0.10, Tamawood (TWD) – $0.105, Tribune Resources (TBR) – $0.20
Other ASX corporate actions today:
Economic calendar (AEDT):
12:30 am: US PPI