ASX 200 Live Today - Wednesday, 5th August
The S&P/ASX 200 is set to open higher after the S&P 500, Dow and Russell 2000 all closed at record highs. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Wednesday, August 5. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Reporting season is heating up and we've got you covered. Our reporting season calendar has over 250 stocks plus earnings and dividend estimates.
ASX 200 scores its fifth all-time high of the year
[2:20 pm] That's a wrap! The S&P/ASX 200 is up 67 points (+0.78%), with Materials (+3.1%) grinding higher intraday, Tech (+2.6%) now on a six-day win streak and Financials (-0.4%) bouncing off session lows.
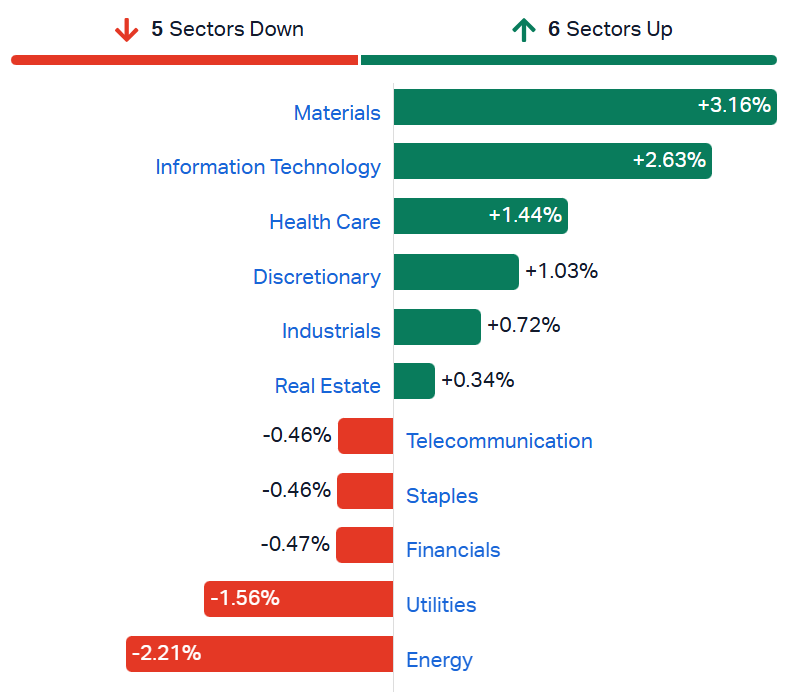
S&P/ASX 200 sectors (Source: Market Index)
Tuesday's session felt very strong, and today has been a resumption of that strength. That momentum may be driving some rotation out of defensives (Staples and Telcos are down) and banks (CBA fell as much as 3.0% intraday) into the more growth-oriented and cyclical pockets of the market.
Despite the ASX 200 printing all-time highs, the small end of town is only just catching a bid. The S&P/Emerging Companies Index has risen 8.5% over the last four sessions but remains down around 7% year-to-date, leaving plenty of catch-up potential for smalls. Put another way, the froth has yet to return to the speculative end. It nevertheless feels like a 'blue skies' moment for markets. Oil is easing (despite still-volatile US-Iran developments), yields are coming down, a sharp selloff across semis and AI-related plays has reset positioning and technicals, and US earnings season has been remarkably strong, with roughly 84% of reported S&P 500 companies beating expectations.
Heavyweight bank stocks have V-shaped in recent weeks to sit back near all-time highs, Discretionary names have bounced strongly (Wesfarmers is back at record levels), and BHP and Rio Tinto, having tilted their portfolios further towards copper in recent years, are benefiting from the soaring copper price.
Reporting season is starting to pick up steam, with REA Group, Block, Beach Energy and AMP due to report tomorrow.
Miners carry the index higher
[1:22 pm] A very strong day for the Materials index (+3.1%), offsetting the declines for Telcos (-0.5%), Staples (-0.5%), Financials (-0.8%), Utilities (-1.6%) and Energy (-1.7%). Some very constructive charts out there, against a backdrop where copper is up 0.2% today to US$6.70/lb, just 0.4% shy of its 2 June record high.
BHP is moving out after six weeks of choppy trade.
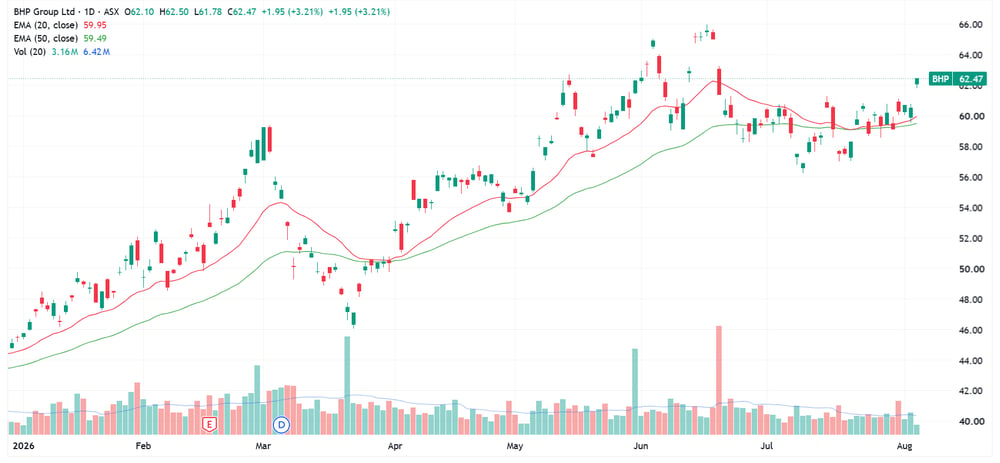
BHP daily price chart (Source: TradingView)
South32 is going to test a rather longstanding trading range, except this time, as a more copper oriented business (having announced plans to sell its aluminium assets to Alcoa for up to US$5.6bn back in July, and for this reason, probably why South32 has rallied the hardest in recent weeks, up ~24% since 17 July).
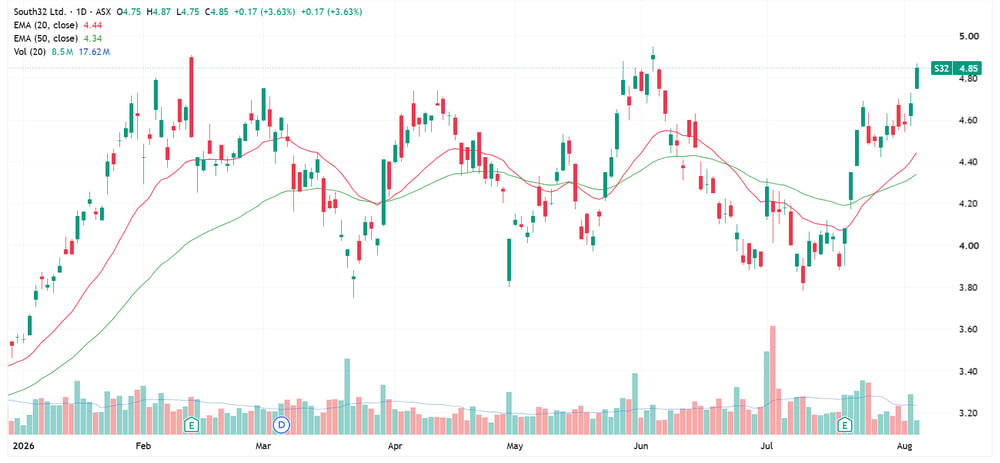
South32 daily price chart (Source: TradingView)
Newmont (and most other goldies) are trying to dig themselves out of a four-month long downtrend, now crossing above the key 50-and-200 day moving averages.
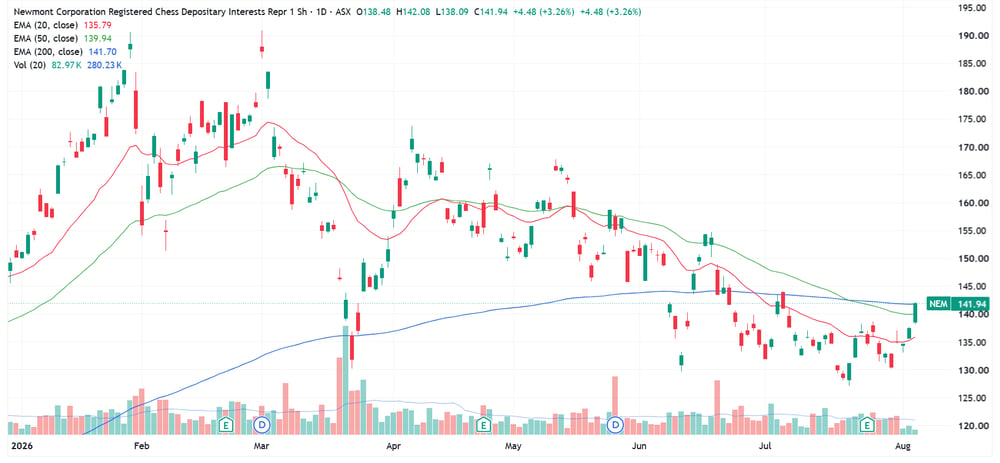
Newmont daily price chart (Source: TradingView)
Diggers and Dealers 2026: Key quotes from six presentations
[1:10 pm] Here's a round-up of the key comments from Astral Resources, Australian Strategic Materials, West African Resources, Wildcat Resources, Fenix Resources and Pinnacle across the forum's presentations.
Astral Resources (AAR):
On the DFS delay and its cause: "Our delay is actually linked to our ownership structure of the Mandilla Gold Project, and that is the nature of the tenure is split between where we own the gold rights but not the underlying tenure"
On project economics at current prices: "The payback on this $227 million development is six months. The internal rate of return is 170%. The net present value at an 8% discount rate is 2.5 billion"
On the share price and value gap: "From a share price perspective, we have copped a smack. It is absolutely disproportionate to the retracement in the gold price"
On funding position: "We have $65 million in the bank. We have line of sight on another $50 million from the J.V. and the combination of those will see us very well funded as we head into development"
Australian Strategic Materials (ASM):
On the strategic rationale for the Energy Fuels deal: "If both of these transactions progress a near term Western mine all the way through to magnet supply chain with direct access to energy fuels, deep competency in solvent extraction and operations in the States"
On its Korean metals capability and the China concentration it displaces: "Metalisation is over 95% concentrated in China. And so what we have established over this period in Korea with our facility here is a very unique capability"
On the offer premium: "The implied price is adequate premium to our pre-announcement share price... as of this morning it was a 44% premium"
On the risk balance for shareholders: "There are a lot of risks attached to this as well as a lot of opportunities"
West African Resources (WAF):
On scale and run rate: "We're on a 500,000 ounce per annum run rate, which is exceptional effort from our team" with "nearly 14 million ounces in resources, 7 million ounces in reserves"
On the balance sheet and capital management: "We've had very, very strong cash flow... over A$1 billion in cash in gold at the end of the June quarter. And we will look at either returning some of that back to shareholders or buying back shares"
On the government's move to acquire more of Kiaka: "The government realised we did such a magnificent job building Kiaka they'd like to have another 25% of it... the government's determined that they will pay us $185 million for 25% of Kiaka"
On Kiaka's upside versus budget: "We have had days where Kiaka is done over 40,000 tonnes... Currently our budgets are at 10 million tonnes per annum. I think with some tweaking we can get Kiaka up to 12 to 14 million tonnes per annum"
Wildcat Resources (WC8):
On the scale of the asset: Pepper Tabbah is "74.1 million tonnes, which is the largest undeveloped lithium project in Australia"
On cost position and margin: "Our operating costs are about $541. Our C1 operating costs and our all in sustaining costs are about $658 at today's lithium price of $2000, that some significant margins to be made"
On project economics: "Our NPV at 2000 is about $2.9 billion post-tax free cash flow of about $6.5 billion post-tax and an IRR of 40%... a payback period of 1.7 years"
On exploration track record: "We've had three discoveries in three years"
Fenix Resources (FEX):
On the growth ambition: "Our ambition is to be a 10 million tonne a year producer... to be the new Western force in iron ore"
On cost discipline versus peers: "We've brought our cost down almost 20% since we started production. All the other iron ore miners have gone up more than 20% over the same area"
On the pathway to lower costs at scale: "At the moment we're targeting 75 AUD FOB. The scoping study identified a pathway to $55 FOB. Times that by 10 million tonnes"
On rewarding shareholders without dilution: "We haven't raised any equity since we raised the $15 million we need to build this mine... we've paid back more than $75 million in fully franked dividends"
Brokers stay cautious on Credit Corp as US buying pullback overshadows record profit
[1:02 pm] Credit Corp's FY26 result on Tuesday came in broadly in line, with net profit hitting a record as strength in the US PDL business offset a softer lending contribution, though the print was overshadowed by US purchasing guidance sitting well below market expectations. Shares whipsawed, rising as much as 4.8% before reversing to close 7.0% lower after falling as much as 11.4% intraday
Morgans maintained Buy, lowered target from $19.15 to $18.25: viewed the result as in line but the investment outlook as the more negative signal, with US growth still central to the thesis and efficiency gains seen offsetting the weaker purchasing outlook.
Canaccord Genuity maintained Buy, raised target from $19.70 to $19.80: saw the ledger investment guidance as a disappointment but little changing in the underlying lending story, with improving AU/NZ debt buying returns and a valuation still viewed as undemanding given the growth outlook.
JPMorgan maintained Overweight, lowered target from $19.60 to $18.60: saw valuation as supported after recent weakness and the US purchasing step-down as market driven, cautioning that delivering guidance without an improved outlook risks stagnation while viewing the consumer lending business as underappreciated.
Macquarie retained Outperform, lowered target from $13.83 to $13.34: sees Credit Corp as a disciplined operator, "with solid consumer lending momentum, better US collections and resilient AU/NZ market. While visibility on FY27 PDL remains mixed, at ~8x PE, valuation is attractive."
SK Hynix rallies on shareholder return hopes
[1:01 pm] SK Hynix shares jumped as investors bet on an imminent buyback and shareholder return announcement, helped by an overnight rally in US chipmakers.
SK Hynix rose as much as 7.9% in Seoul, outpacing Samsung's 6% gain, with the Kospi up nearly 5% in morning trade
Optimism centres on the 25-day US quiet period ending August 4, following its July 10 ADR sale, expected to clear the way for shareholder return disclosures
Analysts expect a program combining buybacks, share cancellations and special dividends
The stock had fallen nearly 10% on its July 29 earnings call when it flagged but did not detail a return program
In April it pledged expanded 2026 returns alongside a goal of 100 trillion won ($70.2bn) in net cash
Source: Bloomberg
Centuria Office REIT rebases dividend, but gearing keeps brokers cautious
[12:26 pm] Centuria Office REIT's FY26 FFO per share result landed in line with estimates and consensus, though FY27 guidance was mixed and the dividend was rebased lower as management moved to align distributions closer to underlying cash earnings, sending shares 2.2% lower on Tuesday.
Bell Potter maintained Sell, target unchanged at $0.85: viewed the dividend rebase as prudent but flagged the payout still exceeding underlying cash earnings, with elevated gearing and the planned asset sale seen as the key downside risk despite encouraging Queensland leasing.
UBS maintained Neutral, lowered target from $0.90 to $0.88: welcomed the payout reset but saw it as insufficient given little interest cover headroom, with further divestments needed to ease leverage and the valuation viewed as undemanding pending balance sheet progress.
Australian industry stays weak as energy crisis grinds on
[12:25 pm] The Australian Industry Index held at -29.9 in July as pricing pressures eased slightly but activity, orders and employment stayed firmly in contraction.
Australian Industry Index steady at -29.9 (seasonally adjusted), still signalling clear weakness
Pricing indicators stabilised after three months of energy-driven highs, though prices remain structurally elevated
Activity and new orders contraction stabilised, but the employment indicator fell again to -23.0 on the lagged impact of the crisis
Manufacturing PMI fell 5.7 points to -19.6 while construction PCI dropped 7.3 points to -40.6, a sixth straight month in contraction
Uncertainty was the most cited business impact at 18%, driven by fuel price volatility and geopolitical developments
Global energy prices rose again in late July, so cost and uncertainty pressures are likely to re-emerge in August
Source: Ai Group Industry Inde
Miners rally as copper nears all-time high and gold prices bounce
[11:47 am] The S&P/ASX 200 Materials index is up 2.42% to the highest since 23 June. The index is now up 8.0% since the 20 July low, but still 7.7% away from the 17 June record high.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
BHP | BHP Group | 2.5% | $62.05 | 4.37% | 36.27% |
RIO | Rio Tinto | 1.4% | $174.75 | 7.4% | 19.0% |
FMG | Fortescue | 0.2% | $18.12 | -3.8% | -17.6% |
NST | Northern Star Resources | 3.1% | $20.95 | 3.5% | -14.7% |
EVN | Evolution Mining | 2.8% | $12.11 | 5.0% | -3.7% |
S32 | South32 | 2.4% | $4.79 | 5.7% | 34.9% |
BSL | Bluescope Steel | 0.6% | $34.01 | 4.6% | 41.3% |
LYC | Lynas Rare Earths | 5.7% | $15.82 | 9.1% | 27.5% |
PLS | PLS Group | 1.8% | $4.36 | 7.8% | 3.7% |
MIN | Mineral Resources | 2.1% | $60.61 | 10.2% | 11.4% |
UBS calls Pinnacle's FY26 a messy beat on flows, miss on profit
[11:05 am] UBS says stronger FUM and 4Q flows should support the FY27 outlook, but underlying 2H profit missed materially.
2H underlying NPAT of $63m came in around 22-25% below consensus and UBS
Reported FY26 NPAT of $176.7m included a $46m PAM step-up revaluation gain, leaving headline NPAT of $130.5m ex-item
Three factors drove the profit miss: rising PNI parent costs ex-PAM, performance fees earned in affiliates with higher staff pass-throughs, and an effective 2H P&L share of ~37% versus FUM share of ~40%
Jun-26 FUM of $229.4bn ran ~1% ahead of UBS and consensus, with 4Q net inflows of $6.8bn beating UBS at $6.5bn and consensus at $5.5bn
Notable FUM performers included PAM up 20% half-on-half, LifeCycle up 42% to $42bn and Metrics up 10%
Price target held at $18.00, with FY26 and FY27 EPS cut 3% each, PNI trading on 17.8x NTM, a 24% PE-relative discount to its 5-year average
Banks tumble with only rotation to blame
[10:56 am] The S&P/ASX 200 Financials index is trading 1.1% lower, with a notable 2.4% tumble for Commonwealth Bank.
What's driving the selloff, on a day where the index is testing all-time highs?
Financials index closed at record highs on Tuesday, so perhaps profit taking/pullback dynamics at play
Materials sector (+2.3%) catching a strong bid, with BHP (+2.4%). Perhaps some rotation from banks to resources?
Last year, I write a piece about how CBA selloffs often coincide with BHP outperformance/rallies
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
CBA | Commonwealth Bank | -2.46% | $176.27 | -1.49% | 9.76% |
ANZ | ANZ Group | -1.44% | $37.62 | 0.59% | 3.21% |
NAB | National Australia Bank | -1.28% | $42.30 | 3.02% | 0.07% |
WBC | Westpac | -1.24% | $38.34 | 1.48% | -0.42% |
BEN | Bendigo & Adelaide Bank | -0.96% | $11.40 | 1.97% | 7.65% |
BOQ | Bank Of Queensland | -0.74% | $6.68 | 1.52% | 1.83% |
MQG | Macquarie Group | 0.52% | $264.57 | 3.35% | 30.33% |
JDO | Judo Capital | 1.95% | $1.05 | 9.42% | -41.29% |
Light & Wonder Q2 call: Recurring revenue and a second-half skew
[10:54 am] Key comments from Light & Wonder's Q2 call led by CEO Matt Wilson and CFO Oliver Chow.
On FY26 guidance: "Given our visibility to year-end, I have a high degree of confidence in achieving our targeted mid to high single digit consolidated AEBITDA growth outlook for 2026"
On recurring revenue and margins: the margin uplift "was less about cost out and more about, you know, an intentional mix shift towards recurring revenue"
On gaming ops yield: "7%, I think it was 8% in the prior period. That's exceptional industry-leading yield expansion" while "moderating expectations a little bit on that line as we continue to scale the install base"
On deleveraging: "the focus will be to rapidly de-lever our balance sheet for the remainder of the year and into the first half of 2027"
On gaming machine sales timing: "there was some deferral of new openings from the second quarter into the second half. So we've got line of sight on those. They're contracted"
Pinnacle FY26 call: Four drivers underpin FY27 growth
[10:49 am] Key themes from Pinnacle's FY26 results call led by MD Ian Macoun.
On FY27 growth drivers, four factors were flagged: a full year of 100% PAM ownership versus two months in FY26, closing FUM sitting 14% above the FY26 average, affiliate margins before performance fees up 10%, and the 50% uplift in Pinnacle parent revenue annualising
On performance, 81% of five-year affiliate strategies outperformed, down from an exceptionally high 91% a year ago, as quality and growth styles hit headwinds
On international, roughly one-third of the $229.4bn FUM is now from clients outside Australia, with management calling replication of its domestic wholesale/retail strength offshore an inflection point
On PAM, run-rate earnings have grown from £9.4m per annum at initial purchase to £17.9m at 100% ownership, with the US SMA and model portfolio market flagged as a major opportunity
On Life Cycle, FUM reached the equivalent of $42.4bn in under two-and-a-half years, with substantial capacity still remaining across its strategies
ASX 200 tests all-time highs, Total returns at record highs
[10:20 am] The S&P/ASX 200 is up 52 points (+0.58%) in early trade, and within ~2 points of the 2 March record close (9,200).
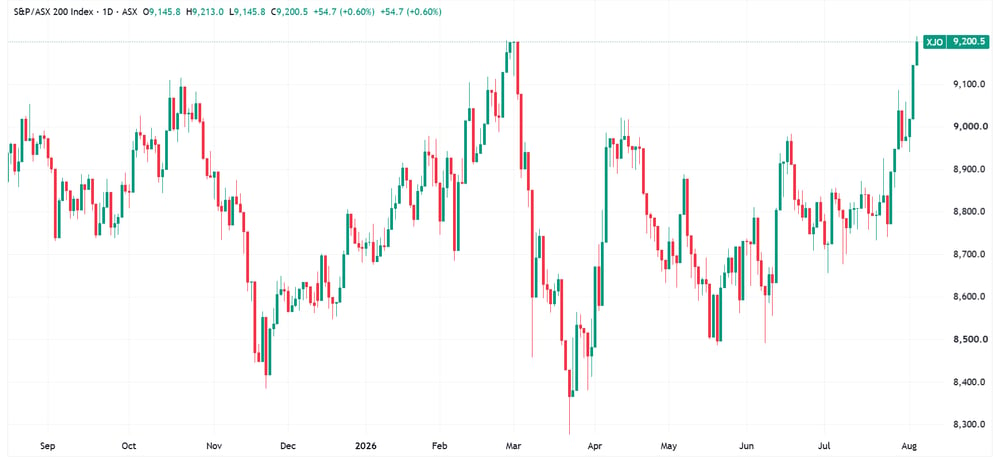
S&P/ASX 200 daily chart (Source: TradingView)
On a total returns basis, the ASX 200 cleared the 2 March record high on Tuesday.
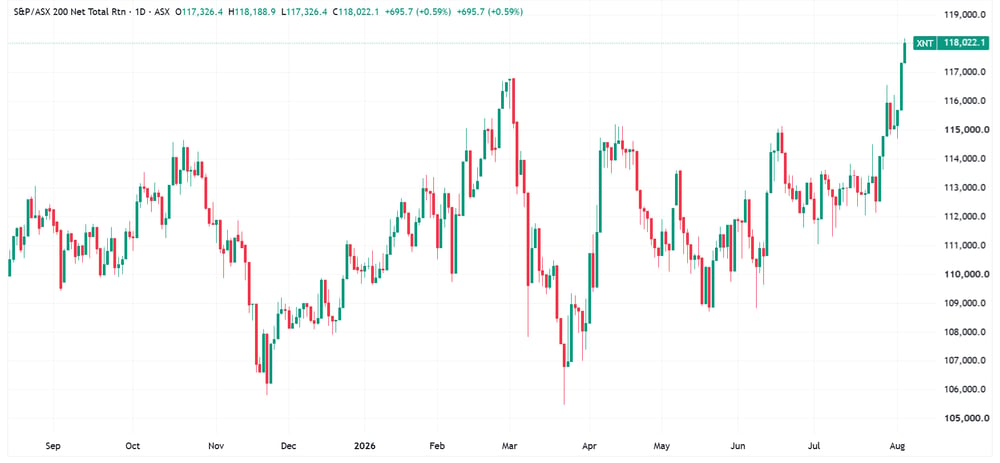
S&P/ASX 200 Total Returns daily chart (Source: TradingView)
Top ASX 200 gainers and losers
[10:17 am] Neuren soars on an earnings upgrade, while copper, rare earths, uranium and software stocks open broadly higher. Meanwhile, US-Iran war beneficiaries like oil, refiners and defensives slip in early trade.
Ticker | Company | % Chg | Price |
|---|---|---|---|
NEU | Neuren Pharmaceuticals | 16.17% | $21.62 |
IPX | Iperionx | 6.71% | $3.34 |
LYC | Lynas Rare Earths | 5.05% | $15.72 |
4DX | 4DMedical | 4.88% | $4.51 |
CSC | Capstone Copper Corp | 4.68% | $14.76 |
PDI | Predictive Discovery | 4.58% | $0.69 |
SLX | Silex Systems | 4.46% | $5.04 |
360 | Life360 | 3.76% | $29.54 |
ZIP | Zip Co | 3.72% | $2.79 |
FFM | Firefly Metals | 3.54% | $1.76 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
WDS | Woodside Energy Group | -2.79% | $32.03 |
KAR | Karoon Energy | -2.29% | $1.71 |
EDV | Endeavour Group | -2.01% | $3.41 |
KCN | Kingsgate Consolidated | -1.96% | $4.01 |
STO | Santos | -1.74% | $7.63 |
NHC | New Hope Corporation | -1.65% | $5.06 |
BPT | Beach Energy | -1.64% | $0.90 |
APA | APA Group | -1.55% | $10.14 |
TLS | Telstra Group | -1.38% | $5.01 |
ALD | Ampol | -1.24% | $38.28 |
Neuren's DAYBUE sales climb 30% as Acadia lifts guidance
[10:08 am] Neuren posted strong Q2 DAYBUE royalty growth and upgraded full-year guidance on the back of Acadia's raised sales outlook. The stock is up 14.5% to $21.31, at the time of writing.
DAYBUE net sales up 30% to US$125m in Q2
Royalty income up 34% to $12.9m
Acadia lifted FY26 DAYBUE net sales guidance 4% to US$480-510m from US$460-490m at the midpoint
Implies Neuren royalty income up 5% to US$53-56m from US$50-54m at the midpoint
Acadia reaffirmed its 2028 target of US$700m DAYBUE net sales
Germany launch expected early Q4 pending EC approval, with the Japan trial readout on track for Sep-Nov
Company page: Neuren Pharmaceuticals (NEU)
Copper within 1% of all-time highs
[9:50 am] Copper prices rallied as much as 2.1% overnight to a record high of US$6.74/lb but finished the session up 1.28% to US$6.68/lb.
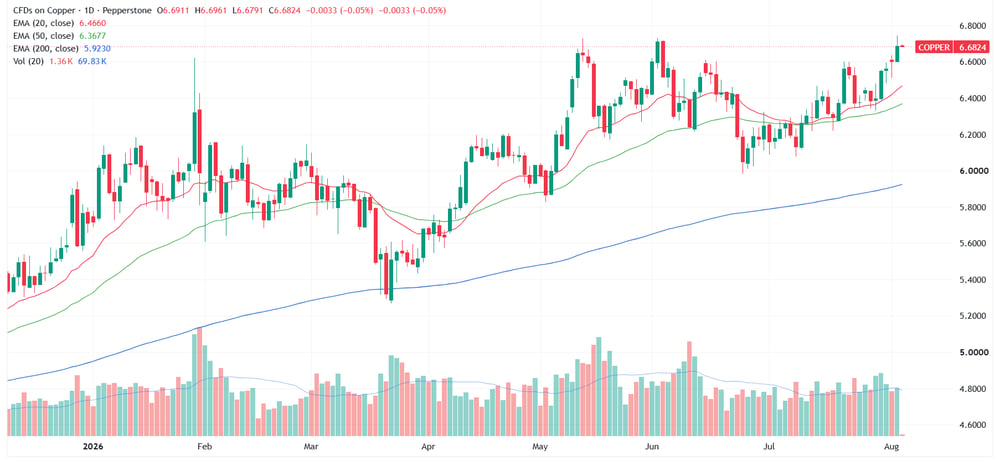
Copper daily price chart (Source: TradingView)
This drove copper equities broadly higher, with a barometer like the Global X Copper Miners up 5.8%.
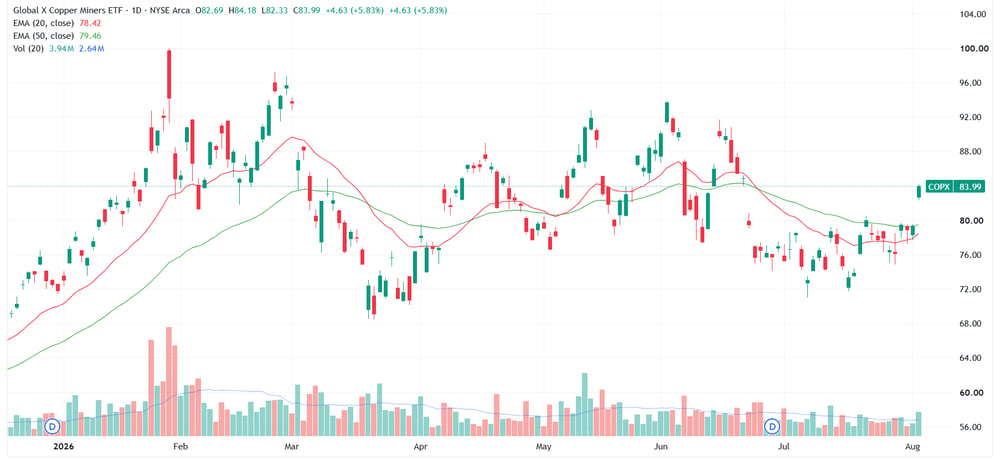
NYSE-listed Global X Copper Miners ETF daily chart (Source: TradingView)
Some interesting comments from a slightly dated Cannacord note (20-Jul) which noted: " Copper prices have remained relatively robust, even as the physical market remains relatively tepid and surplus exchange inventories remain near two-decade highs."
"We believe the ambiguity is serving to maintain a speculative element in pricing, along with a still-strong narrative around data centre construction. We note that the copper equities do not buy this narrative — over the last month, the copper producers in our coverage universe have declined by 13% as a group even as the copper price has remained relatively range-bound."
Want the highlights from Diggers and Dealers?
[9:40 am] I've got a few transcripts from the Diggers and Dealers Mining Forum in Kalgoorlie (CMM, ASM, FEX and more). Let me know if you'd like us to cover the key takeaways/themes from the presentations.
Monadelphous wins $200m BHP port contract
[9:32 am] Monadelphous has secured a major construction contract with BHP at its Nelson Point port facility in Port Hedland.
Contract valued at around $200m for the Port Debottlenecking Project 2 (PDP2)
Covers structural, mechanical, piping, electrical and instrumentation work for the new Car Dumper 6 and supporting materials handling facilities
Work commences immediately with completion expected in 2028
Company page: Monadelphous Group (MND)
Endeavour flags in-line FY26 guidance and $372m of write-downs
[9:28 am] Endeavour Group pre-released FY26 guidance broadly in line with ests, alongside a large slate of mostly non-cash significant items from its strategy review.
Total group sales up 1.3% to $12.21bn vs $12.19bn ests (in line)
Underlying EBIT down 8.7% to $845m vs $847.0m ests (in line)
Underlying NPAT down 14.7% to $363m vs $366.3m ests (1% miss)
$372m of pre-tax significant item expenses ($311m after-tax), predominantly non-cash
Write-downs span Pinnacle wineries and vineyards ($78m), 25 hotels ($67m) and 75 retail stores ($45m)
A $40m provision recognised on cessation of the Woolworths MLDC supply chain contract in September 2028
Endeavour shares are down 5.4% year-to-date and down 13.8% in the last twelve months, though up around 21% since its 2 June all-time low.
Company page: Endeavour Group (EDV)
Light & Wonder Q2 EBITDA beats, tracking ahead of UBS forecasts
[9:19 am] Light & Wonder posted 9% adjusted EBITDA growth with margin expansion across all three segments, coming in above both consensus and UBS's forecast.
Revenue up 2% to $828m vs $842.4m ests (2% miss)
Consolidated AEBITDA up 9% to $383m vs $366.2m ests (5% beat) and 2% ahead of UBS ests of $375m
EPS of $1.53 vs $1.23 ests (24% beat)
Adjusted free cash flow up 50% to $156m vs $110.1m ests (42% beat)
Gaming operations revenue up 18% to $247m, with the premium installed base extending growth to a 24th straight quarter
iGaming revenue up 14% and AEBITDA up 18% despite UK tax increases
UBS flagged that FY26 guidance for mid-to-high single digit AEBITDA growth was reiterated in mid-July, and the ~8% share price reaction that day showed the market's earnings-risk sensitivity. The Q2 result leaves the company well placed against UBS's full-year estimate, which is looking for 6% growth over the remainder of 2026. UBS reiterated a Buy rating on 28 July, calling LNW the strongest shareholder return in its gaming coverage and flagging its ~60% PE discount to Aristocrat.
Company page: Light & Wonder (LNW)
Credit Corp FY26 call: US recovery and a UK runway
[9:12 am] Here are the key themes and takeaways from CEO Thomas Beregi on the FY26 results call.
The result was announced on Tuesday. Credit Corp shares tanked (6.9%) despite rallying ~5% in early trade, the FY26 result was relatively in-line with expectations, though FY27 US purchasing guidance was very soft.
On US collections: "we're not seeing degradation in any of those underlying metrics" with delinquency and repayment conversion "relatively static and have been static since that experience in 2023"
On the US consumer: "the consumer in the US still seems to be hanging in there" and "still reasonably positive about their prospects to maintain their employment"
On US purchasing competition: "we've seen recently a couple of large retendering processes where we were outbid, and we couldn't see a way for us to bid the winning prices and still deliver returns"
On Wizard growth: it "accounted for 17% of our new customer volume as a new product in the year just gone" with plans to "close to double it over the year ahead"
On the UK opportunity: "a market more than 5 times the size of Australia and no real dominant competitor in that market and an underserved situation"
On the outlook: "all segments of the business produced growth, and it's been about five years since we've seen a result like that"
Company page: Credit Corp Group (CCP)
Experience Co Q4 EBITDA slips on weather and fuel costs
[9:01 am] Experience Co posted flat Q4 revenue but a sharp drop in underlying EBITDA as weather, fuel and cost pressures weighed.
Revenue up 1% to $29.4m from $29.2m
Underlying EBITDA down 31% to $2.0m
Adventure experiences up 5% to $15.2m, offsetting skydiving down 3% to $14.2m
Fuel costs rose to ~6.5% of Group revenue from ~4% before the Middle East conflict
Softer April on weather impacts, with May and June broadly in line with pcp
All business units except Skydive Australia grew revenue across FY26
Company page: Experience Co (EXP)
Pinnacle FY26 underlying NPAT up 21%
[8:54 am] Pinnacle delivered strong FUM and net inflow growth in FY26, though underlying earnings came in below consensus.
Underlying NPAT up 21% to $138.0m vs $148.0m ests (7% miss)
Statutory NPAT up 31% to $176.7m, boosted by a one-off gain on the PAM acquisition
Underlying diluted EPS up 15% to 61.0 cents
FUM up 28% to $229.4bn, with net inflows of $33.4bn ($16.3bn in 2H)
Performance fees contributed $35.6m post-tax, down from $46.6m in FY25
Final DPS of 31.0 cents franked to 65%, taking full-year dividends to 60.0 cents, flat on FY25
The full-year dividend is relatively in-line with consensus. Net inflows for the second half of $16.3bn tracking ahead of Macquarie ($14.2bn or 15% beat) and Morgans ($15.2bn or 7% beat). Performance fees also tracking above consensus of $30m (or a ~18% beat).
Company page: Pinnacle Investment Management Group (PNI)
Australian household spending beats in June as EV sales jump
[8:49 am] We missed this data point yesterday, where Aussie household spending rose 0.8% in June, well ahead of the 0.2% consensus, as strong vehicle and travel spending pointed to resilient demand despite higher rates.
Household spending up 0.8% to $81.3bn in June vs 0.2% ests
Follows a 1.2% rise in May and a 1.0% fall in April
Annual spending growth accelerated to 6%, a three-month high
Transport led the gains with new vehicle sales up 3.0%, EVs taking a growing share as households respond to high petrol prices
Air travel spending returned to pre-conflict levels while fuel volumes rose 7.8% on a 10.9% drop in prices
June quarter spending volumes rose 0.7%, up 2.4% year-on-year, a third straight quarterly gain
Source: ABS
Oil slides below US$80 as Hormuz deal hopes build
[8:44 am] Brent tumbled for a second straight day as Qatar, Bessent and Rubio all signalled a short-term US-Iran deal to reopen the Strait of Hormuz could be imminent.
Brent fell 6% to US$78.67 a barrel, below US$80 for the first time in over three weeks as deal optimism grew
Bessent told CNBC a deal to open the strait could come "today or tomorrow", with freedom of movement and no toll
Qatar said a de-escalation proposal has been drafted and is circulating between the parties, with Rubio also upbeat
Iran is privately weighing letting European nations clear mines from the strait, a climbdown from its public stance
Trump gave Iran a "last chance" to agree, threatening renewed airstrikes after calling off major attacks over the weekend
Korea's leveraged ETF frenzy cools sharply under new curbs
[8:43 am] Trading in leveraged single-stock ETFs tied to Korea's chip giants has slumped after regulators moved to rein in speculative retail demand.
Kodex SK Hynix single-stock ETF, the country's largest, saw volume fall to 59m shares Monday, the lowest since 4 June
The Samsung Electronics-linked peer had its quietest session since launching in late May
From 31 July, the minimum cash deposit for leveraged ETF trading was lifted to 30m won ($21,065) from 10m won, with new single-stock listings temporarily suspended
Margin loan balances fell to 28.9 trillion won as of 31 July, the lowest since January
The Kospi remains up around 48% this year but volatility stays elevated, with trading halted four times in July
Source: Bloomberg
Booking beats on resilient travel demand
[8:42 am] Booking Holdings posted a Q2 beat across revenue, earnings and margins as travel demand held up despite macro uncertainty.
Revenue up 8% to $7.4bn vs $7.19bn ests (3% beat)
Adj EPS up 15% to $2.54 vs $2.45 ests (4% beat)
Net income up 118% to $2.0bn vs $1.89bn ests (6% beat)
Adjusted EBITDA up 9% to $2.6bn vs $2.56bn ests (2% beat)
Gross bookings up 9% to $51.0bn and room nights up 5% to 325m
Free cash flow up 16% to $3.6bn vs $2.93bn ests (23% beat)
AMD smashes Q2 with data centre revenue more than doubling
[8:41 am] AMD delivered record revenue and profitability as data centre sales surged, with a Q3 guide well ahead of ests. The stock is still down ~9% after hours despite the clean beat.
Revenue up 50% to $11.5bn vs $11.28bn ests (2% beat)
Adj EPS up 246% to $1.66 vs $1.62 ests (2% beat)
Data Center revenue up 107% to $6.72bn
Non-GAAP net income up 253% to $2.76bn vs $2.64bn ests (5% beat)
Adjusted EBITDA of $3.3bn vs $3.37bn ests (2% miss)
Q3 revenue guide of ~$13.0bn vs $12.5bn ests (4% beat)
SpaceX Q2 revenue jumps 92% with EBITDA nearly tripling
[8:40 am] SpaceX posted a strong Q2 as connectivity and AI segments drove a big beat on revenue and profitability, alongside a narrower-than-expected loss. The stock is down ~6.0% after hours.
Revenue up 92% to $7.8bn vs $6.93bn ests (13% beat)
EPS of -$0.09 vs -$0.26 ests (loss narrower than expected)
EBITDA up 191% to $3.5bn vs $2.03bn ests (72% beat)
Net income of -$541m vs -$1.94bn ests (loss well narrower than expected)
Connectivity revenue up 66% to $4.3bn and AI revenue up 247% to $2.6bn
Starlink subscribers doubled to 12.0m though ARPU fell 22% to $66/mo
Caterpillar hits record quarter with revenue topping $20bn
[8:39 am] Caterpillar delivered its first-ever $20bn+ sales quarter, comfortably beating on revenue and earnings as all three primary segments grew. The stock rallied 5.6% overnight.
Revenue up 24% to $20.54bn vs $19.3bn ests (6% beat)
Adj EPS up 73% to $8.17 vs $6.20 ests (32% beat)
Operating profit up 50% to $4.3bn vs $3.6bn ests (19% beat)
Adj operating margin up 430bps to 21.9%
Construction Industries up 35% to $8.35bn and Resource Industries up 20% to $4.65bn
Enterprise operating cash flow of $4.4bn, with $1.5bn buybacks and $0.7bn dividends
Management flagged strong order rates and a growing backlog across all three primary segments. Power & Energy rose 17% to $8.24bn and Financial Products rose 10% to $1.15bn.
Goldman's Callahan flags a V-shaped snapback in tech
[8:38 am] Goldman's Peter Callahan says the Nasdaq 100 has staged a sharp recovery, rebounding above a key technical level in just four sessions.
NDX up around 945bps in four sessions since last Thursday, punching back above its 50-day moving average
The four-day move ranks alongside how tech traded around major events over the past 20 years including the GFC, COVID, the 2022 hiking cycle and Liberation Day
Cleaner positioning and improved technicals behind the bounce, helped by a momentum factor rebound and reduced leveraged ETF footprints
Stronger fundamentals and visibility, including improved ROIC sentiment after last week's earnings
Investor questions centre on whether it is a squeezy or hated rally, signs of re-risking, and semis versus hyperscalers
Citadel Securities says bull market drivers remain "firmly intact"
[8:35 am] Citadel Securities' Scott Rubner argues the forces behind US stocks' record highs are still in place after a reset in retail speculation.
"July did not change the structural bull market. It reset it," Rubner said, adding investors can now focus more on company fundamentals than positioning.
Markets are shifting from a flow-driven backdrop back to one led by earnings, corporate demand and macro, per Rubner
Retail investors posted their biggest week of stock selling since 2022, concentrated in tech names
Leveraged ETF assets fell 28% to $154bn as the retail retreat unwound speculative "excesses"
Equity financing costs have dropped, signalling less pressure on trading desks and softer demand for leverage
Earnings continue to surprise to the upside while valuations have grown more attractive
Corporate buyback demand is set to accelerate as earnings blackout windows expire
Good morning!
[8:27 am] ASX 200 futures are up 41 pts (+0.45%). The overnight session in a nutshell:
S&P 500 logged its first record close in two months and the Dow cleared 54,000 for the first time, a fourth straight advance led by chips and AI infrastructure
S&P 500 (+1.79%), Dow (+1.71%), Nasdaq (+2.59%) and Russell 2000 (+1.85%)
Brent fell ~6% to US$78.67 after Treasury Secretary Scott Bessent said a Strait of Hormuz deal could land within a day, unwinding July's war premium
Strong session for commodities, with copper (+1.2%) trading within 0.4% of all-time highs, while rare earths, uranium, silver and nickel equities rallied 3-5%
Earnings carried the tape, with Palantir, Caterpillar and Wayfair all beating and lifting guidance, though AMD and SpaceX both sold off after the bell