ASX 200 Live Today - Thursday, 23rd July
The S&P/ASX 200 is trading higher as resources, REITs and utilities trade sharply higher. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Thursday, July 23. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 at a one-month high
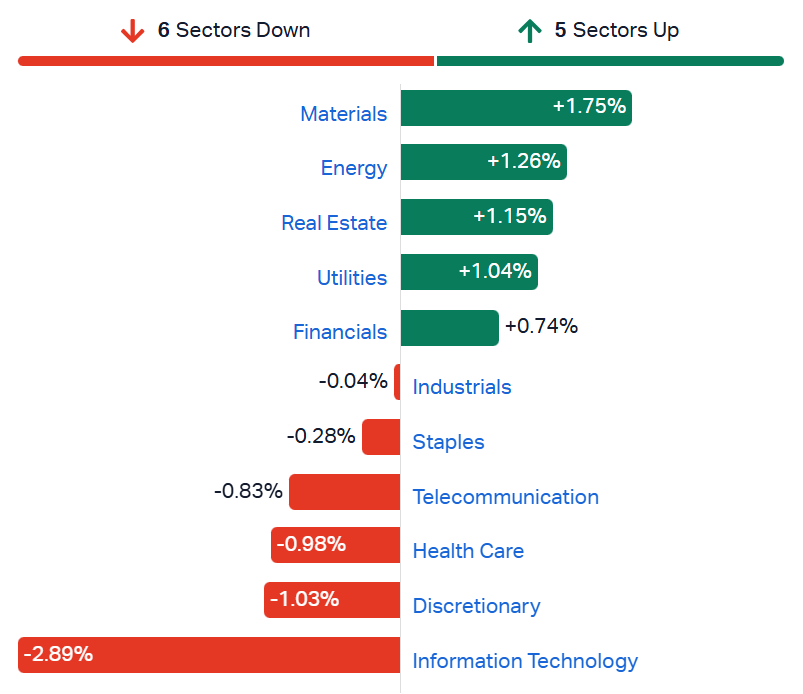
[2:05 pm] The S&P/ASX 200 is currently up 0.55%, down from session highs of 1.17%. The intraday weakness reflects a continued weakness for tech and discretionary through the session, while financials, real estate and utilities giving back some of their gains.
S&P/ASX 200 sectors (Source: Market Index)
Overall, the market remains choppy at best. Index strength reflects a three-day bounce for materials after a ~15% pullback in recent weeks, alongside a steady grind higher for financials, up 8.5% since mid-June. Healthcare put in a rather surprising 23% move from the 3-June low to 7-July, but is now on a five-day losing streak and down 6.8% from its recent peak. Discretionary is still holding onto most of its gains since the 12-May low, up 19.8%, though it too has slipped into a three-day losing streak. So plenty of volatility beneath the surface. Oil prices continue to climb, with Brent up 0.70% today to US$96.16 a barrel, now 35.0% higher since 1 July. That's placing upward pressure on bond yields, with the Aussie 10-year trading with a five-handle again and the US 10-year crossing 4.66%. There's not much chatter about yields yet, but at such uncomfortable levels it won't stay quiet for long. That's all for today.
Macquarie starts FY27 solidly with succession in focus, UBS says
[1:58 pm] UBS keeps a Neutral rating and $250 target, sitting 6% below consensus on the strong start.
CEO succession is the main focus after Shemara Wikramanayake departs following a record FY26, with UBS viewing the transition as occurring from a position of operational strength.
Run rating at ~$0.9bn for Q1 27 as a profitability proxy, up substantially on a weak Q1 26 but behind the record Q4 26 print, with the usual 45/55% 1H/2H split still guided for the full year.
Banking and Financial Services: short-term outlook trimmed on market conditions and customer activity, likely reflecting budget impacts on investor mortgage growth, with Ben Perham now leading the division.
Commodities and Global Markets: earnings contribution rose on American gas and power trading during the January US cold snap, though the division's ~40% share of group earnings remains a volatility risk.
Valuation stretched at ~19.2x P/E versus a long-run average of ~14.0x, with consensus forecasting ~$4.9bn FY earnings (+5% year-on-year).
Company page: Macquarie Group (MQG)
Copper stocks broadly higher
[1:56 pm] Another solid day for copper names, as copper prices recoup Wednesday's 0.5% decline, up by the same amount at the time of writing.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
29M | 29Metals | 10.6% | $0.26 | 10.6% | -50.6% |
AIS | Aeris Resources | 6.5% | $0.41 | 2.5% | -31.7% |
SFR | Sandfire Resources | 4.9% | $19.61 | 3.8% | 9.2% |
CSC | Capstone Copper | 2.6% | $13.73 | 1.9% | -9.4% |
FFM | Firefly Metals | 2.4% | $1.82 | -0.7% | -11.6% |
AR1 | Austral Resources Australia | 1.5% | $0.07 | 8.1% | 17.5% |
BHP | Bhp Group | 1.5% | $60.64 | 0.1% | 33.2% |
RIO | Rio Tinto | 0.9% | $163.41 | -0.9% | 11.3% |
HCH | Hot Chili | 0.7% | $1.55 | -2.5% | 11.2% |
CYM | Cyprium Metals | 0.0% | $0.44 | 3.6% | -17.8% |
HGO | Hillgrove Resources | -3.3% | $0.06 | -9.2% | 22.9% |
MC2 | Marimaca Copper | -5.9% | $7.21 | -7.2% | -42.3% |
Lithium stocks bounce
[1:16 pm] Lithium stocks are trading broadly higher, with most names up 4-6%. Chinese lithium carbonate futures opened slightly higher this morning, now up 4.2% to 147,380 yuan a tonne. Prices are still down around 3.4% for the past week, with most lithium miners also tracking lower for the week.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
CXO | Core Lithium | 8.3% | $0.26 | 0.0% | -5.5% |
INR | Ioneer | 6.1% | $0.12 | -9.6% | -34.1% |
LTR | Liontown | 6.1% | $1.31 | -7.4% | -16.6% |
EUR | European Lithium | 5.3% | $0.30 | -9.1% | 93.5% |
PMT | Pmet Resources | 4.9% | $0.47 | -7.5% | -21.5% |
PLS | PLS Group | 4.5% | $4.34 | -5.3% | 3.2% |
IGO | IGO | 3.7% | $6.95 | -0.2% | -15.2% |
MIN | Mineral Resources | 3.4% | $55.44 | -7.2% | 1.9% |
VUL | Vulcan Energy Resources | 1.9% | $2.69 | -4.6% | -39.0% |
GL1 | Global Lithium Resources | 1.0% | $0.51 | 8.6% | -19.8% |
DLI | Delta Lithium | 0.0% | $0.16 | -5.9% | -27.3% |
Morgan Stanley names SiteMinder a key pick into reporting season
[1:15 pm] Morgan Stanley has flagged SiteMinder as its second key small/mid-cap idea into August results, citing earnings delivery, scope for FY27 growth acceleration and easing fears of AI disruption.
Expects FY26 earnings delivery, with the absence of a trading update suggesting VA consensus EBITDA of $29.9m is realistic despite FX headwinds and Middle East conflict, in contrast to downgrades elsewhere in travel
Sees FY27 re-acceleration, with consensus at 23% revenue growth versus 22% in FY26, and upside from DR+ upsell and the Mews deal, saying delivery of an in-line or accelerating outlook is "very realistic"
Argues AI displacement risk is overplayed, with the Mews partnership natively embedding SiteMinder's distribution capability seen as "disconfirming evidence of that bear case"
Flags property-count acceleration, with partnerships able to scale properties at lower ARPUs but also lower acquisition and servicing costs, implying earnings upside
Australia 10-year yield back at 5.00%
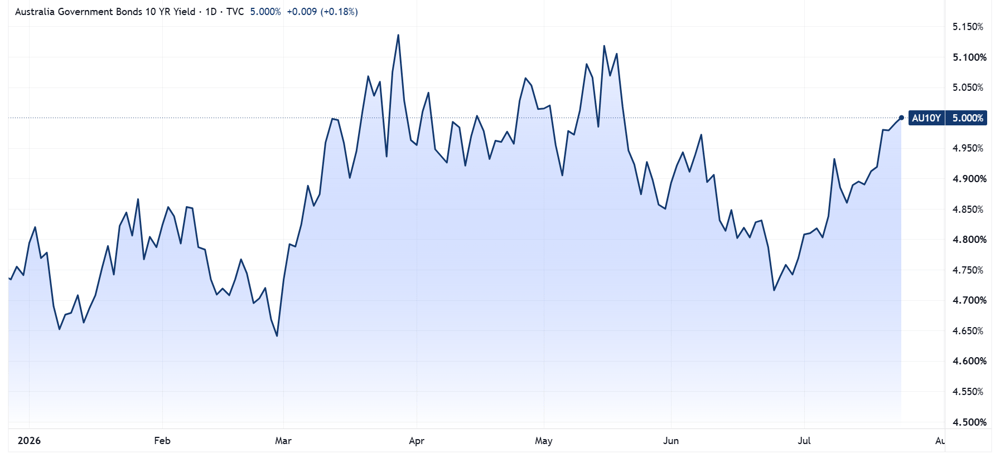
[1:14 pm] The Aussie 10-year yield has V-shaped its way back to 5.00%, a level that is typically bearish for equities. A mix of still-solid economic data and soaring oil prices has pushed the 10-year up a massive 28 bps since the 24 June low of 4.71%.
Australia 10-year bond yield (Source: TradingView)
A solid day for big miners
[12:33 pm] Large cap miners are trading broadly higher at noon, with the S&P/ASX 200 Materials index up 1.6% and on track to record a three-day win streak. The index is still down 9.5% since its 17 June record high.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
BHP | BHP Group | 1.2% | $60.49 | -0.1% | 32.9% |
RIO | Rio Tinto | 0.6% | $162.91 | -1.2% | 11.0% |
FMG | Fortescue | 1.6% | $18.88 | -1.0% | -14.2% |
NST | Northern Star Resources | 2.7% | $20.89 | 4.7% | -14.9% |
EVN | Evolution Mining | 3.2% | $11.72 | 6.4% | -6.8% |
S32 | South32 | 2.1% | $4.65 | 15.3% | 30.8% |
LYC | Lynas Rare Earths | -0.9% | $15.25 | -5.6% | 22.8% |
BSL | Bluescope Steel | 0.7% | $32.56 | 1.0% | 35.3% |
PLS | PLS Group | 4.2% | $4.33 | -5.6% | 3.0% |
ORI | Orica | 1.3% | $23.28 | -1.0% | -4.0% |
MIN | Mineral Resources | 2.8% | $55.15 | -7.7% | 1.4% |
SFR | Sandfire Resources | 4.1% | $19.46 | 3.0% | 8.3% |
Noosa Mining Conference wrap: gold producers talk up cash, grades and growth
[12:27 pm] Day two of the Noosa Mining Investor Conference featured WA and West African gold producers spruiking strong balance sheets and aggressive drilling against a supportive gold price.
Regis Resources (RRL): lifted Duketon guidance on "opportunistic ounces" via the idle Duketon North mill, with the Bakewell project delivering 223koz over five and a half years. On the cost commentary the ounces have drawn, management said "who in their right mind wouldn't undertake this project" given a 127% IRR, adding "if the gold price drops... we can turn it off overnight"
Ramelius Resources (RMS): achieved guidance for the sixth straight year at 192koz, with $650m cash and no debt. On growth, management pointed to WA-style undergrounds being "three years of reserves and will do for the next 20 years", and flagged a maiden Fletcher-style surprise potential as it doubles exploration spend by $100m
Pantoro (PNR): aiming to lift Norseman from around 100koz to 200koz by replacing low-grade open pits with high grade, noting "grade is king" as it pushes plant feed toward five to seven grams, backed by $220m cash and no debt, with a first hole into a Crown Reef pillar returning "just under six meters at 35 grams a tonne... everything you see there is visible gold"
Turaco Gold (TCG): advancing the Afema project in Cote d'Ivoire, described as a "top five undeveloped African gold project" targeting 200koz a year, adding resource "at a run rate of about 100,000 ounces per month" toward a US$3bn NPV and near-100% IRR at US$4,000/oz
Black Cat Syndicate (BC8): producing at a 100koz run rate with $92m cash and no debt, flagging two high-grade discoveries at Paulsens, with management noting "not only have we found it, but we've now developed through it very quickly", including a development drive at 9.7g/t over 76m
Analysts' take on Lynas
[12:24 pm] Lynas shares fell 3.6% lower on Wednesday after a Q4 result missed materially on NdPr output as ore variability at Mt Weld lifted concentrate impurities and constrained productivity at Kalgoorlie and Kuantan, alongside raised capex guidance for the Malaysian heavy rare earth expansion.
Ord Minnett upgraded to Lighten from Sell, raised target from $14.00 to $15.00: downgraded production forecasts on difficult Mt Weld chemistry but judged the selling largely exhausted, while preferring smaller rare earth names offering better value.
JPMorgan maintained Overweight, lowered target from $22.00 to $18.50: cut earnings materially on volumes and higher costs after production and sales missed on feed quality, though it saw the weakness as overdone given the scarce ex-China supply position.
Canaccord Genuity maintained Buy, lowered target from $22.00 to $21.00: attributed the miss to apatite pockets disrupting the flowsheet and judged the metallurgical constraints transient rather than structural, with geopolitical significance and price floors supporting earnings.
Analysts' take on Paladin Energy
[12:23 pm] Paladin Energy shares closed 6.6% higher on Wednesday after its Q4 result confirmed completion of the Langer Heinrich ramp up and delivered production, sales and costs at or above guidance, alongside a materially stronger cash position on higher sales.
While analysts viewed the quarter as stronger than expected, FY27 guidance landed below consensus on production, sales and costs, with softer sales tied to uranium product loan repayments and first half weakness from planned maintenance and lower grades ahead of a second half recovery.
UBS upgraded to Buy from Neutral, lowered target from $12.60 to $11.70: sees the stock as oversold versus spot uranium strength and conservative FY27 guidance as cautious management, with asymmetric upside from derisking and cash generation.
JPMorgan upgraded to Neutral from Underweight, lowered target from $9.20 to $9.10: sees risk reward skewed to the upside after estimate rebasing despite product loan repayments driving a material FY27 earnings downgrade, with the investor day a potential positive catalyst.
RBC Capital Markets maintained Outperform, target unchanged at $13.50: views valuation as stretched versus peers and flags additional capex outside guidance and negative cashflow, with consensus seen as cum downgrade across FY27 metrics.
Tech stocks on the backfoot
[11:44 am] The S&P/ASX 200 Tech Index is trading sharply lower, down 2.4% to a one-month low. Heavyweight names like Wisetech, Life360 and Pro Medicus are trading notably lower, down 3-4%. There's no obvious catalyst beside a weak overnight session for software names, with the iShares Expanded Tech-Software ETF falling 3.0%.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
WTC | Wisetech Global | -4.9% | $32.19 | -6.0% | -53.0% |
360 | Life360 | -4.2% | $24.45 | -5.8% | -24.1% |
PME | Pro Medicus | -4.1% | $166.41 | -13.8% | -24.6% |
XRO | Xero | -3.6% | $65.40 | -4.5% | -42.6% |
TNE | Technology One | -2.7% | $28.49 | -3.8% | 3.4% |
HSN | Hansen Technologies | -1.4% | $4.21 | 0.7% | -20.3% |
CAT | Catapult Sports | -1.4% | $3.54 | 0.9% | -14.9% |
OCL | Objective Corporation | -1.1% | $6.93 | 4.1% | -58.2% |
BVS | Bravura Solutions | -1.0% | $2.46 | -3.7% | -4.5% |
IFT | Infratil | -0.8% | $12.99 | 1.5% | 35.6% |
DGT | Digico Infrastructure Reit | -0.8% | $2.61 | -1.9% | -6.5% |
IRE | Iress | -0.8% | $6.56 | 3.6% | -21.7% |
NXT | NextDC | -0.4% | $13.92 | 1.8% | 13.0% |
CDA | Codan | -0.4% | $42.11 | -1.5% | 48.2% |
MP1 | Megaport | 0.2% | $19.15 | -5.1% | 68.8% |
AD8 | Audinate Group | 0.3% | $1.91 | -10.6% | -53.1% |
MAQ | Macquarie Technology Group | 0.4% | $65.98 | -0.2% | -1.5% |
DDR | Dicker Data | 1.2% | $12.59 | 8.1% | 22.4% |
DTL | Data#3 | 1.5% | $10.15 | 7.6% | 13.2% |
SDR | Siteminder | 1.5% | $3.35 | -8.5% | -45.4% |
South Korea Q2 GDP beats on semiconductor export boom
[11:43 am] South Korea's economy grew faster than expected in the second quarter as a chip export surge offset weaker construction investment.
GDP rose 0.6% quarter-on-quarter vs 0.4% expected, though a sharp deceleration from Q1's 1.8%
Annual growth of 3.7% also beat the 3.5% estimate
Exports rose 1.4% on the quarter, led by semiconductors, machinery and equipment, while private consumption grew 0.4% and construction investment fell 0.2%
A BOK official said annual growth of 3% is possible this year if the pace holds, above the central bank's 2.6% forecast set in May and due for revision in August
With inflation at a two-and-a-half-year high, most analysts see at least one more rate hike to 3.00% this year after July's 25bp increase, with 3.25% expected by Q1 2027
Australian unemployment holds at 4.4% as jobs surge smashes expectations
[11:33 am] The jobless rate held steady at 4.4% in June, but a bumper 76,000 employment gain blew past the 15,000 expected, with a rising participation rate absorbing the strength.
Employment rose 76,000 vs 15,000 expected, driven by a 47,000 rise in part-time roles, partly reflecting people who had been waiting to start a job in May
Unemployment rate held at 4.4% in line with expectations, as the number of unemployed rose 13,000
Participation rate climbed 0.3 percentage points to 67.0%, with 55-64 year olds recording the largest annual gain, up 0.8 points to 70.6%
Underemployment rose 0.2 percentage points to 6.5%, while hours worked edged up 0.2% as part-time hours grew 1.2% and full-time hours were flat
Annually, employment grew 1.7% and hours worked rose 1.8% from June 2025
Source: ABS
Stocks on the move: OFX, GDG, James Hardie and Sandfire
[11:00 am] A busy day of corporate news drove sharp moves, led by OFX's takeover premium and a strong quarterly from Generation Development.
OFX Group (+71.5%): after agreeing a transaction process deed for an all-cash takeover by UK-based Equals at $1.00 per share, a 108% premium to its undisturbed price
Generation Development Group (+31.1%): after FY26 group FUM rose 36% to $46.4bn, with record Generation Life sales and a strategic retirement partnership with Colonial First State
James Hardie (+6.1%): after guiding Q1 net sales and adjusted EBITDA around 10% above consensus on stronger-than-expected Siding & Trim sales
Sandfire Resources (+5.0%): after Q4 copper equivalent production rose 38% to 47.6kt, beating ests, driving record earnings and a swing to $353m net cash
Macquarie Group (+0.50%): after announcing CEO Shemara Wikramanayake will retire in November, with Greg Ward to succeed her, alongside a satisfactory Q1 trading update
Santos (-0.5%): after Q2 production and revenue missed ests, though management flagged a 20% to 30% second-half production uplift as Barossa and Pikka ramp up
ASX 200 sharply higher on broad gains for resources, REITs and banks
[10:53 am] A rather surprising open for the S&P/ASX 200, currently up 1.03% to the highest since 19 June. This is despite Wall Street finishing broadly lower, bond yields grinding higher and oil trading at ~US$95 a barrel.
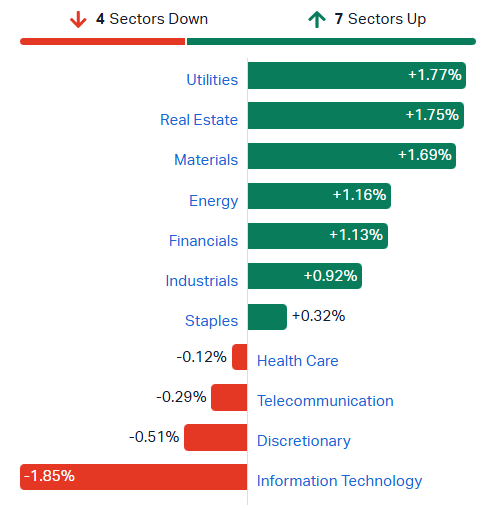
S&P/ASX 200 sectors (Source: Market Index)
What would you like to see more of on the blog?
[10:40 am] Hi there! We're keen to hear what else you'd like us to cover.
A Q&A section would involve answering your questions (e.g. Why is GQG up 30% today)
Extra scans (probably more top gainers and losers for various market caps and sectors)
Some light Nikkei, Hang Seng and KOSPI coverage
A deep dive into genuinely interesting stocks
Memes and humour, if you're up for it
Lotus Resources unveils $138m funding package to fund Kayelekera ramp-up
[10:18 am] The uranium developer has combined an entitlement offer, convertible notes and a prepayment facility to support production ramp-up and settle near-term offtake obligations.
Fully underwritten $60.1m 1-for-1 accelerated non-renounceable entitlement offer
Priced at 22 cents per share, a 67% discount to the last close of $0.66
Binding agreement for $35m of senior unsecured convertible notes from CVI Investments, with an initial conversion price set at 115% of the offer price
Binding commitment letter with Mercuria Energy Trading for a US$30m ($43m) inventory-backed prepayment facility and marketing agreement
Proceeds will fund the ongoing ramp-up and optimisation of Kayelekera plus cash settlement of near-term offtake obligations and corporate costs
All directors will participate, taking up full entitlements and sub-underwriting additional commitments up to a combined $400k
This will be a massive payday for short sellers, as short interest in the stock has ballooned to 22.8%.
Company page: Lotus Resources (LOT)
Top ASX 200 gainers and losers
[10:05 am] Generation Development Group surges after funds under management growth accelerated in the June quarter, Paladin gets another kick after yesterday's quarterly and James Hardie also higher on a strong quarterly earnings update. Meanwhile, tech/software names open broadly lower following a weak lead from Wall Street (iShares Expanded Tech-Software ETF down 3.0%).
Ticker | Company | % Chg | Price |
|---|---|---|---|
GDG | Generation Development Group | 29.94% | $4.34 |
PDN | Paladin Energy | 9.09% | $9.96 |
JHX | James Hardie | 8.18% | $37.70 |
KCN | Kingsgate Consolidated | 7.56% | $4.27 |
SFR | Sandfire Resources | 5.40% | $19.70 |
AAI | Alcoa Corporation | 5.14% | $67.14 |
DYL | Deep Yellow | 4.96% | $1.42 |
IGO | IGO | 4.63% | $7.01 |
MIN | Mineral Resources | 3.79% | $55.66 |
NIC | Nickel Industries | 3.66% | $0.91 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
360 | Life360 | -3.76% | $24.55 |
WTC | Wisetech Global | -2.98% | $32.83 |
DMP | Domino's Pizza | -2.96% | $16.39 |
WES | Wesfarmers | -2.88% | $87.31 |
XYZ | Block | -2.46% | $110.68 |
PME | Pro Medicus | -2.24% | $169.56 |
HUB | Hub24 | -1.89% | $83.70 |
COH | Cochlear | -1.66% | $110.33 |
REA | REA Group | -1.65% | $157.08 |
XRO | Xero | -1.49% | $66.84 |
Domino's exposure uncertain after Court finds misleading conduct on 2005 agreement
[10:03 am] The Federal Court found Domino's historical representations breached consumer law, but potential exposure beyond the lead applicant remains unquantifiable.
The Federal Court found Domino's historical representations about the application of certified enterprise agreements constituted misleading and deceptive conduct under the Australian Consumer Law rather than the Fair Work Act.
The Court assessed lead applicant Gall's loss at around $12k, with findings of causation and loss limited to that claim only.
Wider exposure to other alleged group members remains highly uncertain and unquantifiable at this stage.
Domino's is reviewing the Reasons for Judgment to assess its position, including any available grounds of appeal.
No orders were made and the parties have been directed to file short minutes of order within seven days.
The Court indicated it intends to refer the balance of the proceeding to mediation.
Company page: Domino's Pizza Enterprises (DMP)
Generation Development caps FY26 with 36% FUM growth and CFS win
[9:46 am] Generation Development Group finished FY26 with group funds under management up 36% to $46.4 billion, driven by record Generation Life sales and continued Evidentia expansion.
Group FUM of $46.4bn at June, up 36% on the prior year, after integrating the Evidentia and Lonsec managed account businesses
Generation Life posted record quarterly sales inflows of $442m, up 39%, ending with FUM of $5.95bn
Colonial First State selected Generation Life as its strategic retirement solutions provider, one of the group's most significant alliances given CFS administers more than $180bn
Evidentia FUM reached $40.5bn, up 37%, with quarterly net inflows of $3.5bn including the $1.8bn Xplore Wealth transition and positive market movements of $2.3bn
Evidentia added strategic partnerships with Vanguard and Ironbark and acquired Encore Advisory Services, supporting the launch of its Private Investment Series
Lonsec expanded its research platform to over 2,000 products under research
I don't have any recent consensus numbers handy, but June quarter FUM for Evidentia is up 16.3% quarter-on-quarter, compared to negligible growth in recent quarters (March QoQ up 0.8%, Dec-25 QoQ up 5.8%, Sep-25 QoQ up 10.1%).
Company page: Generation Development Group (GDG)
Explorers report gold drilling, rare earth output and a silver deal
[9:45 am] A busy day at the junior end of the market, spanning drill results, a rare earth production milestone and a silver-focused acquisition.
Sun Silver will acquire the Bayan Springs North project from Bayan Mining for up to $800k, comprising $150k on completion, $150k in cash after 12 months and a $500k milestone payment in cash or shares, plus a 1.0% NSR to Bayan that Sun Silver can halve for a one-off $2.0m payment.
Turaco Gold returned 100m @ 1.06g/t gold from 495m in hole WOUDD0244 at the Woulo Woulo deposit, Afema project, including 36m @ 1.87g/t from 559m.
The intercept sits 250m below prior high-grade drilling and points to a broad body of higher-grade mineralisation beneath the current 1.7Moz resource and PFS pit design.
Boab Metals has completed around 60% of Phase IX drilling at its Sorby Hills silver-lead-zinc project, finishing all reserve conversion drilling at the B, Omega and Norton deposits, with high-grade galena at Norton supporting reserve growth and mine-life extension.
Viridis Mining and Minerals has reached steady-state continuous production of mixed rare earth carbonate at its demonstration plant, with July recoveries of 79% MREO and 64% TREOB beating PFS assumptions of 76% and 57%.
High-grade samples have been shipped to offtake partner Solvay in France, with the improved recoveries set to feed into the definitive feasibility study.
Santos Q2 production and revenue miss as commissioning costs weigh
[9:14 am] Santos reported second-quarter production and revenue below consensus, though management flagged a sharp second-half uplift as Barossa and Pikka ramp up.
Production of 23.1mmboe vs 24.1mmboe ests (4% miss), up 3% on the prior quarter, with first-half production of 45.6mmboe
Sales revenue of US$1.35bn vs US$1.53bn ests (12% miss), up 6% on the prior quarter
Realised LNG price of US$11.21/mmbtu vs US$12.5 ests (10% miss), up 4.9% quarter-on-quarter despite the pricing lag on a weak Q1 JCC
Second-half production expected to rise around 20% to 30% on the first half, with Barossa at 97% of planned rates and Pikka targeting 80,000 bbl/day plateau in Q3
FY26 production guidance narrowed to 99-105mmboe from 101-111mmboe, with capex unchanged at US$1.95bn-US$2.15bn and unit costs held at US$6.95-US$7.45/boe
On the interim dividend: the board will weigh full-year cash flow timing, with first-half free cash flow hit by one-off items not reflective of underlying capacity
Company page: Santos (STO)
Sandfire finishes year strongly as Q4 copper output tops expectations
[9:07 am] Sandfire delivered a record quarter with copper equivalent production up 38% and well ahead of consensus, driving record financial outcomes and a swing to a solid net cash position.
Group CuEq production up 38% to 47.6kt vs 43.6kt ests (9% beat), for annual output of 154.2kt within guidance
Copper production of 34.2kt vs 29.1kt ests (18% beat), with silver at 1.8Moz vs 1.3Moz ests (38% beat), though zinc and lead came in below consensus
Quarterly underlying EBITDA of $343m vs $325.5m ests (5% beat)
C1 costs beat at both operations, with MATSA at US$0.47/lb vs US$0.66 ests and Motheo at US$0.70/lb vs US$0.86 ests
Net cash of $353m at June, up $277m in the quarter, from $76m net cash at March and $123m net debt a year earlier
FY26 CuEq guidance of 150-166kt, FY27 guidance of 150kt-166kt CuEq, with unit costs rising only incrementally but around a one-third increase in capital investment across the portfolio
Company page: Sandfire Resources (SFR)
Equals agrees deal process to acquire OFX at $1.00 per share cash
[9:04 am] OFX has entered a transaction process deed with UK-based Equals Group for an all-cash takeover at $1.00 per share, with the board intending to unanimously recommend the deal.
Cash consideration of $1.00 per share values OFX equity at $247m and enterprise value at $233m, implying a 9.2x FY26 EV/EBITDA multiple
Offer represents a 108% premium to OFX's undisturbed close of $0.480 on 4-Feb, the day before its strategic review was announced
OFX board intends to unanimously recommend the scheme, subject to agreeing terms, comfort on Equals' debt funding, no superior proposal and an independent expert's endorsement
Equals granted four weeks of exclusivity, extendable by a further four weeks, to complete confirmatory due diligence, secure debt financing and enter a Scheme Implementation Deed
Company page: OFX Group (OFX)
James Hardie flags Q1 beat as Siding & Trim sales top guidance
[9:02 am] James Hardie expects first-quarter results to exceed prior guidance on stronger-than-expected Siding & Trim sales, though management attributes the outperformance to execution rather than a US housing recovery.
Net sales of US$1.45bn-US$1.48bn vs US$1.32bn ests (11% beat at midpoint) and up from prior guidance of US$1.32bn-US$1.35bn (10% above at midpoint)
Adjusted EBITDA of US$399m-US$407m vs US$366.1m ests (10% beat at midpoint) and up from prior US$354m-US$375m (11% above at midpoint)
Siding & Trim net sales of US$846m-US$860m, up from prior US$758m-US$781m, with segment EBITDA of US$282m-US$288m
Deck, Rail & Accessories net sales of US$296m-US$305m, up modestly from prior US$291m-US$300m, though the segment posted a small GAAP operating loss
GAAP net income guided to US$102m-US$104m
CEO commentary: "Our first quarter results are expected to exceed our prior guidance, primarily as a result of better-than-expected sales in Siding & Trim. Siding & Trim net sales reflected strong sell-through and underlying demand for our products. Our performance in Deck, Rail & Accessories was driven by channel inventory normalization and sell-through that improved throughout the quarter.”
NYSE-listed James Hardie shares are up 4.1% after hours.
Company page: James Hardie (JHX)
Helloworld says Webjet ignored earlier $1 per share takeover approach
[9:00 am] Helloworld boss Andrew Burnes has escalated the dispute with Webjet, claiming its former chairman never responded to a $1 per share bid lobbed last September, the AFR reports.
Undisclosed $1 per share approach made last September drew no response and was withdrawn, vs. a competing 80 cent bid from BGH Capital and Ariadne Investments at the time
Helloworld later bid 90 cents per share, disclosed, with BGH and Ariadne countering at 91 cents, before Webjet terminated talks in February and shares crashed to 40 cents
Helloworld holds a 20.1% stake and is pushing for two board seats, which Webjet has resisted given the pair are direct rivals
Webjet cash balance has fallen to under $90m from $112m at demerger, and Burnes estimates it could be as low as $50m excluding cash held for bookings
Webjet reported earnings of $18.2m for the 12 months to 31-Mar, up 8%, with net profit of $3.7m even as bookings slid 7%
Source: AFR
Macquarie flags satisfactory Q1 as commodities lifts but asset management slips
[8:59 am] Macquarie reported satisfactory first-quarter trading at its AGM, with commodities and markets substantially higher but asset management earnings down after a divestment.
MAM net profit contribution down year-on-year, driven by the 2H26 divestment of the North American and European public investments business, with AUM of $748.0bn at June, up 4% on the quarter
CGM net profit contribution substantially up year-on-year on stronger North American gas and power trading against subdued conditions in the prior period
BFS net profit contribution up year-on-year on loan and deposit growth, with deposits of $223.3bn and the home loan book up 6% to $191.5bn, though margins fell on portfolio mix and competition
Macquarie Capital contribution up year-on-year on higher investment-related and brokerage income, partially offset by lower advisory fees, with the private credit portfolio steady at $27.2bn
CET1 ratio of 13.8% at June, up from 12.8% at March, with the harmonised ratio at 18.9%
Company page: Macquarie Group (MQG)
Wikramanayake to retire as Macquarie CEO in November
[8:58 am] Macquarie has announced that long-serving CEO Shemara Wikramanayake will retire in November, with Head of Banking and Financial Services Greg Ward named as her successor.
Wikramanayake steps down from the Macquarie Group and Macquarie Bank boards effective 6-Nov after eight years as CEO and almost four decades with the firm
Greg Ward appointed MD and CEO effective 7-Nov, subject to necessary approvals, having joined Macquarie in 1996 and served as Global CFO for 14 years before running BFS from 2013
Ward led the repositioning of BFS into a significant competitor in Australian personal banking, business banking and wealth management
Company page: Macquarie Group (MQG)
Oil prices hit a seven-week high
[8:56 am] Brent climbed a further 4.2% overnight to US$95.49 a barrel, now up 34% since the 1 July low.

Brent price chart (Source: TradingView)
Oil jumps as US-Iran conflict escalates with Trump infrastructure threat
[8:43 am] Oil prices surged and tensions intensified as Trump threatened to bomb Iranian bridges and power plants, US forces struck Iran for an 11th straight night and Rubio said Tehran was not serious about a deal.
Trump threatened via Truth Social to destroy one Iranian bridge or power plant, including targets in or near Tehran, each time Iran fires on a ship in the Strait of Hormuz
Iran retaliated by threatening to strike regional infrastructure and energy facilities where the US has interests, and reiterated it wants transit through Hormuz coordinated with Tehran
US Central Command struck Iranian military operations centres, drone storage and logistics infrastructure for an 11th consecutive night, while Houthis declared an embargo on ships loading at Saudi ports
Rubio said Iran violated last month's memorandum of understanding within two weeks and does not have the right to control an international waterway, though Washington remains open to a deal
US diesel back above US$5 a gallon at retail and refining margins at all-time highs, with US refiners producing a near-record 5.3m barrels a day this month amid a global supply crunch
Trump set to impose fresh tariffs by Friday as stopgap duties expire
[8:43 am] The Trump administration is preparing to apply new tariffs on dozens of trading partners before temporary 10% global duties lapse on Friday, ensuring no gap in the tariff regime.
New levies of at least 10% target 60 trading partners on forced-labour grounds, with Canada, Mexico, the EU and Taiwan facing 10% and China, India and Japan facing 12.5%
Duties would replace the stopgap 10% global tariff applied under Section 122 after the Supreme Court struck down Trump's earlier global tariffs, this time invoking Section 301
Plan is not final and full reimposition may slip, as the proposal still requires a formal comment period and hearings before taking effect
Separate escalations underway, with a vowed 50% tariff on many Canadian goods, a 25% tariff on many Brazilian products and a threatened 100% duty on generic drugs from August 2028
A separate excess-capacity probe is not expected to produce tariffs by Friday, with that process still ongoing
Source: Bloomberg
China sticks with fiscal restraint despite deepening slowdown
[8:42 am] China's public spending fell the most since October in June even as growth undershoots, though officials signal looser policy is still coming.
Broad expenditure tumbled 11.9% in June year-on-year against 1.8% revenue growth, cutting the first-half broad deficit 13% to 4.57tn yuan (US$675bn)
Infrastructure spending under the general public budget fell almost 9% in the June quarter, while education, healthcare and social security outlays rose 4.9% under Beijing's "investment in people" push
Land sale income slumped 31.5% in the first half as the property downturn continues to weigh on local government finances
Stamp duty surged 40.9%, the most among major taxes, with equity-trading collections nearly doubling, while VAT rose 6% and corporate income tax gained 3.9%
Stimulus still likely, with provinces holding nearly 1.9tn yuan in unused bond quota for the second half and 800bn yuan of policy financing tools set for aggressive third-quarter rollout
Source: Bloomberg
BOJ open to faster rate hikes as yen weakness fuels inflation risks
[8:41 am] Bank of Japan officials are willing to raise rates more quickly than the six-monthly pace economists expect, as a slumping yen adds to upside inflation risks.
BOJ seen holding at its 31-Jul meeting after lifting the benchmark to 1% last month, the highest in 31 years, with most watchers tipping the next hike in December
Officials open to moving earlier than the assumed six-month cadence with no preset course, as underlying inflation nears the 2% target set more than 13 years ago
Yen firmed to 162.69 per dollar on Wednesday after sliding overnight to a four-decade low, prompting fresh government warnings on possible intervention
2-year JGB yield rose to its highest since 1995 and the 5-year to 1.995%, with markets pricing about a 72% chance of a hike by October
Source: Bloomberg
BofA traders say buy momentum stocks after selloff, eyeing 5% bounce
[8:40 am] Bank of America's trading desk is telling clients to buy US momentum names, arguing a sharp drawdown has created an attractive entry point ahead of a seasonally strong August.
BofA momentum basket ended last week down more than 10% from its 25-Jun peak, on track for its second-worst July in a decade
Historically a drop of that size has been followed by an average 5% gain over the next month, with August the best-performing month for the basket over the past decade
Desk recommends buying the US High Momentum or US TMT High Momentum index via swaps or August call options
Basket holdings include Sandisk, Micron, Danaher, Coinbase and AMD
UBS trading desk also sees the slide nearing an end, flagging an opportunity to rebuild AI and semiconductor positions
Source: Bloomberg
US 30-year yield holds above 5% for longest run since 2007
[8:39 am] The US long bond has traded above 5% for 27 days this year on mounting fiscal concerns and a wave of AI-linked debt issuance competing for buyers.
30-year yield settled at 5.15%, having held above 5% for 27 days in 2026 including the last 12 in a row, the most since 2007
Fed benchmark sits 150bps lower than in 2007, implying investors are demanding more compensation to hold long-dated Treasuries than at the onset of the subprime crisis
US Treasury market has ballooned to US$31tn from US$4.5tn since 2007, with debt above 100% of GDP and annual interest costs topping US$1tn
Over US$500bn of AI-linked financing is competing for the same long-end buyers, a key reason some managers now see 5%-plus yields as sticky rather than quickly bought
30-year real yield has risen around 50bps this year toward 3%, last seen in 2008, with dealers expecting Treasury to lift two to 30-year coupon auction sizes by May 2027
Source: Bloomberg
Tesla misses on earnings as margins compress despite revenue beat
[8:38 am] Tesla beat on revenue and deliveries but missed sharply on profitability, with auto margins ex-credits sliding as regulatory credits collapsed and no new guidance was provided.
Revenue up 26% to US$28.24bn vs US$26.32bn ests (7% beat)
Adjusted EPS down 18% to US$0.33 vs US$0.51 ests (35% miss)
Auto margin ex-credits of 16.3% vs 18.1% ests, down 310bps year-on-year, with regulatory credits down 67% to US$146m
Operating margin of 1.4% vs 5.4% ests, down 269bps, as operating income fell 57% to US$398m
Deliveries up 25% to 480,126, with active FSD subscriptions up 56% to 1.48m and inventory cut to 15 days of supply from 27
Free cash flow of -US$1.09bn, well ahead of the -US$3.25bn ests, aided by US$4.70bn operating cash flow
Tesla is currently trading 4.6% lower after hours.
Alphabet lifts FY26 capex guide to as much as US$205bn on stronger AI demand
[8:36 am] CEO Sundar Pichai flagged early-stage AI adoption across consumer and enterprise as Alphabet raised spending plans and warned of near-term Cloud margin pressure.
FY26 capex guide raised to US$195bn-US$205bn, up from US$180bn-US$190bn, citing accelerated capacity deliveries to meet demand
Supply constraints will see third-party capacity expanded in Q3 as a temporary bridge, creating modest near-term margin pressure
Gemini 4 is being trained as a much larger base model, with Pichai saying the next generation needs more scale to compete at the frontier
TPU system sales will see only a small portion of revenue recognised in 2026, with the majority in 2027
On AI adoption: Pichai said it feels like "very early innings" of a secular shift across Google's core information businesses, adding enterprises are "barely scratching the early stages" of what is possible
Alphabet beats across the board as Cloud surges 82% and capex guide lifted
[8:35 am] Alphabet delivered a broad top and bottom-line beat, with Cloud growth clearing buy-side expectations and full-year capex guidance raised sharply.
Revenue up 24% to US$119.80bn vs US$117.02bn ests (2% beat)
Revenue ex-TAC up 27% to US$103.62bn vs US$101.07bn ests (3% beat)
EPS ex disclosed equity-gain impact of ~US$2.85 vs US$2.90 ests (2% miss)
Google Cloud revenue up 82% to US$24.77bn vs US$22.46bn ests (10% beat), operating margin 35.6% vs 30.8% ests and up from 20.7% a year ago
Search & Other of US$63.27bn vs US$63.28bn ests (in line), up 17%, with YouTube Ads up 13% to US$11.06bn
CapEx of US$44.92bn vs US$44.1bn ests, more than doubling year-on-year
Alphabet shares are currently down 2.9% after hours.
ServiceNow beats and raises FY26 guide as AI ACV tops US$1bn
[8:35 am] ServiceNow beat across every top line and profitability metric and lifted full-year subscription guidance, with AI annual contract value crossing US$1bn in the quarter.
Total revenue up 24% to US$3.99bn vs US$3.92bn ests (2% beat)
Subscription revenue up 24.5% to US$3.88bn, or 23% in constant currency
Adjusted EPS of US$0.90 vs US$0.86 ests (5% beat)
cRPO up 21% to US$13.20bn vs US$13.03bn ests (1% beat), with total RPO up 21% to US$29.0bn
FY26 subscription guide raised to US$15.76bn-US$15.78bn, up 22.5%, alongside 31.5% operating margin and 35% free cash flow margin
ServiceNow AI ACV crossed US$1bn in the quarter, with customers over US$5M ACV up 23% to 658
ServiceNow shares fell 6.4% overnight but trading 4.9% higher after hours.
US stocks slip as oil surge lifts yields and revives rate-hike bets
[8:35 am] Wall Street closed lower on Wednesday as an oil rally on escalating US-Iran tensions pushed bond yields higher and lifted the odds of a Fed rate hike.
S&P 500 down 0.14% to 7,498.96, with the Nasdaq off 0.57% to 25,690.90 and the Dow flat at 52,218.58
Brent up 4.2% to US$95.49 a barrel, now up 34% since 1-Jul, after the 11th straight round of US strikes on Iran, placing upward pressure on bond yields
US 10-year yield up 11bps over the last three sessions and on the cusp of its highest since Jan-25
Megacaps mostly lower, with SpaceX down 6.7%, Meta down 2.5% and Microsoft down 1.8%, though Nvidia rose 2.3%
Rate-hike odds this month jumped to nearly 34% from 10% a week ago, with a 78% chance of at least a quarter-point hike priced for September
Good morning!
[8:21 am] ASX 200 futures are up 72 pts (+0.82%).
The overnight session in a nutshell:
Major US benchmarks finished narrowly lower as Big Tech weakness and rising oil offset Energy gains ahead of the first Magnificent Seven results
S&P 500 (-0.14%), Nasdaq (-0.57%), Dow (-0.01%), Russell 2000 (-0.92%)
Alphabet and Tesla headlined Q2 earnings, with Alphabet beating on revenue and Google Cloud surging 82%, while Tesla topped revenue but missed on profit and margins
Alphabet and Tesla shares both trading lower after hours, down 3.1% and 4.1% respectively
Oil prices continue to run as the US carried out an 11th consecutive night of strikes on Iran, Brent is now trading at US$95 a barrel and up 34% since 1-Jul