In a nutshell:
Major US benchmarks closed mostly lower as big chipmakers like Nvidia (-2.9%), Micron (-4.8%) and Broadcom (-4.3%) led the losses, while the Dow made a small gain
OpenAI sparked a chipmaker selloff when it was reported the company told investors its annualised revenue is nearing $50bn, about $20bn below figures reported last month, reviving doubts over returns on the AI buildout: the Philadelphia Semiconductor Index (SOX) lost 3.4%
Trump ruled out attacking Iran before the 3 November midterms, trimming an oil rally fuelled by record Hormuz tanker attacks and Gulf of Mexico storm shut-ins
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,765 | -0.47% |
Dow Jones | 51,232 | +0.10% |
NASDAQ Comp | 27,193 | -1.25% |
Russell 2000 | 2,794 | +0.03% |
Global Indices | ||
 S&P/TSX | 35,145 | +0.30% |
 Shanghai Composite | 3,812 | -0.79% |
 DAX | 24,807 | -1.18% |
 Hang Seng | 23,786 | -1.43% |
 Nifty 50 | 71,593 | -1.44% |
 Nikkei 225 | 69,042 | -1.42% |
 FTSE 100 | 10,442 | -0.16% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,133.12 | +0.54% |
 Copper | 6.5 | -1.48% |
 WTI Oil | 91.18 | +3.29% |
Currency | ||
 AUD/USD | 0.6959 | +0.02% |
Cryptocurrency | ||
 Bitcoin (USD) | 81,585 | -1.83% |
 Ethereum (AUD) | 3,549 | -3.98% |
Miscellaneous | ||
US 10 Yr T-bond | 5.231 | -0.87% |
VIX | 15.41 | +2.19% |
US Sectors
Sector | % Chg |
|---|---|
| Energy | +2.92% |
| Consumer Staples | +2.12% |
| Financials | +0.91% |
| Real Estate | +0.59% |
| Materials | +0.46% |
| Industrials | +0.30% |
Sector | % Chg |
|---|---|
| Communication Services | -0.06% |
| Utilities | -0.26% |
| Health Care | -0.41% |
| Consumer Discretionary | -0.47% |
| Information Technology | -1.78% |
S&P 500 Session Chart
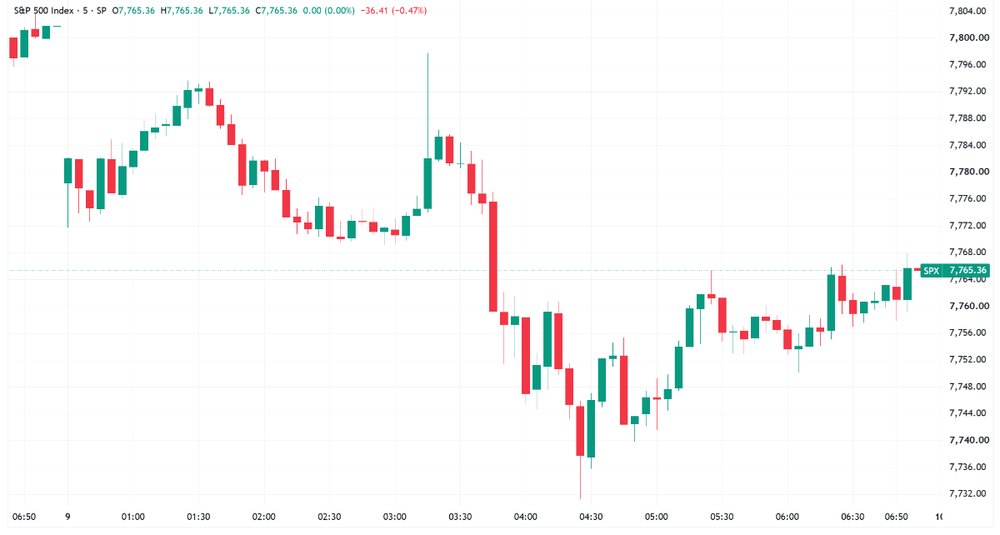
S&P 500 trended mostly lower throughout the session amid a selloff for megacap chipmakers to finish off worst levels (Source: TradingView)
Overnight Markets
Major US benchmarks mixed but off their worst levels after a midday chip selloff, sparked by the FT’s report on OpenAI’s revenue
The Philadelphia Semiconductor Index (SOX), which tracks 30 of the largest US-listed chip designers, manufacturers and equipment makers, fell 3.4% after the news, with big names like Nvidia (-2.9%), Micron (-4.8%) and Broadcom (-4.3%) among the decliners
S&P 500 Equal Weight index finished 0.6% higher, showing the losses in the cap-weighted S&P 500 were concentrated in its largest names
The US 2-year bond yield continued its three day pull back, falling 1 bp to 4.75%, now down 3.5% since 28 September, the 30-year yield also pulled back from its 24 highs by 6bps to 5.6%
The FT reported OpenAI told investors its annualised revenue is nearing $50bn, about $20bn below the $70bn widely reported last month (FT)
Brent rose 2.5% to $103 a barrel, adding to a near 9% rise since 29 September, as Iran stepped up tanker attacks in the Strait of Hormuz and Hurricane Isaias shut about 500,000 barrels a day of Gulf of Mexico output, though Trump’s remarks on Iran trimmed the gains (CNBC)
Macquarie strategists warned nearly every major financial blowup of the past 50 years has followed rapid moves in long-term bond yields (YF)
Stocks
Chipotle jumped 6% and Starbucks fell as much as 6.7%, its biggest intraday drop in over a year, after the FT reported Starbucks has worked with advisers on a takeover proposal for the burrito chain previously led by CEO Brian Niccol (BBG)
PepsiCo Q3: revenue up 5.6% to $25.27bn, beat ests by ~1%, core EPS $2.34 beat by ~2%, cut FY26 core EPS growth outlook to 2.5-3% from the low end of 5-7%, with CEO Ramon Laguarta flagging urgency to lift North America performance (YF)
Amazon job cuts hit nearly 1,000, citing the company has "adjusted parts of its store business...to better enable us to deliver on our priorities." (YF)
Palantir jumped in early trade after Goldman Sachs upgraded the stock to Buy from Neutral with a $230 target, citing a shift to sovereign AI that could expand its addressable market (YF)
Iran & Energy
Trump said on Truth Social the US will not attack Iran before the 3 November midterms and is holding productive talks with Tehran, after saying late Wednesday renewed strikes were under consideration (CNBC)
Energy prices eased after Trump’s Iran comments, cooling a rally in long-dated Treasury yields from multi-decade highs, while consumer defensive and payments stocks including Walmart, Visa and Mastercard rebounded (TE)
Oil traders are increasingly tuning out Trump’s Iran rhetoric and reacting to evidence of physical supply and cargo-flow changes, with Again Capital’s John Kilduff likening the market to geopolitical roulette (BBG)
UKMTO said a tanker was struck by multiple projectiles north of Qatar with casualties, as weekly attacks on Hormuz shipping hit their highest level since the US-Iran conflict began (YF)
Tariffs
New York Fed researchers found tariffs added 2.9 percentage points to inflation across 67 goods categories by February, and prices for those items would have fallen without the levies (CNBC)
Central Banks
St Louis Fed President said more monetary policy firming will be required to return inflation to 2% in a timely manner, but he has not prejudged the late-October meeting (RT)
ECB accounts of the September meeting showed all policymakers saw inflation risks skewed higher, though Slovenia’s Primoz Dolenc said stable core inflation shows broader price pressures remain contained (RT)
BoE Chief Economist said central banks must stay focused on fighting inflation as global bond yields rise, after he was among three MPC members who voted for a September hike (RT)
BoE policymaker Megan Greene said UK employers look on course to raise pay by around 3.5% next year, more than would help return inflation to the 2% target (RT)
Economy
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Gold Miners | 86.72 | +1.47% |
| Silver Miners | 84.68 | +1.34% |
| Steel | 101.96 | -0.46% |
| Lithium & Battery Tech | 69.02 | -0.70% |
| Copper Miners | 82.22 | -1.63% |
| Strategic Metals | 60.58 | -2.10% |
| Uranium | 38.56 | -3.43% |
Industrials | ||
| Aerospace & Defense | 204.88 | +0.63% |
| Agriculture | 28.34 | -0.53% |
| Construction | 91.02 | -0.56% |
| Global Jets | 27.48 | -0.69% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 200.48 | -1.41% |
Renewables | ||
| Solar | 43.32 | -0.48% |
| Hydrogen | 42.2357 | -2.91% |
Technology | ||
| Cloud Computing | 28.99 | +0.69% |
| Cybersecurity | 47.94 | +0.17% |
| FinTech | 24.5503 | -0.36% |
| Data Center & Digital Infrastructure | 27.15 | -1.91% |
| Electric Vehicles | 32.6004 | -2.22% |
| Robotics & AI | 34.83 | -2.35% |
| Semiconductor | 563.28 | -3.35% |
ASX Today
CSL to move all current US plasma centres onto Haemonetics' NexSys platform by end-2027, sending Haemonetics shares up 12% (YF)
Guzman y Gomez reports Q1 FY27 network sales of $387.5m, up 18.8% on the pcp, with comp sales up 7.1% against 4.0% a year ago and three new Australian openings taking the network to 286. Reaffirms FY27 guidance of mid-single digit comp growth and underlying EBITDA of 6.7-6.9% of network sales from 6.2%, and extends the buyback by up to a further $100m beyond its 23 October end date (GYG)
What To Watch Today
Kerry here! Energy, Staples and Banks caught a bid on Wall Street. Though local miners are in for another challenging session.
Energy back in the spotlight: Oil is turning higher again, with Brent up ~8.5% since 29-Sep. The ASX 200 Energy index has climbed 3.3% from its 1-Oct low and reclaimed its 50-day moving average on Thursday. The S&P 500 Energy sector rallied 2.9% overnight and now sits within 1% of its 15-Sep record. US diesel futures surged 5.6% after a relatively shallow 10% pullback in recent weeks and are back within 3% of their own 15-Sep record. That puts classic energy names like Woodside and Santos, refiners Viva and Ampol, and possibly coal names back in focus
Miners not so much: Miners kept struggling overnight despite a softer US dollar and mostly lower yields. Gold miners were the exception, up 1.5% after a 3% dip in the prior session. Copper staged a sharp reversal, rallying as much as 1.9% intraday to US$6.80/lb before finishing 1.2% lower at US$6.59/lb. The early pop may have been driven by China's return from its week-long National Day holiday and a strike at Antofagasta's Centinela project in Chile. Chinese lithium carbonate futures followed a similar path, rallying as much as ~4.5% on Thursday before closing 1.2% lower at 117,300 yuan a tonne. The Global X Copper Miners ETF fell 1.6% overnight and the VanEck Rare Earths/Strategic Metals ETF lost 2.1%
Key Events
Stocks trading ex-dividend:
Fri 9 Oct: EQT Holdings (EQT) – $0.20
Mon 12 Oct: Civmec (CVL) – $0.035, Washington H. Soul Pattinson (SOL) – $0.63
Tue 13 Oct: Perenti (PRN) – $0.045, Star Combo Pharma (S66) – $0.003
Wed 14 Oct: United Overseas Australia (UOS) – $0.02
Thu 15 Oct: Acorn Capital Investment Fund (ACQ) – $0.035, Australian Foundation Investment Company (AFI) – $0.092, Cobram Estate Olives (CBO) – $0.045, Fat Prophets Global Contrarian Fund (FPC) – $0.03, Horizon Oil (HZN) – $0.01, K&S Corporation (KSC) – $0.06, Rivco Australia (RIV) – $0.018, WAM Research (WAX) – $0.05
Other ASX corporate actions today:
Dividends paid: AUB Group (AUB), Bisalloy Steel Group (BIS), Capricorn Metals (CMM), Fleetwood (FWD), Genesis Energy (GNE), Lindsay Australia (LAU), SGH (SGH), WiseTech Global (WTC), Wiseway Group (WWG)
IPOs: None
AGMs: None
Economic calendar (AEDT):
10:30 pm: Canadian unemployment rate