In a nutshell:
Chipmakers led a tech rebound that lifted the Nasdaq and S&P 500, though most S&P 500 stocks fell and the Dow finished slightly lower
Treasuries sold off as haven demand faded, with traders rebuilding bets on Fed hikes into next year ahead of next week's FOMC
European stocks slid after violent French protests, while Brent held near US$110 as Houthi-Saudi hostilities kept Gulf supply fears elevated
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,691 | +0.41% |
Dow Jones | 51,966 | -0.07% |
NASDAQ Comp | 26,431 | +1.11% |
Russell 2000 | 2,728 | +0.25% |
Global Indices | ||
 S&P/TSX | 35,929 | -0.69% |
 Shanghai Composite | 3,731 | +0.39% |
 DAX | 25,320 | -1.18% |
 Hang Seng | 24,187 | +0.52% |
 Nifty 50 | 73,853 | -1.17% |
 Nikkei 225 | 64,917 | -0.62% |
 FTSE 100 | 10,765 | -1.08% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,140.74 | -0.62% |
 Copper | 6.55 | +0.30% |
 WTI Oil | 103.15 | +1.72% |
Currency | ||
 AUD/USD | 0.6979 | -0.01% |
Cryptocurrency | ||
 Bitcoin (USD) | 81,927 | +1.00% |
 Ethereum (AUD) | 3,439 | +2.02% |
Miscellaneous | ||
US 10 Yr T-bond | 5.136 | +0.75% |
VIX | 18.44 | -7.75% |
US Sectors
Sector | % Chg |
|---|---|
| Consumer Discretionary | +2.73% |
| Information Technology | +1.19% |
| Communication Services | +0.28% |
| Materials | +0.08% |
| Consumer Staples | -0.42% |
| Health Care | -0.61% |
Sector | % Chg |
|---|---|
| Energy | -0.64% |
| Industrials | -0.65% |
| Financials | -0.79% |
| Real Estate | -1.17% |
| Utilities | -1.97% |
S&P 500 Session Chart
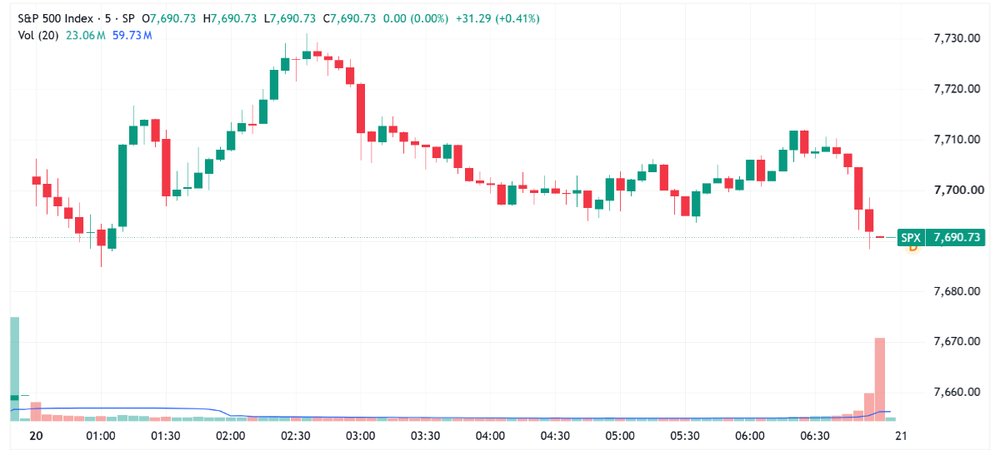
S&P 500 higher, but off best levels (Source: TradingView)
Overnight Markets
Major US benchmarks mostly higher, finished off best levels as an early chip-led surge faded through the afternoon
Chip stocks led the rebound from the Nasdaq 100's worst week since the April 2025 tariff turmoil, with the Philadelphia Semiconductor Index (+1.6%) snapping an eight-day losing streak, its longest in 18 years
Chipmakers led by Micron (+2.9%) and Intel (+2.4%) added nearly $250bn in market value even as roughly 70% of S&P 500 stocks fell
Treasuries fell as the tech rebound sapped haven demand, lifting yields six to eight basis points as traders rebuilt bets on Fed hikes next year while still pricing a December increase (BBG)
AI financing jitters lingered, with CoreWeave reversing early gains to close 0.4% lower despite a Goldman Sachs upgrade to buy, while its credit default swaps sit at distress levels after last week's 25% plunge (CNBC)
European stocks fell more than 1% after violent weekend protests that could force governments to lift spending, with French bond yields climbing much faster than German Bunds (AP)
Brent crude swung between US$107-110 a barrel before settling near US$109, as uncertainty over when the Iran war will allow energy flows to normalise kept prices volatile (AP)
Goldman Sachs' Ben Snider kept his 8,000 year-end S&P 500 target and sees the index reaching 8,700 by end-2027, modelling 36% earnings growth this year (YF)
The Q3 earnings bar is high, with analysts forecasting 29% year-on-year profit growth for S&P 500 companies, per FactSet, as Meta, Tesla and Netflix report this week (AP)
Stocks
Amazon jumped 5% after Morgan Stanley named it a top pick and raised its price target to $350 from $335, citing five upcoming catalysts (CNBC)
Meta price target lifted to $820 from $775 at Morgan Stanley, which reiterated its overweight rating ahead of Wednesday's Q3 result (CNBC)
Apple reiterated at buy by Bank of America, which said global average ship times for the iPhone Duo have stretched to 82 days (CNBC)
SpaceX rose 1.3% after Elon Musk pledged to give one SpaceX share to every kid in America next year (AP)
Geopolitics
Iran’s Kharg Island oil terminals have sat empty since late August, with crude exports falling from almost 1 million barrels a day in July to nothing as the US blockade bites (BBG)
Zelenskyy accused Trump of pressuring Ukraine to surrender to Russia, while offering a new proposal on Trump's demand that Kyiv stop striking Russian refineries (BBG)
Putin proposed a summit with Trump and Xi Jinping next month to discuss ending the war in Ukraine, the Wall Street Journal reported (BBG)
France saw one of its worst bouts of protest violence in years over the weekend, sending French equities to lead losses across Europe (YF)
Tariffs & Trade
Trump's steel tariffs are curbing US imports and lifting prices, helping Cleveland-Cliffs post a Q3 profit that topped estimates and sending its shares sharply higher (BBG)
Copper traders are growing wary of the bull market with no sign of US tariffs on the metal, after US imports helped drive LME prices to a record near $15,000 a tonne last month (BBG)
Central Banks
BofA economists kept their call for a Fed rate hike next week, arguing inflation has worsened since September, even as 85% of the market expects a hold (YF)
Economy
China's Q3 GDP grew 4.5% year-on-year, ahead of 4.4% estimates and up from a three-year low of 4.3%, as tech exports offset a deepening property slump (CNBC)
China's September retail sales rose 1.1% year-on-year, beating forecasts for 0.6% (CNBC)
China's September industrial output grew 5.5% year-on-year, in line with forecasts (CNBC)
China's fixed asset investment fell 7.2% year-on-year in January to September, while the urban unemployment rate held at 5.2% (CNBC)
US homes falling out of contract hit 14.5% in September, the highest share on record outside the early pandemic months, per Redfin data (YF)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Lithium & Battery Tech | 64.61 | +0.87% |
| Steel | 102.88 | +0.42% |
| Copper Miners | 79.69 | -0.36% |
| Uranium | 35.27 | -0.45% |
| Silver Miners | 81.88 | -0.75% |
| Gold Miners | 86.47 | -1.41% |
| Strategic Metals | 53.36 | -1.60% |
Industrials | ||
| Agriculture | 28.2 | -0.11% |
| Aerospace & Defense | 207.755 | -0.63% |
| Construction | 87.03 | -0.67% |
| Global Jets | 25.58 | -1.04% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 204.06 | +1.02% |
Renewables | ||
| Hydrogen | 37.18 | +0.49% |
| Solar | 41.31 | -1.29% |
Technology | ||
| Cloud Computing | 28.62 | +1.96% |
| Semiconductor | 501.93 | +1.73% |
| Cybersecurity | 44.87 | +1.20% |
| Robotics & AI | 33.35 | +1.00% |
| Electric Vehicles | 30.5947 | +0.71% |
| FinTech | 24.2198 | -0.21% |
| Data Center & Digital Infrastructure | 25.7 | -0.31% |
ASX Today
Bellevue Gold produces 35.6koz in the September quarter, down from 41.6koz, with AISC rising to $3,096/oz after the new mining contractor ramped up slower than planned. Deferred ounces will be recovered later and FY27 guidance of 150-170koz is unchanged. Hedge book cut to 57.5koz (BGL)
BHP holds FY27 guidance across all commodities despite Q1 copper output falling 19% to 400.7kt on lower feed grades, planned maintenance and severe weather in Chile. Iron ore of 66.5Mt was up 4% on pcp, with WAIO lifting 4%. Jansen potash on track for mid-CY27 (BHP)
Gentrack wins a contract with Momentum Energy to move its 200,000-plus Australian residential and business meter points onto the g2 billing platform, following a competitive evaluation. No contract value or revenue timing was disclosed (GTK)
HUB24 reports Q1 platform net inflows of $4.0bn, down 23% on pcp, with total FUA of $168.6bn up 15%. Platform FUA rose 18% to $143.7bn. Signed 45 new licensee agreements and added 211 advisers over the quarter (HUB)
Judo Capital reaffirms FY27 profit before tax guidance of $210-220m, with gross loans at $15.1bn and NIM tracking to plan. Impaired and 90-day past due loans rose to 3.16% from 2.90% at June, still below its through-the-cycle assumption. AAA pipeline of $1.9bn reflects SME caution (JDO)
Regis Resources produces 83.0koz at an AISC of $3,617/oz, in line with expectations, and maintains FY27 guidance on a stronger second half. Cash and bullion rose to $1.28bn, including a $51m Vault Minerals break fee. The Federal Court ruled the McPhillamys Section 10 Declaration invalid (RRL)
What To Watch Today
Not a whole lot. Not the most inspiring overnight lead, where tech/semis bounced but finished off best levels (e.g. Nasdaq up 1.11% vs. session highs of 1.81%). Breadth was weak, with the Equal-weight S&P 500 (-0.32%) underperforming the cap-weighted index by 73 bps, and the Dow finished fractionally lower. Our overnight ETF watchlist traded mostly lower, Rare Earth/Strategic Metals (-1.6%) hit a fresh 14-month low and now down 51% since 11-May, Gold Miners (-1.4%) softened as gold reversed a small intraday gain to finish 0.59% lower, most other resource-related ETFs fell around 0.5–1.0% lower.
Coal anyone? A few interesting data points to consider for the unloved sector – i) Chinese coal production fell 6.8% year-on-year to 385Mt in September, extending a run of annual declines that began in April, ii) recent coal deals (AngloCoal, Kestrel and Malabar) imply coal prices of US$300-500 a tonne, well-above where coal prices trade today and iii) coal has underperformed oil and LNG. The Chinese coal data on Monday was the likely driver behind a broad rally across names like Whitehaven, New Hope and Yancoal, all of which rallied around 5%.
Key Events
Key events
Stocks trading ex-dividend:
Tue 20 Oct: Clover Corporation (CLV) – $0.013, GQG Partners (GQG) – $0.033, Kingsgate Consolidated (KCN) – $0.10
Wed 21 Oct: None
Thu 22 Oct: N1 Holdings (N1H) – $0.004
Fri 23 Oct: None
Other ASX corporate actions today:
Earnings: None
IPOs: None
AGMs: Bendigo Bank (BEN), Codan (CDA), Meridian Energy (MEZ), Region Group (RGN)
Economic calendar (AEDT):
122:15 pm: China Loan Prime Rate
5:00 pm: UK Unemployment
11:30 pm: US Building Permits, Housing Starts