In a nutshell:
Chipmakers led a tech rebound that lifted the S&P 500 and Nasdaq as Americans voted in the midterms, even as Apple and most S&P 500 members lagged
Oil whipsawed as the US and Iran weighed fresh mediator proposals, although Tehran said it would not accept diplomacy based on coercion. Brent settled flat at US$104.5 a barrel, but whipsawed between US$107.2 and US$100.8
Meta drew up to US$58bn of orders for a US$15bn US dollar bond sale, a fresh test of investor appetite for Big Tech's AI debt
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,569 | +0.36% |
Dow Jones | 51,787 | -0.38% |
NASDAQ Comp | 25,372 | +0.83% |
Russell 2000 | 2,812 | +0.22% |
Global Indices | ||
 S&P/TSX | 35,532 | -0.75% |
 Shanghai Composite | 3,608 | -0.82% |
 DAX | 25,865 | -0.45% |
 Hang Seng | 23,526 | +0.57% |
 Nifty 50 | 76,918 | +1.62% |
 Nikkei 225 | 63,082 | -0.33% |
 FTSE 100 | 10,638 | -1.14% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 3,928.02 | -0.48% |
 Copper | 6.38 | -2.47% |
 WTI Oil | 96.81 | +0.36% |
Currency | ||
 AUD/USD | 0.6964 | -0.48% |
Cryptocurrency | ||
 Bitcoin (USD) | 77,801 | +1.43% |
 Ethereum (AUD) | 3,287 | +1.81% |
Miscellaneous | ||
US 10 Yr T-bond | 4.952 | +1.19% |
VIX | 20.91 | -1.14% |
US Sectors
Sector | % Chg |
|---|---|
| Information Technology | +1.31% |
| Industrials | +0.96% |
| Communication Services | +0.90% |
| Real Estate | +0.19% |
| Consumer Discretionary | -0.02% |
| Health Care | -0.30% |
Sector | % Chg |
|---|---|
| Utilities | -0.55% |
| Financials | -0.59% |
| Energy | -0.84% |
| Consumer Staples | -1.76% |
| Materials | -1.93% |
S&P 500 Session Chart
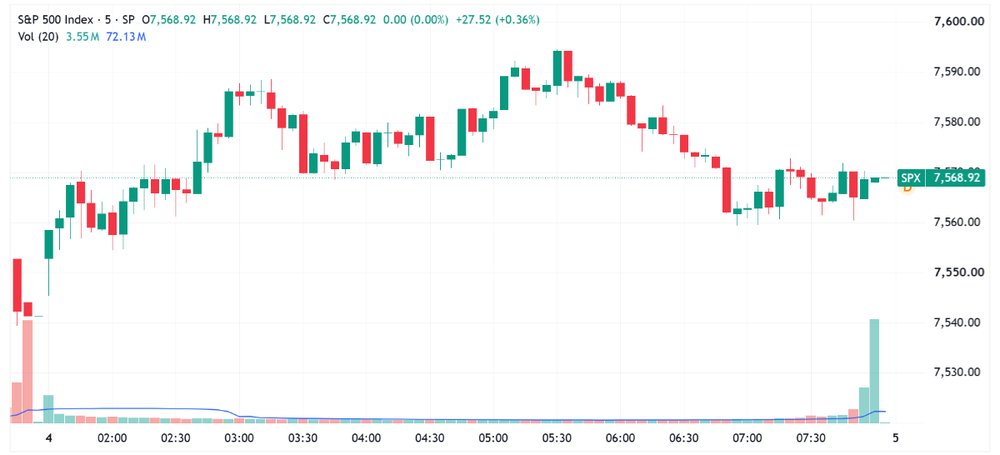
S&P 500 higher in a relatively choppy and rangebound session (Source: TradingView)
Overnight Markets
Major US benchmarks mostly higher in late trade, a chip rally tried to revive the AI trade and lifted the S&P 500 and Nasdaq
Breadth was soft, with seven of the eleven sectors trading lower and the Equal-weight S&P 500 (-0.33%) underperformed the cap-weighted index by 69 bps
Treasury yields briefly spiked after September job openings jumped to a four-month high, with the 10-year up 12 bps intraday to 5.03% before paring gains to finish 5 bps higher at 4.96%
Chip stocks bounced from a fresh bear market, the Philadelphia Semiconductor Index having closed Monday about 22% below its 6 October high (YF)
Goldman Sachs trader Bobby Molavi says 60% of the S&P 500 is in bear market territory, even with the index within about 3% of its record high (BBG)
UBS says low hedge fund positioning and favourable seasonality could fuel a year-end S&P 500 squeeze once the midterm vote is out of the way (BBG)
AllianceBernstein's Nelson Yu urges investors to diversify beyond AI after Monday's drop pushed the Nasdaq 100 into its third correction of the year (BBG)
US-listed bitcoin ETFs lost more than $1bn over two sessions as the Binance hack and midterm uncertainty weighed on crypto sentiment (BBG)
Traders are positioning for a Democratic sweep to tighten regulation of crypto and prediction markets, putting Trump-era digital finance winners at risk (BBG)
Stocks
AMD Q3 revenue up 45% to $13.4bn, ~2% ahead of ests, data centre up 97% to $8.55bn, adj. EPS $2.09 beat by ~7%. Q4 revenue guided to ~$17bn, ~5% above ests, as Helios rack shipments ramp. Shares up ~7% after hours
Apple fell 1.9%, bucking the tech rebound, after a mixed outlook in its first quarterly report under CEO John Ternus (BBG)
Meta set to raise $15bn from a five-part US dollar bond sale, drawing up to $58bn of orders, about 3.9 times the deal size, with a debut euro note to follow (BBG)
Shopify Q3 revenue $3.74bn, ~0.3% below ests and its first miss since 2022. GMV of $119.15bn also short, adjusted EPS $0.49 beat, shares down 8.0% (YF)
Palantir shares slipped 1.6% despite Q3 revenue and profit beating ests and a raised full-year revenue outlook, with US commercial sales topping US government revenue for the first time (YF)
CrowdStrike to buy AI security startups Fiddler and Dreadnode for a combined $495m (YF)
Geopolitics
The US and Iran are reviewing fresh mediator proposals to avoid a return to all-out war, with Qatar expecting feedback from both sides within two days (BBG)
Iranians face inflation of almost 80% and a rial that has lost half its value against the US dollar this year, as the US naval blockade strangles trade and oil exports (BBG)
Trump says he agreed with Netanyahu to cut about $4bn in annual US military aid to Israel by year-end, although the current 10-year aid deal runs through 2028 (BBG)
Iran's Foreign Ministry says Tehran will not accept diplomacy based on coercion, a day after Washington and Tehran both signalled openness to a settlement (CNBC)
Americans voted in midterm elections with control of Congress at stake, Polymarket giving Democrats a 76% chance of winning both chambers as of Tuesday morning (YF)
Tariffs
Trump says a US-Canada trade deal is coming very soon, adding that Canada would supply fertilizer to the US without tariffs as part of the agreement (YF)
Central Banks
No major overnight headlines
Economy
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Uranium | 33.03 | +0.30% |
| Lithium & Battery Tech | 60.1 | +0.08% |
| Strategic Metals | 49.8 | -0.92% |
| Steel | 99.34 | -1.20% |
| Silver Miners | 71.25 | -1.48% |
| Copper Miners | 71.72 | -1.54% |
| Gold Miners | 77.632 | -1.92% |
Industrials | ||
| Construction | 92.36 | +0.82% |
| Aerospace & Defense | 216.42 | +0.81% |
| Agriculture | 26.56 | -0.90% |
| Global Jets | 27.61 | -1.57% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 215.47 | +0.79% |
Renewables | ||
| Solar | 43.3393 | +3.02% |
| Hydrogen | 35.24 | +2.83% |
Technology | ||
| Semiconductor | 465.0 | +2.50% |
| Data Center & Digital Infrastructure | 25.33 | +1.60% |
| FinTech | 24.3 | +0.97% |
| Cybersecurity | 46.83 | +0.77% |
| Electric Vehicles | 28.9508 | +0.31% |
| Cloud Computing | 27.43 | +0.29% |
| Robotics & AI | 32.32 | +0.15% |
ASX Today
City Chic Collective expects positive EBIT in 1H FY27 and a positive cash balance with no drawn debt, after August’s step down in promotional activity lifted group trading gross margin 240bps. Revenue ex-wholesale fell 1.7%, but ANZ comparable store sales rose 15.4% and full-price stores jumped 19.6% (CCX)
Goodman Group targets FY27 operating EPS growth of 9% and a 30.0 cents distribution, with the total portfolio lifting to $90.0bn. Annual like-for-like NPI growth of 4.0% (6.2% ex Greater China) and occupancy of 95.5% as Chinese market rents continue to reset (GMG)
Goodman Group holds development WIP at $19.7bn across 51 projects on an 8.3% yield on cost, with data centres 79% of the book but just 31% precommitted. Global power bank rises to 6.6 GW, 3.6 GW secured, and full-building hyperscale negotiations are advanced on several sites (GMG)
What To Watch Today
RBA recap: The RBA voted 6-3 to hike 25 bps to 4.85%, citing a “materially higher” inflation outlook and an unemployment rate of 5%. The three dissenters softened the tightening bias, even as the statement closed by saying further tightening in financial conditions is warranted to return inflation to target.
3-year tanks, REITs surge: Markets took the decision well, with the Aussie 3-year down 7 bps to 4.78%, its lowest since 7-Sep. Yield-sensitive or consumer-facing stocks ripped, including Real Estate (+2.8%), Discretionary (+1.8%), Telcos (+1.7%) and Staples (+1.2%). JB Hi-Fi was up ~1.7% heading into the decision and closed 3.0% higher. Charter Hall was tracking around breakeven and also finished up 3.0%. You get the idea. It reinforces a rotation that’s been building for the past 2-3 weeks, where REITs and retailers have bottomed out of a sharp drawdown and started to turn, at the expense of miners and tech.
More miner weakness: Base and precious metals faded Monday’s tentative bounce, with copper down 2.0% to US$6.47/lb (off session lows of -3.3%), aluminium down 1.7% to US$3,027/t and gold down 0.4% to US$3,927/oz. That kept the pressure on our resource-related overnight ETFs, most of which struggled to bounce on Monday anyway. The Global X Copper Miners ETF finished 1.5% higher from session highs of 3.5%, then fell another 1.5% overnight to its lowest since 30-Mar. For all the talk about supply-side constraints and a commodity supercycle, the price action is saying the opposite.
Key Events
Stocks trading ex-dividend:
Wed 4 Nov: Qualitas Real Estate Income Fund (QRI) – $0.011
Thu 5 Nov: Future Generation Global (FGG) – $0.042
Fri 6 Nov: New Murchison Gold (NMG) – $0.003
Mon 9 Nov: Clime Capital (CAM) – $0.005, Future Generation Australia (FGX) – $0.038, NAOS Ex-50 Opportunities Company (NAC) – $0.016, NAOS Small Cap Opportunities Company (NSC) – $0.01
Other ASX corporate actions today:
Economic calendar (AEDT):
9:00 am: Australia Ai Group Industry Index
9:00 pm: Eurozone Inflation
2:00 am: US ISM Services PMI