In a nutshell:
The AI selloff deepened as Intel's guidance miss and Amazon's cash burn handed the Nasdaq its worst day since June
Fed hawks lined up behind more rate hikes, with Dallas Fed President Lorie Logan calling for at least two more as gold slid to a one-year low
Oil held its October gains after fresh Hormuz tanker attacks, while Trump said the US could finish off Iran's remaining nuclear sites in ten minutes
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,580 | -1.82% |
Dow Jones | 51,770 | -1.09% |
NASDAQ Comp | 25,437 | -2.86% |
Russell 2000 | 2,812 | -1.66% |
Global Indices | ||
 S&P/TSX | 35,620 | -1.74% |
 Shanghai Composite | 3,599 | -1.44% |
 DAX | 25,818 | -0.85% |
 Hang Seng | 23,294 | +1.46% |
 Nifty 50 | 74,460 | +0.42% |
 Nikkei 225 | 63,290 | -2.12% |
 FTSE 100 | 10,730 | +0.07% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 3,875.84 | -3.62% |
 Copper | 6.46 | -1.86% |
 WTI Oil | 104.12 | +2.08% |
Currency | ||
 AUD/USD | 0.7026 | -0.09% |
Cryptocurrency | ||
 Bitcoin (USD) | 77,813 | +0.37% |
 Ethereum (AUD) | 3,219 | +0.54% |
Miscellaneous | ||
US 10 Yr T-bond | 4.929 | -1.20% |
VIX | 19.42 | +12.91% |
US Sectors
Sector | % Chg |
|---|---|
| Energy | +1.91% |
| Consumer Staples | +1.38% |
| Utilities | +0.64% |
| Health Care | +0.43% |
| Real Estate | +0.15% |
| Materials | +0.04% |
Sector | % Chg |
|---|---|
| Financials | -0.74% |
| Consumer Discretionary | -0.86% |
| Communication Services | -1.11% |
| Industrials | -1.57% |
| Information Technology | -4.24% |
S&P 500 Session Chart
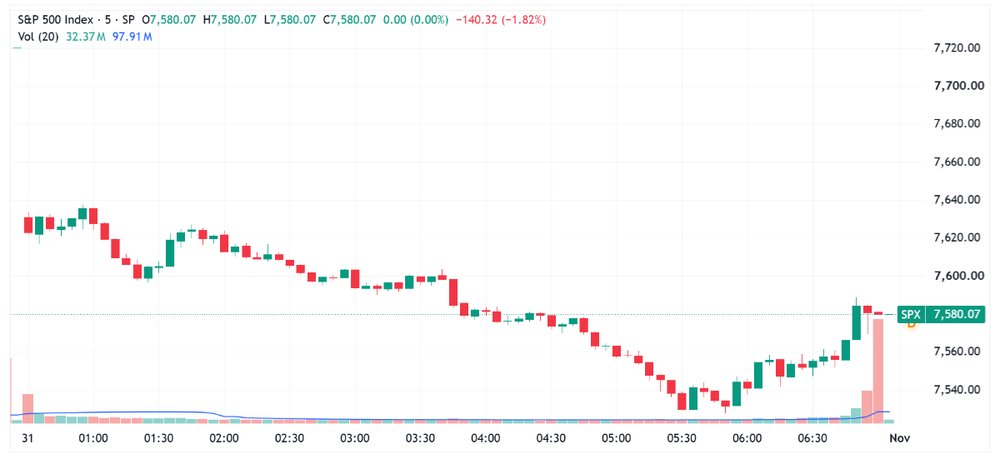
S&P 500 gaps down, trends lower and musters up a small bounce in the last hour of trade (Source: TradingView)
Overnight Markets
Major US benchmarks sharply lower, finished off worst levels after the Nasdaq 100 briefly dipped into correction territory
US weekly recap: S&P 500 (-1.82%), Nasdaq (-2.86%), Dow (-0.85%) and Russell 2000 (+1.29%)
Chip and PC hardware names slumped on Intel's warning, with the chip index down 7.2% and off more than 15% for October. AMD fell 10.9%, Dell 10.8% and HP 9.6%
VIX spiked to 23.93 intraday before easing to close at 19.41 as buyers lifted the Nasdaq 100 back above the correction line into the close
Gold slid to a one-year low below $3,900 an ounce and silver fell under $50 for the first time since November 2025 as higher-for-longer rate bets outweighed haven demand
Binance resumed withdrawals on Sunday following a record $6.3bn hack, saying it has restored backing for 90% of affected user assets and will absorb the losses (CNBC)
82% of the 299 S&P 500 companies that have reported beat ests, with Q3 earnings growth now tracking 31.6% year-on-year, per LSEG (RT)
AI enthusiasm is collapsing after Big Tech earnings darkened the outlook, with even companies generating stable free cash flow getting sold (BBG)
Big Tech holds more than $3 trillion in AI spending commitments across Alphabet, Meta, Microsoft, Amazon and Oracle, spanning leases, buildings and energy (BBG)
Companies falling short of lofty AI expectations are getting punished, with the week a test of whether the spending will deliver a return, says Wealthspire's Oliver Pursche (RT)
Stocks
Intel guided Q4 revenue to $15-16bn and EPS to 25 cents, well short of $17.1bn and 43 cents ests, warning of slowing PC demand. Shares sank almost 29%, the worst day since the 1970s (CNBC)
Amazon Q3 AWS revenue up 39% to $46bn, the fastest growth in nearly five years, but EPS of $1.89 missed ests by ~4% and core e-commerce growth was the slowest in three years. Capex topped forecasts. Shares pared a 7% after-hours slide to close down 1.4% (BBG)
Exxon Mobil Q3 profit doubled to $15.4bn from $7.5bn a year earlier, beating ests as war-driven supply disruptions lifted refining margins. Shares rose more than 2% (CNBC)
Chevron Q3 net income up nearly 200% to $9.9bn with revenue ahead of ests, as soaring margins from Middle East supply disruptions flowed through. Shares closed higher (CNBC)
Starbucks forecast a decline in annual revenue as it divests its China business. Shares dipped 1.8% (RT)
Samsung hosted OpenAI CEO Sam Altman and about 50 executives in South Korea on Saturday to deepen cooperation on memory chips and AI infrastructure as global shortages intensify (BBG)
DeepSeek released a prototype autonomous coding agent dubbed Super-Agent, aiming to challenge Anthropic's Claude Code (BBG)
Geopolitics
Trump says the US can take out Iran's remaining one or two nuclear sites in ten minutes, after a Saturday call with Netanyahu as Washington weighs resuming strikes (YF)
California Governor Gavin Newsom warned federal judges the Trump administration may seek warrants to seize ballots and election records before midterm results are certified (BBG)
New Zealand stocks and the kiwi face a test as polls point to a tight 7 November election and drawn-out coalition talks. The NZ dollar is down about 6% since late August (BBG)
Tariffs & Trade
Central Banks
Dallas Fed Logan says the FOMC needs at least two more 25 bps hikes, adding a gradual pace can help households and markets adapt (BBG)
St Louis Fed Musalem says another hike is needed soon, arguing earlier incremental moves are less disruptive than abrupt ones later (CNBC)
Richmond Fed Barkin points to high inflation, solid demand and relatively low unemployment in the first round of post-FOMC commentary (RT)
US jobs pickup may keep the Fed on track to hike again, with October payrolls forecast to more than double to 65,000 and unemployment steady at 4.2% (BBG)
Economy
China's official manufacturing PMI fell to 49.3 in October from 50.1, missing 50.0 ests and slipping back into contraction
South Korea's October exports jumped 93.7% year-on-year to a record $115.3bn, with semiconductor shipments up 259% to $56.4bn
Euro area GDP grew 0.4% quarter-on-quarter in Q3, slowing from 0.6% in Q2 as France contracted 0.1%
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Lithium & Battery Tech | 59.81 | -1.85% |
| Steel | 99.3978 | -1.88% |
| Strategic Metals | 49.99 | -5.12% |
| Copper Miners | 71.96 | -5.19% |
| Gold Miners | 77.09 | -5.21% |
| Uranium | 33.73 | -5.57% |
| Silver Miners | 71.25 | -5.58% |
Industrials | ||
| Agriculture | 26.89 | -1.03% |
| Construction | 89.67 | -1.23% |
| Global Jets | 26.93 | -2.04% |
| Aerospace & Defense | 209.74 | -2.13% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 217.61 | -0.11% |
Renewables | ||
| Solar | 40.2 | -2.38% |
| Hydrogen | 34.94 | -4.33% |
Technology | ||
| FinTech | 23.8861 | -1.50% |
| Data Center & Digital Infrastructure | 25.57 | -2.96% |
| Cybersecurity | 49.37 | -3.23% |
| Robotics & AI | 32.22 | -3.59% |
| Cloud Computing | 28.02 | -4.17% |
| Electric Vehicles | 29.03 | -4.19% |
| Semiconductor | 471.51 | -8.24% |
ASX Today
KMD Brands grants exclusivity to US consumer brand group Bluestar Alliance to complete confirmatory due diligence on a possible acquisition of all KMD shares, following the approaches flagged at its FY26 result. Long stop date of 23 December, with no certainty of a binding proposal (KMD)
Macmahon Holdings completes its $75m acquisition of Aspect Engineering Solutions after the ACCC waived notification, with $30m upfront and the balance tied to retention and performance hurdles. Indicative underlying EPS accretion of ~6.2% from inception, before synergies (MAH)
Regis Resources extends mineralisation in its half-year exploration update, with 6.2m at 1.9g/t Au around 200m south of the Garden Well South reserve and 14.3m at 4.6g/t at Beamish South, where a resource update is underway. Tropicana’s Havana South returned 12m at 6.1g/t (RRL)
St Barbara defines a maiden underground resource at Old Austen Down-Plunge of 4.8Mt at 3.4g/t for 0.5Moz, sitting entirely outside the open pit resource updated in July. An extensive diamond campaign is being planned to upgrade the Inferred portion (SBM)
St Barbara gets Nova Scotia sign-off to restart ore processing at Touquoy, with the mill refurbishment ahead of schedule and first ore on 3 November. Canada’s impact agency will require a duplicative federal assessment for the 15-Mile hub, putting the mid-2028 construction start at risk (SBM)
St Barbara approves an on-market buy-back of up to 100m shares from around 23 November, with all shares acquired to be cancelled. Sits within the 10/12 limit so no shareholder approval is needed. CEO Andrew Strelein says the stock remains significantly undervalued (SBM)
Westpac reports FY26 net profit ex-notable items of $6.99bn, in line with ests, on revenue up 1% to $22.7bn and pre-provision profit up 4% to $10.9bn. Deposits grew 6% and lending 5%. Final dividend of 77c takes FY26 to $1.54, up 1% (WBC)
What To Watch Today
AI and miner carnage continues: The awkward juncture continues, where solid Mag-7 earnings are being scrutinised for high AI infrastructure spending and negative cash flow. The Nasdaq is now 7.8% off its 6-Oct record and dragging down our all-important resource sector along with it. Overnight, gold tanked 3.6% to undercut recent ~US$3,970 lows, now trading at a fresh 12-month low. Copper fell 1.4% to US$6.56/lb, so still in its recent trading range. Meanwhile, it was a sea of red for pretty much our entire overnight ETF watchlist, led by Silver Miners (-5.8%), Uranium (-5.5%), Gold Miners (-5.2%), Copper Miners (-5.1%), Rare Earths/Strategic Metals (-5.1%) and Tech-Software (-3.4%). You’ve got the likes of uranium and rare earths/strategic metals continuing to spiral into the abyss, while the copper ETF (down 25% since 27-Aug) is testing those Mar-26 and Jul-26 lows, threatening to roll over.
The pivot continues: On the flip side, the Equal-weight S&P 500 recorded its fourth-straight week of gains (despite falling 0.79% last Friday). Wall Street continues to experience a pivot into Energy and defensives like Staples, Utilities and Healthcare. This has, and is, a theme to watch out for. As a name like BHP falters, it's probably worth keeping an eye out for an unfortunate rotation into the likes of CBA.
Westpac results: Speaking of banks, Westpac reports its FY26 result today. Bank of Queensland reported its FY26 result on 15-Oct, where NIM of 1.70% was running ahead of 1.68% ests, with 2H26 NIM of 1.73% vs. 1.70% ests. While its outlook pointed to a modern 1H27 NIM uplift and return to home lending growth. So a positive read through from a recent result.
Key Events
Stocks trading ex-dividend:
Mon 2 Nov: Djerriwarrh Investments (DJW) – $0.037, Kapstream Investment Trust (KIT) – $0.014, La Trobe Private Credit Fund (LF1) – $0.013, N1 Holdings (N1H) – $0.004, Pengana Global Private Credit Trust (PCX) – $0.013, Revolution Private Credit Income Trust (REV) – $0.014
Tue 3 Nov: WAM Global (WGB) – $0.066
Wed 4 Nov: None
Thu 5 Nov: Future Generation Global (FGG) – $0.042
Fri 6 Nov: New Murchison Gold (NMG) – $0.003
Mon 9 Nov: Clime Capital (CAM) – $0.005, Future Generation Australia (FGX) – $0.038, NAOS Ex-50 Opportunities Company (NAC) – $0.016, NAOS Small Cap Opportunities Company (NSC) – $0.01
Other ASX corporate actions today:
Dividends paid: None
Earnings: Westpac (WBC)
IPOs: None
AGMs: None
Economic calendar (AEDT):
11:30 am: Australia Building Permits
12:45 pm: China RatingDog Manufacturing PMI
2:00 am: US ISM Manufacturing PMI