In a nutshell:
Hot September CPI revived Fed hike bets, sparking a tech-led selloff while defensives held up
Wild price action for yields, with the US 2-year finished flat at 4.80% but briefly surged 15 bps to 4.95%, the US 10-year is down 2 bps despite spiking 11 bps to 5.32%
AI infrastructure stress deepened as CoreWeave bonds hit distressed levels and a gauge of chip giants extended its slide from a June peak to 20%
Middle East escalation kept Brent above US$105 after the Houthis hit Aramco's headquarters and Iran flagged new tanker tactics
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,719 | -1.11% |
Dow Jones | 51,621 | -0.09% |
NASDAQ Comp | 26,693 | -1.88% |
Russell 2000 | 2,730 | -1.93% |
Global Indices | ||
 S&P/TSX | 35,584 | -1.11% |
 Shanghai Composite | 3,767 | -0.88% |
 DAX | 25,299 | +0.15% |
 Hang Seng | 24,314 | -0.13% |
 Nifty 50 | 72,782 | -0.34% |
 Nikkei 225 | 67,744 | -0.05% |
 FTSE 100 | 10,725 | +0.70% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,098.01 | -1.53% |
 Copper | 6.56 | -1.71% |
 WTI Oil | 95.08 | +1.00% |
Currency | ||
 AUD/USD | 0.6971 | -0.17% |
Cryptocurrency | ||
 Bitcoin (USD) | 81,697 | -1.97% |
 Ethereum (AUD) | 3,467 | -3.66% |
Miscellaneous | ||
US 10 Yr T-bond | 5.19 | -0.52% |
VIX | 16.87 | +10.48% |
US Sectors
Sector | % Chg |
|---|---|
| Health Care | +2.44% |
| Consumer Staples | +2.38% |
| Energy | +0.80% |
| Utilities | -0.31% |
| Materials | -0.44% |
| Financials | -0.61% |
Sector | % Chg |
|---|---|
| Real Estate | -0.82% |
| Industrials | -0.96% |
| Consumer Discretionary | -1.10% |
| Communication Services | -1.73% |
| Information Technology | -2.62% |
S&P 500 Session Chart
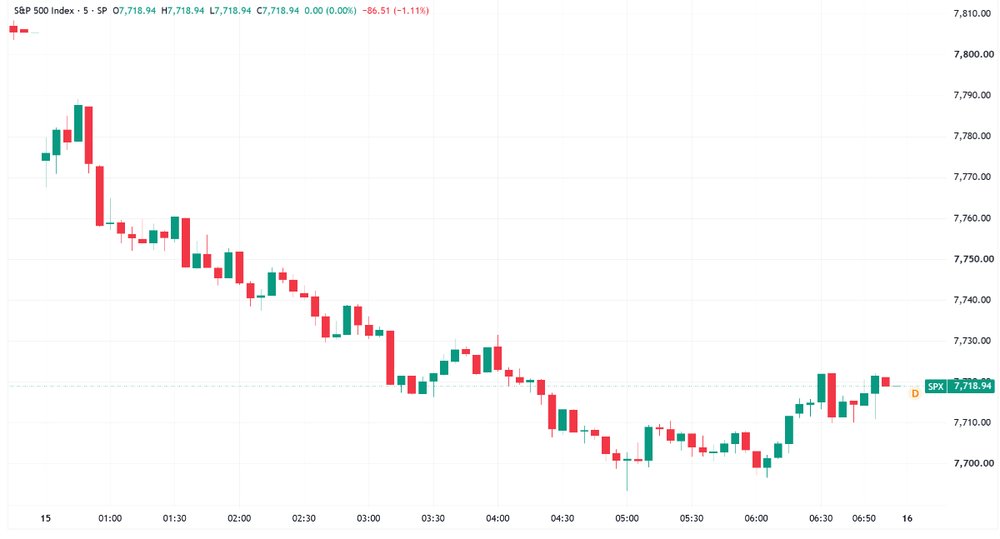
S&P 500 trended lower to finish near worst levels (Source: TradingView)
Overnight Markets
Major US benchmarks lower, finished off worst levels, as hotter-than-expected CPI print revived Fed hike bets and chipmakers extended their rout
Philadelphia Semiconductor Index (SOX) fell 4.3%, taking its slide to 11.6% since 6 October, with Nvidia (-3.1%), Micron (-4.1%) and Broadcom (-3.1%) among the heavyweights in the red
Bond yields whipsawed on the print, with the 2-year briefly surging 15 bps to 4.95% but finished the session fractionally higher at 4.80%, the 10-year also jumped 11 bps to 5.32% but finished 2 bps lower at 5.19%
Traders now price more than a 62% chance of at least one more Fed hike before year-end, including a 40% chance of a half-point increase, double the odds a day earlier (CNBC)
Neocloud stocks tumbled after Gartner forecast 80% of the neocloud market will cease to exist by 2030, hitting CoreWeave, Nebius and IREN (YF)
Micron, Nvidia and Broadcom are expected to deliver nearly 40% of S&P 500 third-quarter earnings growth, according to Goldman Sachs data (Axios)
AI selloff a recalibration, not a break, in the AI investment story, says UBS Chief Investment Office's Ulrike Hoffmann-Burchardi (BBG)
Traders hid in value and lower-beta sectors as the "higher-yield bogeyman" returned to haunt stocks, says Bloomberg Markets Live strategist Tatiana Darie (BBG)
Stocks
Bank of America Q3: profit down 17% to $6.93bn, EPS 91c missed ests by ~17% (or ~2% excluding a $1.2bn Treasury anti-money laundering penalty), bond trading revenue down 17% to $2.55bn, shares fell about 8%, steepest drop since April 2025 (BBG)
Morgan Stanley Q3: EPS $3.03 beat ests by ~4%, equity trading revenue up 41% to $5.8bn versus $4.9bn ests, wealth unit drew a record $232bn in net new assets with about half tied to IPOs, shares slipped despite the beat (BBG)
ASML 3Q26 sales hit a record €11.7bn with a record 57.5% gross margin. Lifted 2026 sales outlook to €44bn to €45bn and guided fourth-quarter sales of €14.2bn to €15.2bn, with some customers discussing orders for 2029 and 2030 (YF)
Netflix is cutting about 6% of its workforce, its biggest round of job cuts since 2022 (WSJ)
CoreWeave shares fell as much as 17%, the biggest intraday drop since February, as its bonds slid to distressed levels and CEO Mike Intrator told staff the market is acting irrationally and the backlog covers its debt (BBG)
A broader AI infrastructure selloff hit Oracle and Dell, with losses across major AI names erasing about $80bn in market value as rising borrowing costs rattled the capital-intensive sector (RT)
Geopolitics & Energy
Singapore-flagged cargo ship GFS Pride sank in the Strait of Hormuz after a strike by unknown projectiles sparked a fire, with all 21 crew evacuated without injury, Singapore’s port authority said (BBG)
Revolutionary Guard chief Ali Ozmaei said Iran is impatient to sink US warships near Hormuz, while Trump maintained American forces will not attack Iran before the November midterms (CNBC)
Houthis launched missile and drone strikes across Saudi Arabia, including a hit that damaged Saudi Aramco's headquarters in Dhahran (BBG)
Iran deploying new tactics to target ships in a bid to keep oil prices high, Iranian officials say, with one saying the different tactics began about 10 days ago (RT)
IEA says diesel shortages could persist well into 2027 as conflicts curb Middle East and Russian supply, with record prices driving stock draws ahead of peak winter demand (RT)
Tariffs
Michigan Republican Senate candidate Mike Rogers broke with Trump on Canadian tariffs, calling for an end to the trade fight to lower prices after backing tariffs as necessary in August (CNBC)
New York Fed research found Trump’s tariffs added 2.9 percentage points to consumer goods inflation through February, pushing up prices of American-made goods as well as imports (FN)
Central Banks
Fed October decision now a closer call, futures price roughly even odds of a hike at the 27-28 October meeting after CPI, Raymond James' Eugenio Aleman says inflation is broadening out (RT)
Traders briefly priced two Fed hikes by the end of January following the broad upswing in September consumer prices (BBG)
TD Securities still expects an October hold, says the CPI report raises the odds of a hike this month but sees the Fed opting for December (BBG)
The Fed’s Beige Book showed half of its 12 districts reporting robust or intensifying price pressures as higher energy costs spread through local economies, with tariffs and insurance also cited (BBG)
Chicago Fed President called the hot CPI print unacceptable, while Richmond Fed President Tom Barkin said it ran too hot and kept the October decision open (FXStreet)
Economy
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Steel | 102.46 | -0.55% |
| Lithium & Battery Tech | 66.38 | -1.88% |
| Strategic Metals | 55.78 | -2.91% |
| Copper Miners | 80.82 | -4.24% |
| Gold Miners | 83.4 | -4.40% |
| Uranium | 35.54 | -4.92% |
| Silver Miners | 79.53 | -5.45% |
Industrials | ||
| Aerospace & Defense | 204.24 | +0.12% |
| Agriculture | 28.26 | -0.60% |
| Construction | 87.23 | -2.66% |
| Global Jets | 25.84 | -3.58% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 203.25 | +1.61% |
Renewables | ||
| Hydrogen | 39.17 | -3.88% |
| Solar | 42.64 | -3.92% |
Technology | ||
| Robotics & AI | 34.11 | -2.43% |
| Electric Vehicles | 31.1893 | -2.66% |
| Cloud Computing | 28.88 | -2.92% |
| FinTech | 24.1 | -3.33% |
| Data Center & Digital Infrastructure | 26.29 | -3.81% |
| Cybersecurity | 46.56 | -4.14% |
| Semiconductor | 519.42 | -4.50% |
ASX Today
AMP reports 3Q26 Platforms net cashflows of $1.5bn, up 20% on the pcp, with Superannuation & Investments net outflows narrowing to $138m from $241m. Total wealth AUM of $168bn across Australia and NZ. Has now delivered $75m of its $150m on-market buyback (AMP)
Bank of Queensland delivers FY26 statutory NPAT of $250m, up 88%, and cash earnings of $358m, up 7%, though cash EPS fell 7% to 54.4c. NIM up 6bps to 1.70% as home lending shrank $4.6bn and commercial lending grew $2.1bn. 2H26 dividend of 20c (BOQ)
Contact Energy generated 1,069GWh in September at a unit cost of NZ$37.83/MWh, down from NZ$48.79 a year earlier, as mass market electricity and gas sales rose to 484GWh from 372GWh. South Island controlled storage sat at 135% of mean at 13 October (CEN)
DigiCo Infrastructure REIT executes a 15-year, 71MW contract at SYD1 with an investment grade global technology firm, taking the site to 100% contracted across 88MW. Australian portfolio WALE lifts from ~3 years to over 10 years. The 52MW expansion is fully funded with no new equity (DGT)
Netwealth Group lifts total FUA 2.5% to a record $139.2bn in Q1 FY27, up 15.2% on the pcp, with FUA net flows of $3.6bn. FUM net flows hit a quarterly record of $2.4bn to take total FUM to $36.6bn. Added 3,822 net new accounts (NWL)
SHAPE Australia awarded a ~$800m contract by DigiCo for the 52MW capacity expansion at the SYD1 data centre campus, lifting the site to 88MW. Secured off its completed 20MW Stage 1 upgrade and expected to materially contribute to revenue across FY27 and FY28 (SHA)
What To Watch Today
Kerry here. Ooft. US CPI came in slightly hotter than expected, but the real problem is services ex-energy, which rose 0.4% month-on-month. That measure has been gradually accelerating in recent months and points to widespread moderate price pressure. Fed rate hike bets inched higher, though one 25 bp hike by year end remains the base case (62.9% likelihood, from 66.3% a week ago, so nothing crazy). An October hike may win over a few of the more hawkish Fed officials, but Waller and Jefferson have both backed a “go slow” approach.
Defensives take the spotlight: 17 of the 30 Dow constituents finished higher as health care and staples both rallied around 2.4%, a very real pivot into defensive sectors. The S&P 500 energy index also notched its third straight record high. It’s a shift worth watching, and probably why ASX 200 futures are down just 0.2%
Commodities smashed:A stronger US dollar, the Fed implications and yield volatility drove a broad-based commodity selloff. Silver tanked 6% to US$55.6/oz, gold fell 1.3% to US$4,105/oz, copper dropped 1.6% to US$6.67/lb and aluminium slipped 1.5% to US$2,975/t. Resource equities fell even harder. The Global X Uranium ETF tumbled 4.9% and is now down 15% over the past six sessions, its lowest level since August 2025. The VanEck Gold Miners ETF sank 4.4%, undercutting its 200-day moving average to hit a two-month low. The Global X Copper Miners ETF fell 4.2% but closed just above its 200-day. Copper miners had been holding up well given high copper prices but have started to roll over, while uranium and lithium names have moved vertically lower. Expect a fairly weak session for local miners
Key Events
Stocks trading ex-dividend:
Thu 15 Oct: Acorn Capital Investment Fund (ACQ) – $0.035, Australian Foundation Investment Company (AFI) – $0.092, Cobram Estate Olives (CBO) – $0.045, Fat Prophets Global Contrarian Fund (FPC) – $0.03, Horizon Oil (HZN) – $0.01, K&S Corporation (KSC) – $0.06, Rivco Australia (RIV) – $0.018, WAM Research (WAX) – $0.05
Fri 16 Oct: Gowing Bros (GOW) – $0.03, WAM Microcap (WMI) – $0.053
Mon 19 Oct: FFI Holdings (FFI) – $0.125, Solaris Australian Equity Income Plus (SET) – $0.007, WAM Income Maximiser (WMX) – $0.007
Tue 20 Oct: Clover Corporation (CLV) – $0.013, Kingsgate Consolidated (KCN) – $0.1
Other ASX corporate actions today:
Dividends paid: Cue Energy Resources (CUE), DPM Metals (DPM), Garda Property (GDF), Integrated Research (IRI), Lovisa (LOV), Monash IVF (MVF), New Hope (NHC), Northern Star Resources (NST), Sims (SGM), South32 (S32), Virgin Australia (VGN), Vulcan Steel (VSL)
IPOs: None
AGMs: ARB Corp (ARB) – 9:30 am, Treasury Wine Estates (TWE) – 10:00 am, Australian United Investment Company (AUI) – 11:00 am, South32 (S32) – 12:00 pm
Economic calendar (AEDT):
10:30 am: Australia Unemployment
4:00 pm: UK GDP August
10:30 pm: US PPI