In a nutshell:
Wall Street capped its worst week since June as the AI selloff spread from chipmakers to megacaps, with CoreWeave's credit stress the focal point
Brent pushed back above US$109 as Iran claimed tanker mine strikes in Hormuz and US lawmakers moved to block Trump's Russian diesel deal
Hawkish central bank rhetoric stayed in play with the BoJ's Ueda and ECB officials flagging further tightening, while US 10-year yields held around 5.1%
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,659 | -1.09% |
Dow Jones | 52,002 | -0.34% |
NASDAQ Comp | 26,140 | -2.14% |
Russell 2000 | 2,721 | -1.66% |
Global Indices | ||
 S&P/TSX | 36,177 | +0.11% |
 Shanghai Composite | 3,716 | +0.24% |
 DAX | 25,623 | +0.95% |
 Hang Seng | 24,187 | +0.52% |
 Nifty 50 | 74,729 | +0.56% |
 Nikkei 225 | 65,324 | +1.39% |
 FTSE 100 | 10,882 | +0.38% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,166.39 | -0.11% |
 Copper | 6.53 | +0.30% |
 WTI Oil | 101.41 | +3.51% |
Currency | ||
 AUD/USD | 0.6968 | +0.31% |
Cryptocurrency | ||
 Bitcoin (USD) | 80,857 | -0.23% |
 Ethereum (AUD) | 3,382 | -2.83% |
Miscellaneous | ||
US 10 Yr T-bond | 5.098 | +0.18% |
VIX | 19.99 | +21.45% |
US Sectors
Sector | % Chg |
|---|---|
| Energy | +2.46% |
| Utilities | +1.40% |
| Consumer Staples | +1.31% |
| Materials | +0.68% |
| Financials | +0.49% |
| Real Estate | +0.38% |
Sector | % Chg |
|---|---|
| Industrials | -0.05% |
| Health Care | -0.26% |
| Consumer Discretionary | -1.17% |
| Communication Services | -2.45% |
| Information Technology | -2.54% |
S&P 500 Session Chart
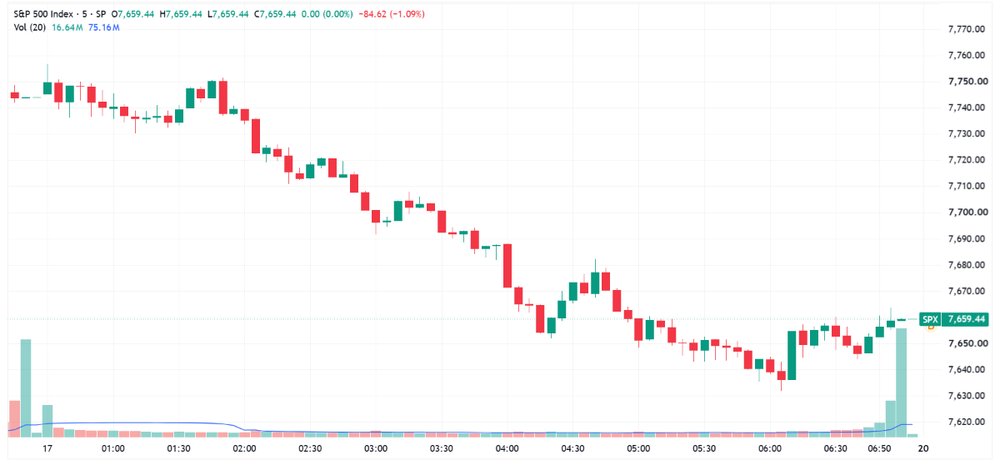
S&P 500 trended lower to finish slightly off worst levels (Source: TradingView)
Overnight Markets
Major US benchmarks trended lower to finish near worst levels, with the S&P 500 and Nasdaq posting their worst week since June
Chipmakers fell for an eighth straight day, the longest losing streak since 2008, sending the Nasdaq 100 to its worst week since the April 2025 tariff turmoil
Micron fell 5.6%, AMD 6%, Broadcom 4.5% and Intel 5.8%, with 68 of the S&P 500's 75 tech stocks closing lower (YF)
VIX spiked 21% to 19.9, the highest since June as the tech rout deepened into Friday's close
CoreWeave sank nearly 12%, losing a quarter of its value this week, as five-year CDS topped 1,000 basis points and a 2031 bond yield neared 16% (CNBC)
South Korea's Kospi logged its worst week since 2008, falling more than 14% on AI worries and now nearly 40% below its June high (CNBC)
Nvidia's Jensen Huang says the AI rout "is going to pass", arguing the technology will be transformative for every industry (BBG)
Cathie Wood's ARK added CoreWeave and Cerebras during the week's declines, comparing CoreWeave's debt stress to Coinbase's before the crypto boom (BBG)
Oaktree's Howard Marks unconvinced by AI bubble calls even as billionaires including Ray Dalio and Michael Novogratz warn of bubble conditions (BBG)
Stocks
Apple iPhone Duo shipping estimates slipped into January within minutes of preorders opening, with retail stores selling out of launch-day stock of the $1,999 foldable (BBG)
Tesla shares opened 1.9% higher after unveiling its second-generation Roadster with SpaceX-developed thrusters, with production expected to begin in 2028 (CNBC)
ExxonMobil flagged a $4.5bn quarter-on-quarter boost to Q3 refining earnings as the Iran war and Ukrainian strikes on Russian refineries lifted margins, full results due 30 October (RT)
Anthropic to commit 5% of its shares to a new public benefit fund, subject to stockholder approval, as it prepares for an IPO expected to be among the biggest ever (BBG)
Iran & Energy
Brent at US$110 a barrel for the first time since May as Middle East and Russia-Ukraine supply risks persisted (BBG)
Iran says it has rebuilt and expanded its air defences, bracing for renewed US strikes as Hormuz and nuclear talks stall (BBG)
China’s underground gas storage was 80% full at the end of September, enough to cover winter demand after early stockpiling on Iran war risks, says Rystad (BBG)
Trump declined to rule out using the “Mother of all Bombs” on Iran after the 3 November midterms (BBG)
Trump waived Russian energy tariffs and sanctions mandated under the Graham law he signed last month, as the measures complicated his push to lower diesel prices before the midterms (BBG)
US lawmakers introduced a bill to block Trump's Russian diesel deal, which pushed oil prices higher intraday (BBG)
Tariffs
No major tariff and/or trade related headlines
Central Banks
BoJ's Ueda says the bank won't tolerate any overshoot of its 2% target and will keep raising rates, ahead of the 29-30 October meeting (RT)
IMF says the BoJ may need to raise rates faster if inflation rises more than expected, backing its normalisation as "doing the right thing" (RT)
ECB's Lagarde says the global bond selloff has tightened financing conditions, which will curb euro area growth and ultimately inflation (CNBC)
ECB's Nagel says "maybe we have to do more", with a December hike to 2.75% widely expected (CNBC)
Economy
US factory output rose 0.3% in September, in line with ests, with semiconductor production up nearly 20% year-on-year (BBG)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Gold Miners | 87.71 | +0.79% |
| Steel | 102.45 | +0.68% |
| Silver Miners | 82.5 | +0.24% |
| Copper Miners | 79.98 | -1.05% |
| Uranium | 35.43 | -1.91% |
| Lithium & Battery Tech | 64.05 | -2.32% |
| Strategic Metals | 54.23 | -2.71% |
Industrials | ||
| Aerospace & Defense | 209.07 | +1.04% |
| Agriculture | 28.23 | -0.18% |
| Construction | 87.62 | -0.86% |
| Global Jets | 25.85 | -2.67% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 201.99 | -2.61% |
Renewables | ||
| Solar | 41.85 | -2.11% |
| Hydrogen | 37.01 | -2.63% |
Technology | ||
| Data Center & Digital Infrastructure | 25.78 | -1.75% |
| Robotics & AI | 33.02 | -2.13% |
| Electric Vehicles | 30.38 | -2.38% |
| FinTech | 24.33 | -2.87% |
| Semiconductor | 493.39 | -4.14% |
| Cloud Computing | 28.07 | -4.91% |
| Cybersecurity | 44.34 | -5.26% |
ASX Today
Advanced Braking Technology posts Q1 FY27 product sales revenue of $5.63m, up 8.3% on the pcp, with normalised gross margin lifting to 50.8% from 49.1%. Cash builds to $7.30m from $5.63m at 30 June, supported by disciplined pricing and higher-value spares (ABV)
Arena REIT upgrades FY27 distribution guidance to 19.0-20.2 cps, 5.6-12.2% above prior guidance of not less than 18.0 cps, on progress resolving the Edge portfolio. The upper end assumes Goodstart’s acquisition of 20 Edge centres proceeds, which remains subject to due diligence (ARF)
Bendigo and Adelaide Bank reports 1Q27 cash earnings of $112.7m, up 18.5% on the 2H26 quarterly average, though statutory NPAT of $66.0m fell 8.6%. NIM down 6 bps to 1.94% on higher liquid assets and deposit mix. Lending balances contracted 3.1% annualised, deposits grew 4.8% (BEN)
Challenger reports Q1 AUM of $31.9bn, up 5%, with total sales up 52% to $4.4bn as fixed term sales doubled to $2.2bn. Net annuity flows of $1.1bn equate to 6.3% book growth. Fidante-Channel Capital merger still expected to complete this half (CGF)
McPherson’s CEO and Managing Director Brett Charlton steps down after more than three years, staying through a six-month notice period as the board appoints a search firm to find a successor (MCP)
Mitchell Services delivers record Q1 FY27 revenue of $66.5m, up 25% on the pcp, with EBITDA up 58% to $18.7m and EBT up 118% to $13.3m. Has signed contracts for a further 10 rigs and sees a path to 80 operating rigs before the end of FY27 (MSV)
What To Watch Today
Where are we now? The Nasdaq is down 5.2% over the past eight sessions, though none of the major benchmarks look too technically alarming. The exception is the Russell 2000, which is down about 11.3% since 14 August and undercut its 200-day moving average three days ago, a telling sign of how small caps are faring. Despite the carnage in tech, seven of the 11 S&P 500 sectors finished higher last week, led by staples up 5.0%, energy up 4.8%, healthcare up 3.4% and materials up 3.0%. Tech was the obvious laggard, down 7.7%, followed by industrials, down 0.8%, and discretionary, down 0.3%. There’s a rotation at play, but what it really looks like is buying Walmart at roughly 35x earnings and single-digit growth or SK Hynix at roughly 3.5x earnings and triple-digit growth. Volatility is also on the rise, with the VIX spiking to just shy of 20, while CNN’s Fear & Greed Index collapsed from 46 a week ago to 18, deep in ‘Extreme Fear’ territory below 20. A contrarian bullish angle is developing, provided the AI trade doesn’t implode
Energy on the rise, everything else not so much. The S&P 500 energy sector rose 2.5% to a fresh all-time high, while utilities and staples also caught a bid. Given the strength in energy prices overnight, the ASX is likely to see a continued pivot into defensives and energy outperformance. Copper faded its entire 1.19% intraday gain to finish flat at US$6.61/lb, and the Copper Miners ETF followed a similar path, up 1.7% in early trade before closing 1.0% lower. Our overnight ETF watchlist was mostly in the red, with steep declines for Nickel Miners (-6.8%), Cloud (-4.9%), Biotech (-3.6%), Rare Earths/Strategic Metals (-2.7%) and Airlines/Jets (-2.6%)
Key Events
Stocks trading ex-dividend:
Mon 19 Oct: FFI Holdings (FFI) – $0.125, Solaris Australian Equity Income Plus (SET) – $0.007, WAM Income Maximiser (WMX) – $0.007, Whitefield Income (WHI) – $0.006
Tue 20 Oct: Clover Corporation (CLV) – $0.013, GQG Partners (GQG) – $0.033, Kingsgate Consolidated (KCN) – $0.10
Wed 21 Oct: None
Thu 22 Oct: N1 Holdings (N1H) – $0.004
Fri 23 Oct: None
Other ASX corporate actions today:
Dividends paid: None
Earnings: None
IPOs: None
AGMs: None
Economic calendar (AEST):
10:05 am: RBA Kent Speech
12:30 pm: China House Price Index
1:00 pm: China GDP Growth Rate, Industrial Production, Retail Sales and Fixed Asset Investment
11:30 pm: Canada Inflation