In a nutshell:
Chipmakers led tech higher for a second session, lifting the Nasdaq and S&P 500 while the Dow stalled ahead of the Fed decision and Big Tech results
Oil eased as Iran diplomacy picked up, while Israel's election delivered no clear winner on early exit polls
The Fed began its two-day meeting with markets expecting a hold on Wednesday and a possible signal toward more hikes
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,723 | +0.60% |
Dow Jones | 52,378 | +0.03% |
NASDAQ Comp | 26,478 | +1.18% |
Russell 2000 | 2,819 | +1.16% |
Global Indices | ||
 S&P/TSX | 36,171 | +0.63% |
 Shanghai Composite | 3,648 | -1.33% |
 DAX | 25,591 | +0.71% |
 Hang Seng | 23,041 | -0.73% |
 Nifty 50 | 73,599 | -0.01% |
 Nikkei 225 | 63,268 | +1.73% |
 FTSE 100 | 10,687 | -0.75% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,060.2 | +1.08% |
 Copper | 6.63 | +1.89% |
 WTI Oil | 100.2 | -1.53% |
Currency | ||
 AUD/USD | 0.7026 | +0.00% |
Cryptocurrency | ||
 Bitcoin (USD) | 80,656 | +0.86% |
 Ethereum (AUD) | 3,334 | +1.56% |
Miscellaneous | ||
US 10 Yr T-bond | 4.993 | +0.14% |
VIX | 17.52 | -4.73% |
US Sectors
Sector | % Chg |
|---|---|
| Information Technology | +1.49% |
| Consumer Discretionary | +1.36% |
| Materials | +0.78% |
| Utilities | +0.71% |
| Industrials | +0.58% |
| Communication Services | +0.15% |
Sector | % Chg |
|---|---|
| Health Care | -0.04% |
| Financials | -0.27% |
| Consumer Staples | -0.90% |
| Real Estate | -0.91% |
| Energy | -2.20% |
S&P 500 Session Chart
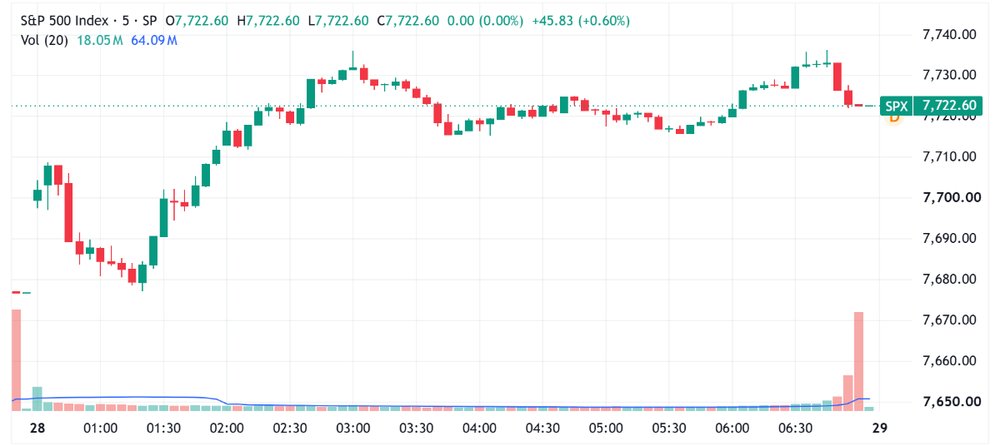
S&P 500 trends higher, closes off best levels (Source: TradingView)
Overnight Markets
Major US benchmarks higher, finished off best levels as chipmakers led a second day of tech gains
Treasury yields edged higher on day one of the Fed meeting, the 2-year up 2 bps to 4.73% and the 10-year up 1 bp to 4.99%
A gauge of chipmakers rallied 3.6% as AI enthusiasm returned ahead of results from tech giants worth more than $10tn (BBG)
Oil slipped in volatile trade as traders weighed moves to de-escalate Persian Gulf tensions and the outcome of Israel's election (BBG)
Consumer staples are tracking their best month in nearly five years as semiconductors crater, with the average S&P 500 stock on track for its sharpest turnaround against the index in decades (YF)
Bond investors doubt a split Congress after the Nov 3 midterms will ease US fiscal worries the way gridlock has for decades (BBG)
Morgan Stanley's Mike Wilson sees a post-election relief rally, saying clearing events like the midterms should pave the way for the S&P 500 to hit a year-end base case of 8,000 (YF)
Stocks
Boeing Q3 adjusted loss of 34c a share was wider than ests of 21c. Cut its full-year delivery target and will fall short of 500 737 Max jets, with the 52-a-month rate pushed to the second half of next year. Shares fell 10.6%, the worst day since April 2025 (BBG)
Coca-Cola Q3 adjusted EPS of $0.91 beat ests by ~3% and revenue of $13.4bn topped ests by ~4%. Unit case volume rose 5%, led by Coke Zero up ~16%. Raised its earnings outlook but flagged slowing North America demand, shares down ~1.5% (YF)
UPS lifted its 2026 revenue forecast to $92.6bn from $91.2bn and raised earnings guidance, with CEO Carol Tomé saying US consumers remain resilient and holiday demand looks strong, shares up ~6% (YF)
Oracle expanded its OpenAI partnership to bring ChatGPT and Codex into its apps and will add Google TPUs and OpenAI's Jalapeño chip to its cloud, shares up nearly 5% (CNBC)
Meta upsized $25bn share sale drew about five times demand, priced at $625, a 2.7% discount, as part of a near $98bn AI funding plan (BBG)
Nvidia to invest $3bn in Meta's equity offering and expand work on the Muse family of models (YF)
Apple unveiled a new iMac and 14-inch MacBook Pro running M6 chips, shares edging higher (YF)
Geopolitics
Israel exit polls show no clear winner, with Netanyahu and challenger Gadi Eisenkot both short of outright victory, Eisenkot's bloc on 52 seats and Arab parties a record 18 (CNN)
Iran's Supreme Leader Mojtaba Khamenei reiterated Tehran's conditions for ending the war with the US amid a regional push to avert fresh fighting in the Gulf (BBG)
UN nuclear watchdog hasn't detected any efforts by Iran to rebuild nuclear facilities damaged in US and Israeli strikes (BBG)
US and Cuban officials clashed at the UN over the embargo as the Trump administration escalates economic pressure on Havana (AP)
Central Banks
Fed expected to hold rates steady on Wednesday, but Chair Kevin Warsh may point the way to more hikes (CNBC)
Fed decision may not be unanimous, with officials split on how quickly to raise rates and analysts expecting a December hike (YF)
Traders price just 10% odds of a Fed hike this week, per CME Group (YF)
Tariffs
German Chancellor Merz urged closer Europe-Asia ties, calling for a coordinated response to violations of free and fair trade and warning of pressure from China (BBG)
Economy
US consumer confidence unexpectedly rose 7.5 points to 91.7 in October, the first gain in four months and highest since June, topping all ests (BBG)
US durable goods orders rose 1.8% in September (CNBC)
China industrial profits rose 14.4% year-on-year in September, up from 4.2% in August and ahead of a 12% forecast, helped by higher energy and AI hardware prices (BBG)
China's AI build-out lifted copper and aluminium producers, with profits up nearly 45% over the first nine months (CNBC)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Strategic Metals | 54.2 | +4.84% |
| Uranium | 35.86 | +4.37% |
| Copper Miners | 76.68 | +3.89% |
| Silver Miners | 76.99 | +3.12% |
| Gold Miners | 83.19 | +2.68% |
| Lithium & Battery Tech | 62.63 | +2.22% |
| Steel | 101.548 | +2.04% |
Industrials | ||
| Global Jets | 27.02 | +2.23% |
| Construction | 87.97 | +2.22% |
| Aerospace & Defense | 206.22 | -0.45% |
| Agriculture | 27.4 | -0.72% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 212.2 | +1.68% |
Renewables | ||
| Hydrogen | 36.92 | +3.45% |
| Solar | 42.02 | +3.09% |
Technology | ||
| Semiconductor | 511.06 | +3.91% |
| Electric Vehicles | 30.41 | +2.36% |
| Cybersecurity | 52.35 | +1.81% |
| Data Center & Digital Infrastructure | 26.13 | +1.75% |
| Robotics & AI | 33.48 | +1.03% |
| FinTech | 24.19 | +0.92% |
| Cloud Computing | 30.38 | -0.85% |
ASX Today
Boss Energy delivers 359klbs drummed at Honeymoon, down 1%, with C1 of $47/lb and AISC of $79/lb tracking to FY27 guidance of 1.25-1.30Mlbs. The New Feasibility Study lands ahead of schedule and confirms the wide-spaced wellfield design supports production to at least FY34 (BOE)
Iluka Resources reports Q3 zircon, rutile and synthetic rutile production of 76kt and sales of 115kt, with realised zircon sand of US$1,685/t in line with guidance. Q4 contracts carry an average US$80/t price rise, lifting the reported Q4 price to US$1,825/t (ILU)
Monadelphous wins about $150m of new resources contracts, including a four-year renewal on Rio Tinto’s Dampier and Cape Lambert marine infrastructure, non-process infrastructure work for BHP’s Ministers North to mid-2028 and a three-year Whitehaven shutdown services extension (MND)
Nova Minerals secures final Alaska state permits for its antimony project, completing permitting within roughly three months and clearing the way for construction and targeted 2027 production. Phase 1 is fully funded by an existing US$43.4m Department of War award, with long-lead equipment already delivered (NVA)
PLS posts record September quarter production of 267.6kt, up 25%, with unit operating costs down 12% to $539/t. An 11% fall in sales and weaker realised pricing cut revenue 24% to $563m. FID taken on the P2000 expansion, targeting ~2.0Mtpa and first ore in the September quarter CY29 (PLS)
PLS signs a 20-year power purchase agreement with Fortescue for a committed minimum 325GWh a year at Pilgangoora from CY29, becoming the first external customer on the Green Grid. Expected to cut unit operating costs by $15-20/t for about $150m of capex phased across FY27-29 (PLS)
West African Resources delivers record quarterly gold production of 128koz at AISC of US$1,570/oz, with $458m of operating cash flow and a $1,195m cash balance. A 20 cent special dividend was paid post-quarter and 2026 guidance of 430-490koz at sub-US$1,900/oz AISC is reaffirmed (WAF)
What To Watch Today
Anthropic in a nutshell. There’s plenty of coverage and commentary on the Anthropic IPO, but here's my two cents. The company is burning far less cash than expected, posting a Q2 operating profit of $974m and an 85% gross margin. The catch is the massive US$600bn of compute contracts that must be paid over the next few years (most of which can’t be cancelled), plus a stack of loans that convert into shares and, of course, the fact that most of its suppliers are also its lenders and shareholders. In short, the IPO marks the AI build-out switching its funding source from credit to public equity.
Nature continues to heal. With the Anthropic S-1 calming market nerves, AI-related sectors are starting to turn after a sharp pullback. On the ASX, that’s pumping life back into materials, which rallied 2.7% on Tuesday. Our overnight ETF watchlist showed broad gains across resources, including Rare Earths/Strategic Metals up 4.8%, Uranium up 4.3%, Copper Miners up 3.8%, Silver Miners up 3.1% and Gold Miners up 2.6%. The flip side could be a pullback in recent pivot beneficiaries like telcos, banks and staples, all of which have run hard over the past month. Something you might notice is that a strong day for BHP often drives weakness for CBA, and vice versa.
Picks and shovels bounce back. The AI revival is also lifting battered contractors and engineering names like SXE, GNG, SKS, SHA, TEA, MGH, GNP and NWH. Before Tuesday’s bounce, most were down 20-30% over the past three weeks. The sector has delivered extraordinary growth, much of it tied to the data centre build-out, but multiples have also expanded to historically elevated levels. As confidence returns to all things AI, so does risk appetite for these pick and shovel plays.
Key Events
Stocks trading ex-dividend:
Wed 28 Oct: None
Thu 29 Oct: Autosports Group (ASG) – $0.03, Benjamin Hornigold (BHD) – $0.062, Waterco (WAT) – $0.13
Fri 30 Oct: None
Other ASX corporate actions today:
Dividends paid: Centuria Industrial REIT (CIP), Centuria Office REIT (COF), Perenti (PRN)
Earnings: None
IPOs: Jacaranda Natural Resources (JRL) at 2:00 pm
AGMs: 4DMedical (4DX), Data#3 (DTL), Dexus (DXS), Fortescue (FMG), Vicinity Centres (VCX)
Economic calendar (AEDT):
11:30 am: Australia Sep CPI
12:45 am: Canada Interest Rate Decision (Ests: 25 bp hike to 2.5%)