In a nutshell:
Wall Street’s rebound lost steam as tech selling resumed, while the Dow held gains and cyclicals led ahead of Tuesday’s US midterm elections
Oil suffered its steepest drop in about three months after Iran’s supreme leader approved talks with Washington and Trump signalled diplomacy would get more time
AI financing stayed front and centre as Oracle filed a US$20bn stock and bond raise and Anthropic disclosed US$895bn in compute commitments in its revised IPO filing
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,541 | -0.51% |
Dow Jones | 51,984 | +0.41% |
NASDAQ Comp | 25,164 | -1.07% |
Russell 2000 | 2,810 | -0.05% |
Global Indices | ||
 S&P/TSX | 35,801 | +0.51% |
 Shanghai Composite | 3,638 | +1.08% |
 DAX | 25,981 | +0.63% |
 Hang Seng | 23,393 | +0.42% |
 Nifty 50 | 75,693 | +1.66% |
 Nikkei 225 | 63,082 | -0.33% |
 FTSE 100 | 10,761 | +0.29% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 3,945.13 | +1.79% |
 Copper | 6.51 | +0.82% |
 WTI Oil | 95.91 | -7.89% |
Currency | ||
 AUD/USD | 0.6996 | -0.51% |
Cryptocurrency | ||
 Bitcoin (USD) | 76,722 | -1.35% |
 Ethereum (AUD) | 3,214 | -0.64% |
Miscellaneous | ||
US 10 Yr T-bond | 4.894 | -0.71% |
VIX | 21.57 | +11.03% |
US Sectors
Sector | % Chg |
|---|---|
| Consumer Discretionary | +2.25% |
| Materials | +1.83% |
| Financials | +1.76% |
| Consumer Staples | +1.75% |
| Industrials | +1.37% |
| Real Estate | +1.01% |
Sector | % Chg |
|---|---|
| Utilities | +0.53% |
| Health Care | -0.17% |
| Communication Services | -0.21% |
| Information Technology | -2.66% |
| Energy | -3.97% |
S&P 500 Session Chart
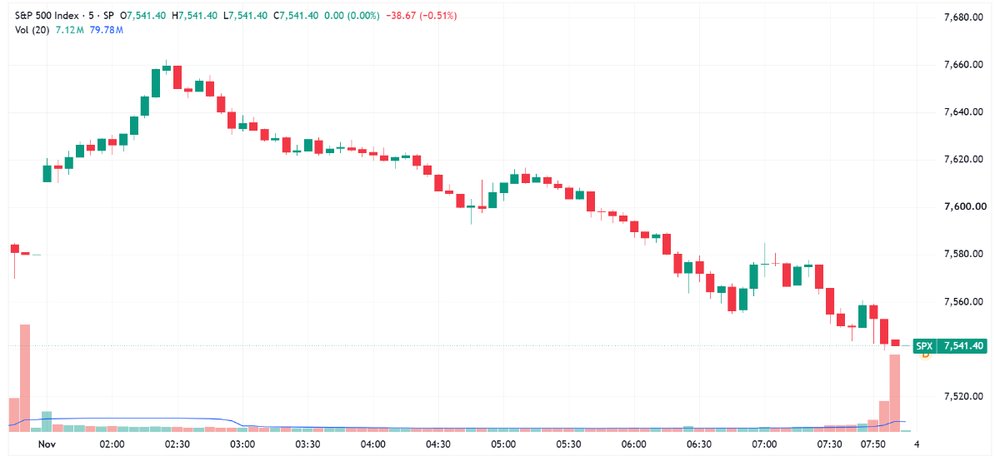
S&P 500 gave up early gains to finish at worst levels (Source: TradingView)
Overnight Markets
Major US benchmarks mixed but finished near session lows, the Dow higher while the S&P 500 and Nasdaq gave back early gains of as much as 1.1% and 1.4% respectively
Oil and natural gas slumped the most in roughly three months,with Brent down ~8% to US$103 a barrel, after Iran’s supreme leader approved government pursuit of talks with the US
Yields eased across the board, with the 10-year down 2 bps to 4.91% (now down ~45 bps since the 7-Oct high) as cheaper oil eased inflation anxiety
Consumer discretionary and materials led the S&P 500, while tech and energy lagged as investors kept rotating out of AI-linked names, with Amazon and Walmart both up 2-3%
Anthropic’s revised IPO filing showed third-quarter revenue of about $17bn, up 1,127% year-on-year, alongside $895.4bn in purchase and lease commitments, mostly for compute (CNBC)
Deutsche Bank upgraded US tech to overweight, saying past rotations into the sector delivered average gains of 32% and outperformed the rest of the S&P 500 by 30 percentage points (CNBC)
Morgan Stanley strategists said the US correction that began in June is in its final innings, with Tuesday’s midterms set to remove a major market overhang (RT)
Morgan Stanley’s Mike Wilson said any post-midterm selloff is likely to be short-lived, even as polls point to a shift in the balance of power in Congress (BBG)
Stocks
Apple reports fiscal Q4 after the bell, its first result under CEO John Ternus, with ests at $113.4bn revenue and EPS of $1.99, and shares down ~2% into the print (CNBC)
Palantir reports Q3 after the bell, with options pricing an 11.5% implied move versus a 10% average over the past two years (CNBC)
Oracle filed to raise $20bn through $10bn of new common stock and $10bn of senior notes to fund its AI build-out, shares down about 6% at midday (CNBC)
Marvell agreed to buy laser maker Lumentum in a $115bn all-stock deal, a bet on optical AI data centre connectivity, though both stocks sold off sharply on the news (CNBC)
SpaceX shares rose more than 3% after The Washington Post reported the company is in talks to buy Dish Network’s Boost Mobile unit or use its network (CNBC)
Micron, SanDisk and Western Digital extended Friday’s slump as memory chip stocks remained at the centre of the AI selloff (CNBC)
Geopolitics
Iran’s supreme leader approved government pursuit of negotiations with the US, state-run IRNA reported, as Washington and Tehran signalled openness to talks (BBG)
Trump told Netanyahu he wants to let Iran negotiations play out before potentially resuming strikes, Axios reported (BBG)
Gulf states fear a fresh US-Israeli assault on Iran would prompt an even more destructive war across the region (BBG)
Secretary of State Marco Rubio said Trump prefers not to use military force against Iran and would like to resolve the eight-month conflict diplomatically (CNBC)
Iran’s Foreign Minister Abbas Araghchi said mediators are discussing the proposal Tehran put forward at the UN General Assembly in September (CNBC)
Americans vote in Tuesday’s midterm elections, with polls pointing to a shift in the balance of power in Congress (BBG)
US voters head to the polls in a sour economic mood, with high and rising prices a key issue and many blaming tariffs and the Iran war for inflation (RT)
Tariffs & Trade
The US plans to suspend South Africa and Rwanda from duty-free access under AGOA, with South Africa’s AGOA exports mainly autos, parts, citrus and wine (RT)
A group representing nearly all major automakers urged Congress to pass a permanent ban on Chinese vehicles in its post-midterm session, as the US keeps tariffs above 100% on Chinese EVs (RT)
Central Banks
No major overnight headlines
Economy
US ISM manufacturing PMI rose to 55.5 in October from 54.5, ahead of 54.6 ests, with production at 59.0, its highest since November 2021 (RT)
ISM prices paid eased to 75.2 from 77.9 but stayed elevated, with manufacturers still paying more for aluminium, copper, diesel and memory components
ISM factory employment kept expanding in October, though the index eased to 52.4 from 52.7 ahead of Friday’s payrolls report
China’s RatingDog manufacturing PMI eased to 52.0 in October from 52.1, in line with ests, as output growth hit a six-month high but export order growth slowed to a three-month low
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Gold Miners | 79.16 | +2.69% |
| Silver Miners | 72.41 | +1.63% |
| Steel | 100.695 | +1.31% |
| Copper Miners | 72.83 | +1.21% |
| Strategic Metals | 50.27 | +0.56% |
| Lithium & Battery Tech | 60.08 | +0.45% |
| Uranium | 32.93 | -2.37% |
Industrials | ||
| Global Jets | 28.06 | +4.20% |
| Construction | 91.8479 | +2.43% |
| Aerospace & Defense | 214.7 | +2.36% |
| Agriculture | 26.8 | -0.33% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 213.79 | -1.76% |
Renewables | ||
| Solar | 42.09 | +4.70% |
| Hydrogen | 34.52 | -0.92% |
Technology | ||
| FinTech | 24.0672 | +0.66% |
| Robotics & AI | 32.27 | +0.16% |
| Electric Vehicles | 28.8549 | -0.60% |
| Cloud Computing | 27.35 | -2.39% |
| Data Center & Digital Infrastructure | 24.93 | -2.50% |
| Semiconductor | 453.65 | -3.79% |
| Cybersecurity | 46.47 | -5.87% |
ASX Today
It’s crickets out there! Literally just a handful of drilling results
What To Watch Today
The rotation continues (and miners try to catch a bid). The equal-weight S&P 500 has staged a V-shaped recovery, up 5.7% since 30-Sep and now within 1.2% of all-time highs. Overnight, most sectors outside Energy and Tech caught a decent bid as bond yields continued to roll over, largely thanks to a sharp pullback in oil prices. Discretionary led the way, rallying 2.1% as markets hone in on the idea that the rate hike cycle is nearing its end. We’ve seen a similar dynamic locally, where the S&P/ASX 200 Discretionary sector corrected ~16% between 6-Aug and 23-Sep before bouncing ~8%. Resources are also trying to turn, buoyed by easing yields and a softer US dollar. But the price action across our ETF watchlist was far from bullish. The Copper Miners ETF closed up 1.1% after being up as much as 3.5%, and the Rare Earths/Strategic Metals ETF finished 0.6% higher after fading early gains of 4.0%. Miners have sold off hard since late August and have so far struggled to make the turn. Software didn’t benefit from the AI trade stumbling either, with the iShares Expanded Tech-Software ETF down 2.2% and now 8.9% lower over a three-day skid. So really, it’s the consumer-facing sectors that are winning this rotation out of AI.
The Melbourne cup. Macquarie's quants tip Point of Law for the Melbourne Cup, with the former King Charles-owned three-year-old topping both models. So You Are and Juja Kibo place on the traditional model, while an enhanced version layering on market narrative signals has Shockletz and Hopewell Rock second and third
Key Events
Stocks trading ex-dividend:
Tue 3 Nov: WAM Global (WGB) – $0.066
Wed 4 Nov: None
Thu 5 Nov: Future Generation Global (FGG) – $0.042
Fri 6 Nov: New Murchison Gold (NMG) – $0.003
Mon 9 Nov: Clime Capital (CAM) – $0.005, Future Generation Australia (FGX) – $0.038, NAOS Ex-50 Opportunities Company (NAC) – $0.016, NAOS Small Cap Opportunities Company (NSC) – $0.01
Other ASX corporate actions today:
Dividends paid: None
Earnings: None
IPOs: None
AGMs: None
Economic calendar (AEDT):
2:30 pm: RBA Interest Rate Decision (Ests: 25 bp hike to 4.85%)
2:00 am: US JOLTs Job Openings