In a nutshell:
Major US benchmarks finished lower, but off worst levels as big banks opened third-quarter earnings season with mixed results and Johnson & Johnson weighed on healthcare
Memory chip selloff hit Seoul hardest on fears China’s CXMT is closing the DRAM gap, while US chipmakers posted a milder fifth straight decline
Houthi attacks on Saudi Arabia escalated, with a Reuters source saying Aramco’s headquarters was struck, as Trump accused Iran of steering the attacks to lift oil before the midterms
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,805 | -0.02% |
Dow Jones | 51,670 | -0.35% |
NASDAQ Comp | 27,204 | -0.15% |
Russell 2000 | 2,783 | -0.40% |
Global Indices | ||
 S&P/TSX | 35,984 | +0.90% |
 Shanghai Composite | 3,801 | +0.10% |
 DAX | 25,260 | -0.07% |
 Hang Seng | 24,345 | +0.30% |
 Nifty 50 | 73,034 | +1.54% |
 Nikkei 225 | 67,778 | -1.82% |
 FTSE 100 | 10,650 | -0.06% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,160.77 | -0.27% |
 Copper | 6.68 | -0.30% |
 WTI Oil | 94.79 | +1.12% |
Currency | ||
 AUD/USD | 0.6984 | +0.35% |
Cryptocurrency | ||
 Bitcoin (USD) | 83,338 | +1.05% |
 Ethereum (AUD) | 3,593 | -0.08% |
Miscellaneous | ||
US 10 Yr T-bond | 5.217 | -0.44% |
VIX | 15.27 | +0.39% |
US Sectors
Sector | % Chg |
|---|---|
| Energy | +1.74% |
| Communication Services | +0.88% |
| Utilities | +0.57% |
| Materials | +0.37% |
| Information Technology | +0.08% |
| Consumer Discretionary | -0.08% |
Sector | % Chg |
|---|---|
| Real Estate | -0.28% |
| Industrials | -0.29% |
| Consumer Staples | -0.33% |
| Financials | -0.41% |
| Health Care | -1.33% |
S&P 500 Session Chart
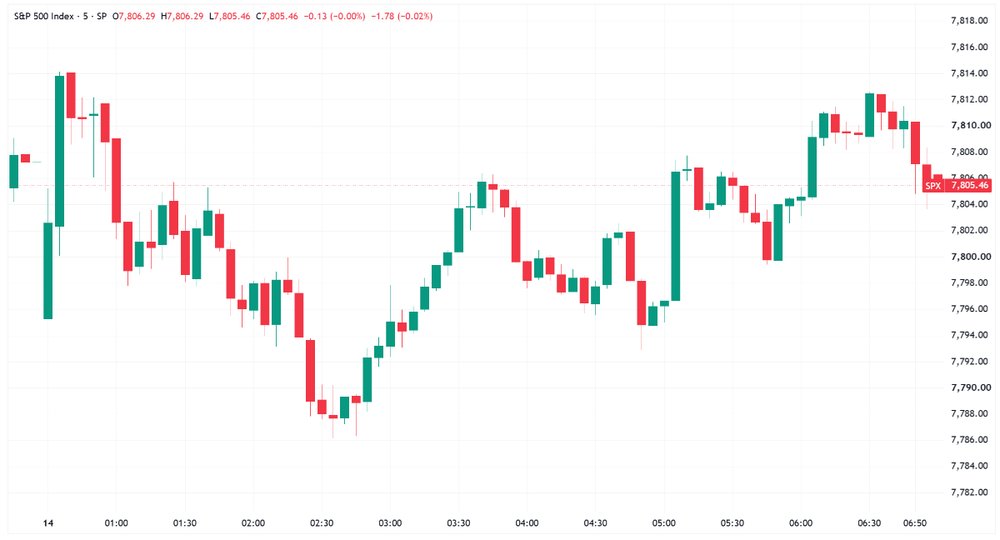
S&P 500 regained early loses to finish flat (Source: TradingView)
Overnight Markets
Major US benchmarks lower, but off worst levels with the S&P 500 fluctuating through the session as Wall Street banks kicked off earnings season
US 10-year yield eased 2bps to around 5.22% and the 30-year slipped 3 basis points to 5.56% ahead of Wednesday’s September CPI report
The Philadelphia Semiconductor Index (SOX) fell as much as 3% before recovering to close 0.2% lower, taking its five-session drop past 8%, after Broadcom CEO Hock Tan compared some of the money flowing into the sector to casino gambling
South Korea’s Kospi closed down 5.5% on AI overheating and Chinese competition fears, with Samsung Electronics and SK Hynix down about 7% and 10%, while Taiwan’s Taiex and the Nikkei 225 lost nearly 2% (BBG)
Brent edged higher to US$106.3 a barrel, an 11% rise since 29 September, and WTI near US$94 a barrel as hopes for more Russian diesel offset Saudi-Houthi supply fears, with Goldman estimating the extra diesel would cut wholesale prices by just $1 to $2 a barrel (CNBC)
S&P 500 earnings for the July to September quarter are expected to grow 30.6% year-on-year, led by technology and energy companies, according to LSEG data (RT)
Healthy earnings beats are now the status quo, with index EPS highly dependent on AI capex durability and monetisation, says BofA's Subramanian (YF)
Fund managers won't rotate from stocks to bonds until the 10-year yield hits 5.9%, BofA's October survey shows (YF)
Stocks
JPMorgan Q3: net income up 6% to $15.3bn, revenue up 8% to $50.2bn, EPS $5.57 missed ests by ~6%, a rare shortfall, and included $658m of bond-rout securities losses. Jamie Dimon warned large deficits, sticky inflation and rising rates pose risks beneath the economy’s strength (YF)
Goldman Sachs Q3: revenue up 23% to $18.68bn, equities revenue up 72% to $6.44bn, FICC down 1% to $3.47bn, EPS $17.01 beat ests by ~31% despite a ~$1 charitable contribution hit (RT)
Citigroup Q3: profit up 40% to $5.25bn, revenue up 8% to $23.8bn, its best third quarter in a decade, EPS $2.85 beat ests by ~7%, though card profit fell 8%. Jane Fraser expects to exceed this year’s return target (RT)
Wells Fargo Q3: EPS $1.87 beat forecasts but net interest income of $12.52bn missed ests by ~1%, credit loss provisions of $1.03bn came in below ests and full-year NII guidance was held, shares down almost 3% (CNBC)
Johnson & Johnson Q3: profit slightly topped ests on strong Tremfya sales and it targets a mid-2027 spinoff of the DePuy Synthes hips and knees unit. The CFO said the Mideast conflict and Europe austerity hurt international sales, shares down about 6% (RT) marketscreeneraol
Apple unveiled the HomeView smart home hub, a new Apple TV 4K and HomePod mini, all showcasing its AI-upgraded Siri, as shares climbed to a record high (CNBC)
Nvidia CEO Jensen Huang flagged $2bn of European investment announcements in the next week, adding to $8bn deployed on the continent over the past year, with new stakes in French startups including Doctolib (BBG)
Iran & Energy
Loud booms were heard near Saudi Aramco’s Dhahran headquarters, with a source telling Reuters the building was struck, directly or by falling debris, an evacuation order issued and staff told to work from home Wednesday (RT)
Netanyahu and Trump discussed a possible major joint operation against Iranian military and nuclear targets before the Israeli and US elections, Axios reported, though a White House official called the report false (Axios)
Trump said on Truth Social the Houthis were probably attacking Saudi Arabia at Iran’s behest to drive up oil prices before the November midterms, warning he would never forget the attacks (YF)
Saudi Arabia intercepted three drones north of Riyadh and two ballistic missiles fired toward Khamis Mushait, while the coalition warned civilians to leave an oil site in Houthi-held Sanaa (BBG)
Trump said he might ask Turkish President Erdogan to intervene on Saudi Arabia’s behalf against the Houthis, adding he believed Erdogan would do as asked (RT)
Central Banks
New York Fed President John Williams said one more hike may be appropriate this year but sees no current reason to raise rates again in 2027, expecting inflation to slow towards 2% next year (BBG)
Fed Governor Waller said surging long-term Treasury yields are curbing demand in housing and autos and doing some of the Fed’s work, as swaps across eight major economies shed almost 200bps of hikes since mid-September (BBG)
Bank of Japan officials are leaning against a rare back-to-back hike at the October 30 meeting but still see a possible move in December, Bloomberg reported, citing people familiar with the matter (BBG)
Economy
The IMF lifted its 2026 global growth forecast to 3.1% from 3.0% in July as AI investment cushioned the war-driven energy shock, and now assumes the Strait of Hormuz reopens in March 2027 (CNBC)
The IMF sees global headline inflation rising to 4.7% this year from 4.1% in 2025 and China’s growth slowing to 4.5%, with just 32 economies accounting for 95% of global growth (YF)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Steel | 103.03 | -0.07% |
| Uranium | 37.38 | -0.90% |
| Lithium & Battery Tech | 67.65 | -1.05% |
| Copper Miners | 84.4 | -1.11% |
| Strategic Metals | 57.45 | -1.25% |
| Gold Miners | 87.24 | -1.46% |
| Silver Miners | 84.11 | -2.27% |
Industrials | ||
| Agriculture | 28.43 | -0.04% |
| Construction | 89.61 | -0.11% |
| Global Jets | 26.8 | -0.81% |
| Aerospace & Defense | 204.0 | -0.99% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 200.02 | -2.08% |
Renewables | ||
| Solar | 44.38 | +2.07% |
| Hydrogen | 40.8711 | +0.92% |
Technology | ||
| Robotics & AI | 34.96 | +0.17% |
| Cloud Computing | 29.75 | -0.03% |
| Electric Vehicles | 32.0596 | -0.06% |
| FinTech | 24.918 | -0.09% |
| Semiconductor | 543.9 | -0.17% |
| Cybersecurity | 48.57 | -0.25% |
| Data Center & Digital Infrastructure | 27.33 | -1.44% |
ASX Today
Mercury NZ lifts Q1 FY27 trading margin 19% to NZ$445m despite Waikato hydro inflows at the second percentile, with 307GWh of new wind and geothermal output largely offsetting a 24% fall in hydro generation. The NZ$486m Kaiwera Downs Stage 2 wind farm has reached full generation, adding 155MW of capacity. On track for FY27 EBITDAF guidance (MCY)
Fletcher Building says Q1 FY27 sales volumes rose on the prior corresponding period in most business units, led by Dimond, ColorCote and PlaceMakers frame and truss sales, up 16% to 18%. Residential & Development remains challenging, with minimal contribution expected towards half-year earnings (FBU)
What To Watch Today
Kerry here! Here’s my two cents on today’s session, with miners still under pressure, energy stocks enjoying their time in the spotlight, and the big question of where those battered engineering stocks go from here.
Not a whole lot: A soft, uneventful US lead. Our overnight ETF watchlist points to more choppy trade for Materials, with gold, rare earths/strategic metals, copper and uranium ETFs all down 1-1.5%, alongside softness in tech and strength in energy. Commodities were broadly lower, with gold down 0.2% to US$4,160/oz, copper down 0.5% to US$6.78/lb and aluminium down 0.4% to US$3,019 a tonne.
Engineering and AI stocks: Names like SKS (-20.5%), Southern Cross Electrical (-8.8%), Maas (-6.6%) and NWH (-4.7%) traded in a relatively orderly fashion until about 3 pm AEDT on Tuesday, then sold off aggressively in the last hour. Southern Cross was up around 1% before nosediving into the close. Other tech and AI-related names followed, including Megaport (-9.9%), Codan (-6.0%) and Dicker Data (-4.9%). Around the same time, AirTrunk said it would delay its Singapore REIT listing to early 2026, citing market volatility and rising bond yields. The selloff looks like one or more funds long the whole AI trade heading for the exit at any cost. It’ll be interesting to see whether this is just a sentiment wobble and these stocks can rebuild their bases, or the start of a de-rating process.
Key Events
Stocks trading ex-dividend:
Wed 14 Oct: United Overseas Australia (UOS) – $0.02
Thu 15 Oct: Acorn Capital Investment Fund (ACQ) – $0.035, Australian Foundation Investment Company (AFI) – $0.092, Cobram Estate Olives (CBO) – $0.045, Fat Prophets Global Contrarian Fund (FPC) – $0.03, Horizon Oil (HZN) – $0.01, K&S Corporation (KSC) – $0.06, Rivco Australia (RIV) – $0.018, WAM Research (WAX) – $0.05
Fri 16 Oct: Gowing Bros (GOW) – $0.03, WAM Microcap (WMI) – $0.053
Mon 19 Oct: FFI Holdings (FFI) – $0.125, Solaris Australian Equity Income Plus (SET) – $0.007, WAM Income Maximiser (WMX) – $0.007
Tue 20 Oct: Clover Corporation (CLV) – $0.013, Kingsgate Consolidated (KCN) – $0.1
Other ASX corporate actions today:
Dividends paid: Cochlear (COH), Duratec (DUR), Qantas Airways (QAN), Shine Justice (SHJ)
IPOs: Glencore (GLC) – 11:00 am
AGMs: Commonwealth Bank of Australia (CBA) – 9:30 am, Origin Energy (ORG) – 10:00 am, The Lottery Corporation (TLC) – 10:00 am, Orora (ORA) – 10:30 am, Praemium (PPS) – 10:30 am
Economic calendar (AEDT):
10:30 am: RBA Meeting Minutes
10:30 am: NAB Business Confidence