In a nutshell:
Wall Street struggled as rising oil prices broadened the selloff beyond the AI trade, with the Dow bearing the brunt and the S&P 500 and Nasdaq notching a second weekly loss
Brent crude hit a six-month high near US$117 a barrel as Houthi attacks on Saudi Arabia and Trump's preparations for post-election Iran strikes stoked supply fears
A central bank super week looms, with the Fed, ECB and Bank of Japan all deciding as traders all but rule out an October Fed hike and eye December instead
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,624 | -0.52% |
Dow Jones | 52,215 | -1.23% |
NASDAQ Comp | 25,955 | -0.21% |
Russell 2000 | 2,776 | -0.29% |
Global Indices | ||
 S&P/TSX | 35,788 | -0.51% |
 Shanghai Composite | 3,690 | +0.89% |
 DAX | 25,182 | -0.75% |
 Hang Seng | 23,093 | +0.69% |
 Nifty 50 | 73,124 | -0.17% |
 Nikkei 225 | 62,693 | -0.34% |
 FTSE 100 | 10,690 | -0.32% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 3,993.96 | -0.77% |
 Copper | 6.48 | +1.78% |
 WTI Oil | 103.27 | +3.82% |
Currency | ||
 AUD/USD | 0.7034 | -0.01% |
Cryptocurrency | ||
 Bitcoin (USD) | 80,391 | +0.10% |
 Ethereum (AUD) | 3,331 | +0.14% |
Miscellaneous | ||
US 10 Yr T-bond | 4.988 | +0.71% |
VIX | 19.45 | +2.21% |
US Sectors
Sector | % Chg |
|---|---|
| Energy | +2.51% |
| Information Technology | +0.35% |
| Real Estate | +0.23% |
| Utilities | -0.66% |
| Materials | -0.99% |
| Health Care | -1.12% |
Sector | % Chg |
|---|---|
| Industrials | -1.29% |
| Financials | -1.33% |
| Communication Services | -1.39% |
| Consumer Discretionary | -1.39% |
| Consumer Staples | -1.83% |
S&P 500 Session Chart
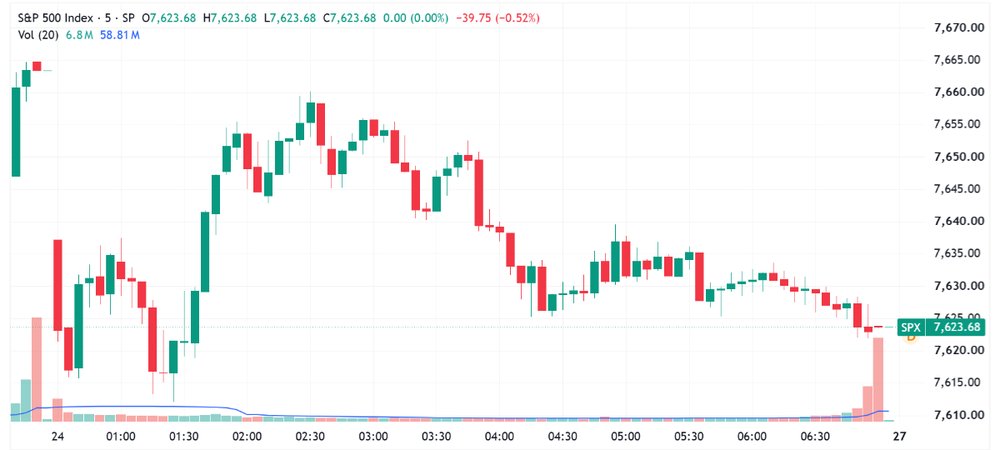
S&P 500 tries to bounce back to breakeven but slumps into the close (Source: TradingView)
Overnight Markets
Major US benchmarks lower, the Nasdaq gave up a modest early gain while the Dow extended losses into the close
S&P 500 and Nasdaq starting to roll over, closing at a respective five-week low and near-three month low
US weekly recap: S&P 500 (-0.47%), Nasdaq (-0.71%), Dow (+0.41%) and Russell 2000 (+2.0%)
Brent crude settled near US$117 a barrel, its highest since April and a third straight weekly gain, as Houthi attacks on Saudi Arabia added to supply risks from the US-Iran war (BBG)
US 10-year yield rose 4 bps to 5.0%, with Treasuries giving back part of Thursday's rally as higher oil revived inflation concerns days before the Fed decision (BBG)
Energy led sector gains as WTI crude topped US$100 a barrel, with oilfield services giants SLB up more than 7% and Halliburton up 6% (CNBC)
Cybersecurity stocks rallied after an Evercore ISI survey flagged strengthening security budgets, with Palo Alto Networks and Cloudflare each up more than 7% (YF)
Telecoms slid as AT&T and T-Mobile fell more than 5% each on a report that SpaceX is in private talks to lease 80,000 US cell towers (CNBC)
A gauge of chipmakers edged higher but still posted its longest weekly drop since November as AI financing jitters lingered (BBG)
France avoided a Moody's downgrade, with the agency holding the euro zone's second-biggest economy at Aa3 with a negative outlook after a week of bond market turmoil (BBG)
Emerging market bond funds drew a 12th straight week of inflows, with JPMorgan Asset Management and Generali loading up despite most US yields topping 5% (BBG)
Bank of America's Michael Hartnett stays tactically risk-off until mid-November, expecting lower yields, stocks and US dollar amid AI and midterm jitters (BBG)
Goldman Sachs cut its Kospi 12-month target by 25% to 9,000, citing more conservative valuations after the index plunged more than 35% from its June peak (BBG)
Stocks
American Express Q3 revenue up 9% to $14.5bn, about 2% below ests, adjusted EPS up 13% to $4.68. Cutting roughly 5% of its global workforce, or 3,500 roles, with a $336m restructuring charge. Shares down about 3% (YF)
Apple briefly overtook Nvidia as the world's most valuable company as its $1,999 iPhone Duo hit stores, with both worth about $5.1tn before Nvidia reclaimed the lead (YF)
SK Hynix shelved plans for a US listing of flash memory unit Solidigm, which had aimed to raise $10bn to $15bn at a valuation of up to $150bn, citing market conditions (YF)
SpaceX is not considering raising equity and has debt funding pools available, JPMorgan says after meeting management, setting it apart from Meta's nonvoting share plan (YF)
Trafigura made a record profit of around $2bn in metals trading as the sector enjoys a second blowout year, while Glencore took a $480m provision tied to iron ore trader Radiant World (BBG)
Iran & Energy
Trump is preparing for Iran escalation after the US and Israeli elections, having sent a third aircraft carrier strike group and 10,000 more sailors and Marines toward the Persian Gulf (BBG)
Trump floated letting Iran wither rather than finishing it off, touting evidence that Middle East oil exports have surpassed pre-war levels (YF)
Saudi Arabia intercepted Houthi drones and a ballistic missile headed for Riyadh on Sunday, after the group claimed attacks on airports and Aramco facilities in Yanbu (CNBC)
US Secretary of State Rubio plans trilateral negotiations over Ukraine, House Speaker Mike Johnson said after weekend talks with Trump and Rubio (BBG)
Tariffs & Trade
Trump defended tariffs at a Georgia rally, saying they have made the US richer as he announced Volkswagen will build a $4.2bn Audi plant producing 200,000 cars a year (BBG)
Trump says his administration has many more economic announcements to come following the Audi plant news, nine days out from the US midterms (BBG)
Central Banks
Traders pared bets on an October Fed hike to about 5%, down from 15% earlier in the week and 37% at the end of September, according to Bloomberg data (YF)
CME FedWatch prices about a 71% chance of a December Fed hike, with no change expected at Wednesday's meeting from the current 3.75% to 4.00% range (CNBC)
PIMCO's Tiffany Wilding says the Fed has room for a measured approach, noting inflation is elevated but not accelerating even as AI boosts US demand (BBG)
Economy
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Steel | 100.04 | +0.08% |
| Uranium | 34.11 | +0.06% |
| Lithium & Battery Tech | 60.68 | 0.00% |
| Copper Miners | 73.09 | -0.05% |
| Strategic Metals | 51.46 | -0.27% |
| Gold Miners | 80.2 | -1.82% |
| Silver Miners | 74.06 | -2.54% |
Industrials | ||
| Agriculture | 27.87 | -0.18% |
| Aerospace & Defense | 202.23 | -1.10% |
| Construction | 85.44 | -1.33% |
| Global Jets | 26.1 | -2.50% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 207.74 | -0.86% |
Renewables | ||
| Solar | 41.07 | -0.68% |
| Hydrogen | 35.4 | -2.72% |
Technology | ||
| Cybersecurity | 49.93 | +4.98% |
| Cloud Computing | 30.31 | +2.19% |
| Data Center & Digital Infrastructure | 25.43 | +1.92% |
| Robotics & AI | 33.02 | +1.04% |
| Semiconductor | 478.2 | +0.53% |
| Electric Vehicles | 29.36 | -0.54% |
| FinTech | 24.4507 | -1.96% |
ASX Today
Beforepay delivers record Q1 FY27 revenue of $16.5m, up 45%, and cash NPAT of $5.7m, up 58%. Total advances hit a record $265m on a 17% lift in average advance size to $524. Personal Loans net bad debt of 1.59% is expected to normalise (B4P)
BlueScope upgrades 1H FY27 underlying EBIT guidance to approaching $1.1bn from $860-960m, driven by North Star on US mini-mill spreads now seen at ~US$810/t versus US$750/t assumed. North America earnings expected around two-thirds above 2H FY26 (BSL)
Brazilian Rare Earths lifts the Monte Alto indicated resource 41% to 3.5Mt at 10.7% TREO, with Monte Alto South up ~200% to 1.9Mt. Indicated material now accounts for 87% of contained TREO, underpinning a fast-tracked, low-capex concentrate export development ahead of Camaçari (BRE)
Greatland Resources produces 70,131oz gold and 2,927t copper in the September quarter at AISC of $2,925/oz, holding FY27 guidance of 260-300koz at $2,900-3,330/oz. Operating cash flow of $289m lifts closing cash to $1.31bn, debt free, with Havieron development now commenced (GGP)
Metallium signs a non-binding MOU with physical commodity trader Traxys to evaluate US critical metals processing, pairing its Texas development with Traxys’ sourcing, offtake, hedging and prepayment capability. No binding offtake, financing or investment commitments agreed (MTM)
NEXTDC responds to investor anger over the M3 Melbourne power delay and FY27 downgrade. Chairman Douglas Flynn will retire once a successor is in place, NED fees are cut 10%, the fee increase resolution is withdrawn and CEO Craig Scroggie forgoes his FY27 STI and LTI (NXT)
PlaySide Studios has signed External Projects contracts worth an aggregate $6.2m so far in FY27, of which ~$5.0m is expected to be recognised as FY27 revenue. Work includes a new Dumb Ways title for a sandbox platform plus AI-enabled prototypes for a large technology company’s upcoming hardware (PLY)
Ramelius Resources produces 48,839oz at AISC of $2,656/oz in the September quarter, with weather disruption to Penny haulage stranding 4,202oz of contained gold in stockpiles until next quarter. Reaffirms FY27 guidance of 205-225koz at $2,150-2,350/oz. Cash and gold of $768m (RMS)
What To Watch Today
Defensives take a breather. High-flying defensive sectors like staples (-1.8%) took a breather on Wall Street overnight, likely weighed by the surging oil price and profit taking. Or perhaps it’s the market saying no thanks to paying ~40-50x for names like Costco and Walmart. Discretionary, financials, industrials and healthcare also fell more than 1%. The ASX has taken a very defensive posture in recent weeks, with utilities (+11.0%), healthcare (+8.2%), staples (+7.4%) and financials (+7.1%) all sharply higher over the past month. These sectors usually move pretty slowly, so a breather wouldn’t be surprising.
CBA vs. BHP. CBA somehow rallied 4.3% last Friday, Westpac and NAB both added around 3.1% and ANZ rose 0.8% to close within 2% of all-time highs. There’s honestly no other explanation for this aggressive bid than a major rotation out of miners. The S&P/ASX 200 materials sector tumbled 3.8%, including a 3.6% drop for BHP. Miners are badly oversold, so perhaps we see some stabilisation here, but it’s certainly a trend to watch.
Energy gains, software holds. Our overnight ETF watchlist was mostly lower last Friday. The few pockets of strength included the Global X Cloud Computing ETF (+2.1%), which closed at its highest since Nov-21, and the broader iShares Expanded Tech Software ETF (+1.7%), which continues to look like it wants to break out. The S&P 500 Energy Sector (+2.6%) also closed at all-time highs. Meanwhile, there’s a real reluctance towards resources. Copper bounced 1.6% to US$6.56/lb, yet the Global X Copper Miners ETF finished flat.
Key Events
Stocks trading ex-dividend:
Mon 26 Oct: Alcoa (AAI) – $0.101
Tue 27 Oct: Bank of Queensland (BOQ) – $0.20
Wed 28 Oct: None
Thu 29 Oct: Autosports Group (ASG) – $0.03, Benjamin Hornigold (BHD) – $0.062, Waterco (WAT) – $0.13
Fri 30 Oct: None
Other ASX corporate actions today:
Economic calendar (AEDT):
No major economic announcements.