ASX 200 Live Today - Thursday, 6th August
The S&P/ASX 200 is set to close at a second straight all-time high. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Thursday, August 6. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Reporting season is heating up and we've got you covered. Our reporting season calendar has over 250 stocks plus earnings and dividend estimates.
ASX 200 set for a second straight all-time high
[2:15 pm] Record highs tend to come in clusters, and the ASX 200 is set to close at a second straight all-time high. The index is currently up 0.42%, but down from session highs of 0.75%. Heavyweight Materials (+1.1%) and Financials (+0.3%) have both halved from session highs of 2.2% and 0.6% respectively. Though both have moved in a rather vertical fashion in recent days/weeks, with Materials up 7.5% in the last five sessions, while Financials have gained 10% since the start of July.
That's all for today. The ASX 200 is looking rather extended after a strong run into record territory. However, oil and bond yields continue to ease, copper prices are sitting at record highs, gold is bouncing and corporate earnings are looking so far so good.
IML backs REA as 'possibly the highest-quality business on the ASX
[2:10 pm] IML Portfolio Manager Lucas Goode, who has covered REA for around 15 years, makes the bull case following FY26 results and pushes back on fears a weaker housing market derails the stock.
On the Bell Potter bear case and its call for a possible 10% FY27 listings fall, Goode argues housing-market concerns are historically when you want to buy REA, noting listings dropped only around 11% even during the Royal Commission and always recover
On pricing power, he says REA is nowhere near its limits, with buyer enquiries up around 10% while Buy yield rose 13%, meaning price per lead climbed just 3%, and rates the stock a Buy
Read the full interview on Livewire for Goode's take on the Bell Potter bear case, AI disruption risk, capital allocation and why he remains bullish.
Results so far: Pinnacle and Credit Corp
[1:41 pm] Of the handful of companies to report so far, share price reactions have been broadly positive, even where the numbers were mixed.
Pinnacle (5-Aug): The stock was already up 17.2% in the three days before the result, then rallied 8.3% on the day and a further 2.9% today. FY26 net profit rose 21% to $138m, about 7% below consensus, but key metrics like funds under management came in ahead.
Credit Corp (4-Aug): FY26 landed broadly in line with expectations and FY27 guidance implied further year-on-year profit growth, but both were overshadowed by a miss on debt purchasing guidance of $200-280m against Macquarie's $305m, around a 21% shortfall. So decent headline numbers offset by a softer guidance item. Credit Corp briefly gained 4.8% on the day before finishing down 6.9%, then recovered 4.5% the next day.
Top All Ords gainers and losers
[1:25 pm] Two Brazil-based rare earth explorers, Viridis and Brazilian Rare Earths, traded sharply higher, while US-based Dateline and Malawi-based Lindian went the other way.
Ticker | Company | % Chg | Price |
|---|---|---|---|
VMM | Viridis Mining And Minerals | 13.93% | $4.17 |
FML | Focus Minerals | 13.51% | $2.10 |
MI6 | Minerals 260 | 11.36% | $0.74 |
AGI | Ainsworth Game Technology | 10.87% | $1.28 |
PNR | Pantoro Gold | 10.41% | $2.44 |
RXL | Rox Resources | 10.12% | $0.46 |
BTR | Brightstar Resources | 9.37% | $0.43 |
G6M | Group 6 Metals | 9.09% | $3.00 |
AUC | Ausgold | 8.85% | $0.95 |
BRE | Brazilian Rare Earths | 8.46% | $4.30 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
DTR | Dateline Resources | -10.71% | $0.13 |
LIN | Lindian Resources | -10.06% | $0.70 |
BGP | Briscoe Group | -6.84% | $3.54 |
BTL | Beetaloo Energy Australia | -5.53% | $0.22 |
SLX | Silex Systems | -4.91% | $4.84 |
SKS | Sks Technologies Group | -4.59% | $8.52 |
SXL | Southern Cross Media Group | -4.11% | $0.54 |
EQR | Eq Resources | -3.88% | $0.32 |
BNZ | Benz Mining Corp | -3.71% | $3.89 |
MYG | Mayfield Group | -3.59% | $2.15 |
AMP flags China momentum and bank capital release on H1 call
[1:24 pm] AMP's new management fielded questions on the doubling of China partnership earnings, bank capital efficiency and platform operating leverage, while lifting dividend and returns guidance.
On China: management attributed the 107% jump in partnership contribution to operating leverage rather than one-offs, noting CLPC's cost-to-income fell from 55% to 45% over two years while a 2023 product-mix regulatory change has now washed through, with revenue growth expected to track closer to the 9% half-on-half AUM growth going forward
On the bank: every $1bn of securitisation frees roughly $30-40m of capital, lifting the CET1 surplus to $89m, though management conceded returns "remain below where we want them to be" and prioritised capital efficiency over volume
On bank NIM: guided broadly stable at 1.25%, with a 12bp funding benefit from the AMP Bank GO transition offset by 9bp from securitisation and balance sheet optimisation
On platforms and AI: North added 74 net new advisers, roughly 3x the prior half, with the AI Implement tool in pilot and captured within controllable costs, aimed at freeing adviser capacity rather than generating direct revenue
Company page: AMP (AMP)
China steel body pushes yuan iron ore pricing in bid to dilute Australian miner power
[1:20 pm] China's main steel industry group is calling for greater use of yuan-denominated index pricing in iron ore, as Beijing moves to boost its sway over a market it says is dominated by Australian and Brazilian producers.
CISA wants yuan-based pricing to complement existing US dollar benchmarks, drawing on the large port-side spot market to better reflect Chinese supply and demand
State-backed buyer CMRG has already secured greater yuan pricing in BHP supply contracts, with similar terms expected to feature in talks with Fortescue and Rio Tinto
Fortescue is currently negotiating with CMRG and has been facing pressure from Beijing
New supply, including Guinea's Simandou project, is helping diversify the market according to CISA
Source: Bloomberg
Gold stocks soar
[12:05 pm] The S&P/ASX All Ords Gold Index is up 5.5% to the highest since 18 June. It's now on a five-day win streak, up 17.0%.
Gold prices rallied 4.2% overnight, and up a further 1.3% on Thursday to US$4,301/oz.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
PNR | Pantoro Gold | 12.7% | $2.49 | 27.0% | -49.2% |
OBM | Ora Banda Mining | 7.3% | $1.35 | 17.6% | -12.0% |
VAU | Vault Minerals | 7.0% | $5.67 | 12.3% | 4.2% |
GMD | Genesis Minerals | 6.8% | $6.88 | 13.2% | -3.9% |
BC8 | Black Cat Syndicate | 6.5% | $1.07 | 23.1% | -12.3% |
EVN | Evolution Mining | 6.5% | $13.33 | 16.0% | 6.0% |
RRL | Regis Resources | 6.3% | $7.13 | 13.6% | -5.3% |
EMR | Emerald Resources | 5.5% | $6.12 | 12.5% | -2.5% |
CYL | Catalyst Metals | 5.3% | $6.42 | 10.0% | -13.1% |
WGX | Westgold Resources | 5.3% | $5.44 | 14.4% | -13.7% |
NEM | Newmont | 5.1% | $150.87 | 13.6% | 0.5% |
NST | Northern Star Resources | 5.0% | $22.58 | 7.8% | -8.1% |
BGL | Bellevue Gold | 5.0% | $1.48 | 16.1% | -12.7% |
RMS | Ramelius Resources | 4.6% | $3.52 | 7.8% | -14.1% |
CMM | Capricorn Metals | 4.1% | $14.77 | 8.6% | 5.5% |
RSG | Resolute Mining | 4.0% | $1.03 | 3.5% | -15.9% |
SBM | St. Barbara | 3.7% | $0.56 | 20.7% | -3.5% |
ALK | Alkane Resources | 3.7% | $1.47 | 9.5% | 10.3% |
PRU | Perseus Mining | 3.5% | $5.35 | 6.6% | -2.9% |
MEK | Meeka Metals | 0.0% | $0.11 | 10.5% | -61.1% |
AMI | Aurelia Metals | 0.0% | $0.36 | 14.3% | 46.9% |
News Corp posts record Q4 as AI licensing, Dow Jones and Realtor drive margins higher
[12:02 pm] News Corp management pointed to record profitability, accelerating AI content deals and standout property earnings, while flagging more licensing agreements and litigation ahead.
On results: Q4 revenue rose 11% to $2.3bn and total segment EBITDA jumped 31% to $423m, with management noting margins expanded 280bps to 18.1%, the highest fourth-quarter profit on record and "our fastest quarterly growth in four years"
On AI licensing: existing OpenAI and Meta partnerships are described as principled benchmarks, with management saying "there are significant deals in the pipeline" spanning horizontal players and sector verticals, alongside continued litigation against firms it accuses of stealing content
On Digital Real Estate: segment EBITDA surged 46% to $222m, with REA revenue up 21% and Realtor.com revenue up 13%, its seventh straight quarter of growth despite a housing market described as "in the doldrums"
On Realtor's moat: management framed proprietary, trusted content as "a chasm" between it and rivals that "no AI engine can legally scrape", citing 5.5 visits per unique user versus Zillow and Homes.com
On HarperCollins: revenue rose 15% to $566m, with a call-out to the pending $1.5bn Anthropic settlement compensating authors and publishers, and management flagging AI's role in transforming audiobooks and translation
On cash and capital: free cash flow rose 42% to $811m and the FY26 buyback hit $643m, over four times the prior year, with management arguing the stock is "materially undervalued"
REA management flags AI-led productivity gains and margin discipline on FY26 call
[11:21 am] REA's leadership fielded questions on FY27 yield, geo-mix and cost levers, leaning on price rises, Luxe and AI-driven efficiency to underpin continued margin expansion.
On FY27 yield: low double-digit controllable growth is driven by an 8% Premiere+ price rise, with management noting "Luxe will be a much larger contributor to yield" than in FY26 while Pro subscriptions add less
On geo-mix: management stressed volatility, noting FY23 was down nearly 5% but subsequent years swung positive, and that a normalisation in Sydney and Melbourne listings could be offset by recovery in Brisbane and other cities
On costs: FY27 guided to mid-single-digit growth ex-M&A, described as "as low on cost as it has been", with offshore centres and the new FlowLab AI model giving levers to flex if listings soften
On AI productivity: the FlowLab agentic-first trial in Realtair delivered planned work 2.6 times faster, with management calling it "just the start" of rewiring engineering teams to release capacity
On capital: the buyback was not reloaded, with the final dividend lifted 25% and payout ratio at 60%, as management noted more than $1bn in franking credits makes franked dividends comparatively more attractive
On current trading: seller leads and July listings are described as flat and stable, with financial services loan application volumes narrowing the earlier gap and improving in recent weeks
Company page: REA Group (REA)
Analysts mixed on Endeavour after preliminary result and sizeable writedowns
[11:19 am] Endeavour Group shares closed (1.4%) lower on Wednesday after preliminary FY26 results showed underlying sales, earnings and profit broadly in line but profit lower, alongside substantial mostly noncash significant items covering legacy technology, winery and vineyard assets, portfolio rationalisation and strategy review costs
UBS maintained Neutral, raised target from $3.25 to $3.50: sales momentum improved sequentially through the final weeks aided by a World Cup boost to hotels demand, though consensus margins for both divisions appear too optimistic and store impairments could signal further closures.
Macquarie maintained Underperform, lowered target from $2.80 to $2.70: underlying earnings were marginally below expectations driven by retail, with writedowns largely noncash and consistent with the simplification strategy, and next year still viewed as an earnings reset as wage pressures offset announced cost reductions.
REA FY26 results: Bulls vs. bears
[10:47 am] A very choppy session so far for REA Group.
Open: +3.69% ($172.45)
High: +4.21% ($173.33)
Low: -0.14% ($166.09)
Last: +1.30% ($168.46)
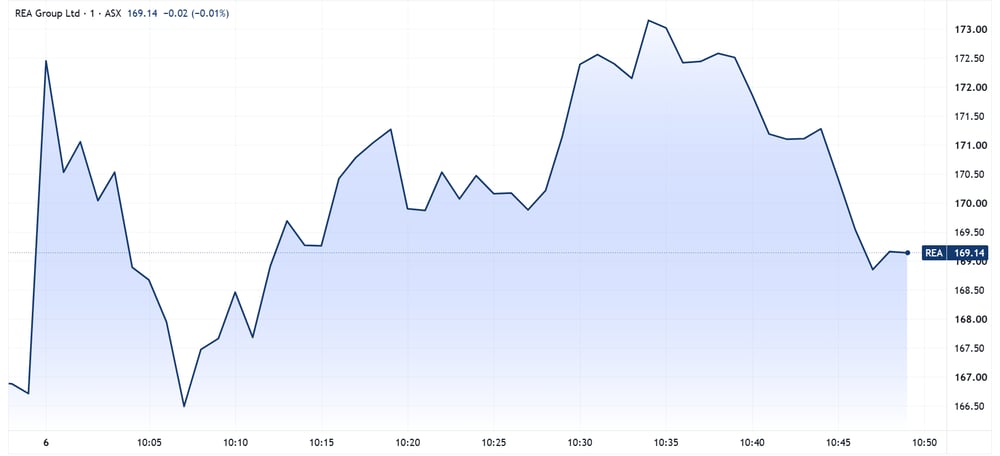
REA intraday price chart (Source: TradingView)
The FY26 result this morning was slightly ahead of market expectations across profits and dividends, with REA continuing to flex its pricing power and cost management.
Revenue up 7% to $1.79bn, in line with ests
Core EBITDA (ex-associates) up 12% to $1.09bn vs $1.06bn ests (3% beat)
Core NPAT up 15% to $650.5m vs $637.3m ests (2% beat)
Final DPS of $1.73 fully franked, with full-year dividend up 20% to $2.97 vs $2.95 Macquarie ests (1% beat)
Residential revenue up 12% on 13% Buy yield growth and flat listings, better than the anticipated 1-3% decline
The FY27 guidance flagged softening demand and volume headwinds, which is unsurprising given recent property market commentary.
FY27 new Buy listings guided flat to down low single-digits, with July down 2% and combined Sydney/Melbourne listings down 16%
FY27 yield growth guided low double-digits, underpinned by an 8% Premiere+ price rise, with operating costs up mid single-digits ex-M&A
REA is trading around the bottom of its historical valuation range, currently around 25x forward earnings. So there's a bit for everyone in this result.
Bulls: FY26 numbers broadly in-line or slightly ahead, strong cost management and buy yield growth of 13%, better-than-feared buy listings (flat vs. 1-3% decline), reaffirmed low double-digit buy yield growth
Bears: New buy listings to trend lower, Sydney/Melbourne listings down 16%, near-term earnings growth reliant on pricing, softening demand across key markets
'Sell America' debate reignites as Washington policy shifts rattle bonds and the dollar
[10:45 am] A run of policy decisions from the Fed and Treasury has some global investors reassessing their appetite for US bonds and the dollar, reviving last year's 'Sell America' trade.
Fed Chair Kevin Warsh's sparse communication has cast doubt on the Fed's inflation-fighting credibility, with an unusually high number of officials favouring an immediate hike
Treasury's sign-off on coordinated support for the yen, the first such effort in almost 30 years, risks pressuring the dollar despite being executed via the euro
30-year Treasury yield pushed above 5% to its highest since 2007, while the dollar has weakened against nearly every G10 currency over the past month despite higher yields
Term premium on 30-year Treasuries rose to 1.56%, the highest since 2013, as Treasury lifted quarterly borrowing needs to $739bn
Source: Bloomberg
ASX 200 eyes second straight record high
[10:31 am] The S&P/ASX 200 is up 0.68% in early trade, now up 5.9% in the last nine sessions.
Miners are trading sharply higher following strong gains for copper and gold prices overnight, though the Materials index is still ~4.2% away from its 17 June record high
Financials copped a bit of volatility on Wednesday, down 0.44% but tumbled as much as 1.78% intraday. The Financials index is back up at record highs today
Tech stocks are trading down ~1% after an eight-day win streak where the Tech index gained 16.5%
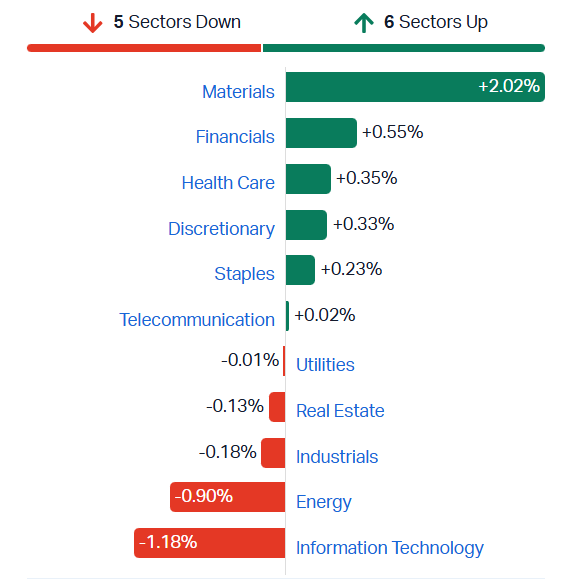
S&P/ASX 200 sectors (Source: Market Index)
Top ASX 200 gainers and losers
[10:14 am] Gold stocks dominate the top gainers list, while today's reporters (Beach Energy and Block) open slightly lower.
Ticker | Company | % Chg | Price |
|---|---|---|---|
PNR | Pantoro Gold | 7.47% | $2.38 |
VAU | Vault Minerals | 7.26% | $5.69 |
GMD | Genesis Minerals | 7.14% | $6.90 |
EVN | Evolution Mining | 6.47% | $13.33 |
GGP | Greatland Resources | 6.29% | $11.82 |
EMR | Emerald Resources | 5.69% | $6.13 |
RRL | Regis Resources | 5.52% | $7.07 |
ALK | Alkane Resources | 5.30% | $1.49 |
NEM | Newmont Corp | 5.21% | $151.00 |
CMM | Capricorn Metals | 5.14% | $14.92 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
BPT | Beach Energy | -3.37% | $0.86 |
XYZ | Block | -3.13% | $117.05 |
SLX | Silex Systems | -2.75% | $4.95 |
WTC | Wisetech Global | -2.56% | $38.89 |
PNI | Pinnacle Investment Management | -2.34% | $18.80 |
KAR | Karoon Energy | -1.95% | $1.66 |
TUA | Tuas | -1.82% | $2.16 |
360 | Life360 | -1.69% | $29.05 |
NXT | NextDC | -1.69% | $13.97 |
SHL | Sonic Healthcare | -1.57% | $21.90 |
Beach Energy beats on FY26 EBITDA, holds dividend as Waitsia lifts production
[9:39 am] Beach delivered FY26 underlying EBITDA ahead of market expectations on stronger realised gas pricing and cost discipline, though sales revenue fell short and reserves declined.
Sales revenue down 10% to $1.80bn vs $2.00bn ests (10% miss)
Underlying EBITDA down 8% to $1.04bn vs $993.5m ests (5% beat)
Underlying NPAT down 21% to $355m vs $358.8m ests (1% miss)
Final fully franked dividend of 2 cps, taking full-year dividends to 3 cps
Production of 19.4 MMboe with realised gas price up 7% to $11.5/GJ and field opex down 3% to $244m
2P reserves fell to 156 MMboe from 173 MMboe, driven by production partly offset by 3.1 MMboe of positive revisions
FY27 production guided to 19.5-23.0 MMboe, a 6% miss at the midpoint vs ests, with capex of $600-700m running slightly ahead
Company page: Beach Energy (BPT)
AMP delivers 33% underlying profit growth, unveils fresh $150m buyback
[9:30 am] AMP's first-half FY26 result beat modestly on underlying profit and dividend, driven by strong Platforms cashflows and a doubling of its China partnerships contribution.
Revenue up 6.2% to $671m vs $680.7m ests (1% miss)
Underlying NPAT up 33% to $174m vs $173.7m ests (in line)
Statutory NPAT up 57% to $154m vs $159.0m ests (3% miss)
Interim dividend of 3 cps, 20% franked, vs 2 cps ests, with a further $150m on-market buyback announced
Platforms net cashflows up 33% to $3.1bn, while Super & Investments turned positive for the first time since 2017
China partnerships contribution more than doubled to $56m, with combined annualised ROI improving to 16%
FY26 controllable costs guided to $630-640m, with AMP Bank targeting $2.0bn of AMP Bank GO deposits
Company page: AMP (AMP)
REA beats on FY26 earnings and lifts dividend 20%, but flags softer FY27 listings
[9:16 am] REA delivered core NPAT and EBITDA ahead of of market expectations on strong yield growth, though its FY27 outlook points to flat-to-lower listings amid a deteriorating demand backdrop.
Revenue up 7% to $1.79bn, in line with ests
Core EBITDA (ex-associates) up 12% to $1.09bn vs $1.06bn ests (3% beat)
Core NPAT up 15% to $650.5m vs $637.3m ests (2% beat)
Final DPS of $1.73 fully franked, with full-year dividend up 20% to $2.97 vs $2.95 Macquarie ests (1% beat)
Residential revenue up 12% on 13% Buy yield growth and flat listings, better than the anticipated 1-3% decline
FY27 new Buy listings guided flat to down low single-digits, with July down 2% and combined Sydney/Melbourne listings down 16%
FY27 yield growth guided low double-digits, underpinned by an 8% Premiere+ price rise, with operating costs up mid single-digits ex-M&A
Key quotes:
"More Australians trusted realestate.com.au for their property needs than ever before in FY26, with a record 12.7 million average monthly visitors."
"Buy yield benefited from a 7% average Premiere+ price rise, growth in add-on products, higher subscription revenues and increased depth penetration."
Company page: REA Group (REA)
US government joins race for Twiggy's Yangibana rare earths stake
[9:08 am] The Trump administration's investment arm is among a dozen suitors circling Andrew Forrest's controlling stake in the WA rare earths project, the AFR reports.
US Development Finance Corporation, Canada's Neo Performance Materials and ASX-listed Iluka are inside the BofA-run data room for Wyloo's 60% Yangibana holding
At least 12 suitors are in the auction, with Forrest targeting a signed deal by year-end
Yangibana is pitched as development ready with 20.9Mt reserves at 0.9% concentration and a 19-year life, spruiking a higher NdPr:TREO ratio than international peers
Deal includes a Wyloo option to buy a further 10% from co-owner Hastings for around $20m
Source: AFR
Block beats on Q2 profit and lifts full-year guidance as Square GPV accelerates
[9:06 am] Block topped estimates across revenue and earnings, hitting record adjusted operating income and profitability while raising its FY26 outlook.
Revenue up to $6.62bn vs $6.47bn ests (2% beat)
Adjusted EPS of $1.02 vs $0.87 ests (17% beat), up 65% year-on-year
Adjusted operating income of $864m vs $747.8m ests (16% beat)
Square GPV up 13% year-on-year, with US growth accelerating to 10%, the strongest since Q2 2023, and international up 28%
Cash App consumer lending origination up 59% year-on-year to $18.9bn, with primary banking actives up 17%
FY26 EPS guidance lifted to $4.02 ex-items from $3.85 prior, ahead of $3.90 ests (3% beat), with operating income raised to $3.47bn from $3.34bn
Company page: Block (XYZ)
Alliance Aviation lifts pricing on revised Qantas wet lease deal, trims fleet
[9:02 am] Alliance has materially revised its Qantas wet lease contract, securing better pricing from FY27 while cutting committed aircraft and right-sizing its workforce.
Revised deal delivers a meaningful pricing increase from 1 July 2026 plus a new annual escalation mechanism to better reflect future cost increases
Committed fleet steps down from 30 to 23 aircraft over FY27 on reduced flying hours, freeing capital and opening alternative uses for the aircraft
Alliance to right-size its workforce and operating model, starting a phased consultation process over coming months
FY26 underlying PBT reaffirmed at the mid-point of prior $35-40m guidance, implying around $37.5m
Principal commercial changes commence from FY27, with group-wide financial impact to be detailed at FY26 results on 25 August 2026
AQZ shares are down 77% in the past year, largely driven by a ~42% one-day selloff on 7-Nov-25 when the company announced a sharp downgrade to its FY26 guidance alongside the immediate resignation of founding managing director Scott McMillan and CFO Andrew Evans. Today's announcement marks quite a turnaround for the now ~$96 million market cap company.
Company page: Alliance Aviation Services (AQZ)
Glencore eyes ASX listing to tap Australia's $3.1tn pension pool for copper push
[9:03 am] Glencore's planned secondary listing aims to unlock mining-friendly institutional capital to fund copper growth and potentially smooth future M&A, though some managers are sceptical it will draw flows quickly.
Listing targets Australia's $4.4tn pension pool, projected to nearly triple to $12.4tn by 2045, via CDIs with no capital raising or share transfer
CEO Gary Nagle sees ASX 200 inclusion within 12 months, requiring around $1.5bn of local market cap, before qualifying for the ASX 100 at roughly $5.5bn
Interest picked up after failed Rio Tinto merger talks, with the six-month standstill on those discussions now expired, though Nagle says the listing makes no difference to any potential deal
Sceptics flag no franking credits, four work-related fatalities this year and thermal coal exposure as hurdles to superfund buying without a liquidity event
Copper is the strategic driver, with Glencore targeting about 1.6Mt output by 2035 from 810,000-870,000t expected this year, after $4bn net capex in H1 alone
Source: Reuters
Gold and copper prices soar
[8:55 am] A massive overnight session for gold, with prices up 4.2% to US$4,249/oz, the highest since 18 June. This drove a very strong response for gold equities, with a barometer like the VanEck Gold Miners ETF up 7.3% overnight.
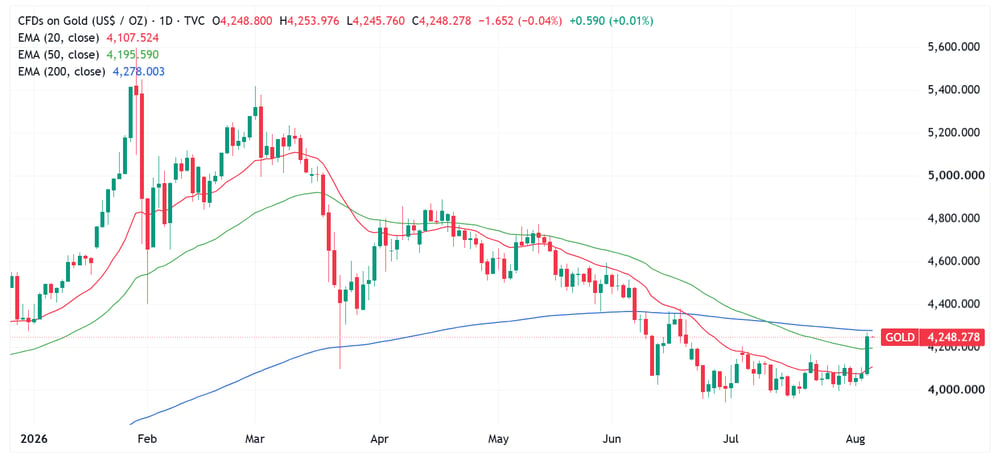
Gold daily price chart (Source: TradingView)
Copper prices also cruised to a fresh all-time high, up 1.8% to US$6.80/lb.
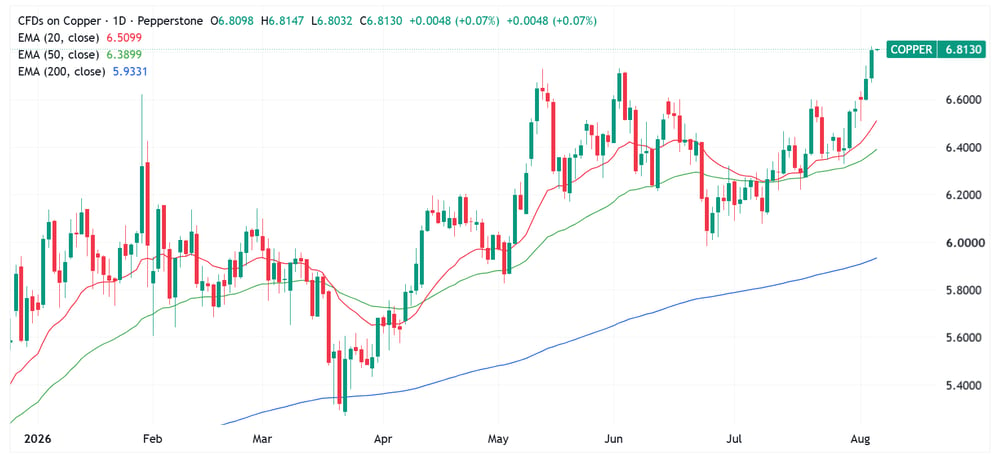
Copper daily price chart (Source: TradingView)
The Global X Copper Miners ETF rallied 3.2% overnight, but remains ~13% below its 29-Jan record high.
Sandisk smashes Q4 estimates on datacenter surge, unveils US$14bn buyback
[8:53 am] Sandisk closed FY26 with revenue up nearly fivefold year-on-year and margins expanding sharply, though its Q1 revenue guide landed below ests. The stock is down ~5.5% after hours.
Revenue up 372% to US$8.97bn vs US$8.6bn ests (4% beat)
Adjusted EPS of US$39.25 vs US$34.45 ests (14% beat), up 68% quarter-on-quarter
Adjusted gross margin of 84.6% vs 81.5% ests, up 58.2ppt year-on-year
Datacenter revenue up 103% quarter-on-quarter to US$2.98bn, with Edge up 392% year-on-year to US$5.43bn and Consumer down 5% year-on-year to US$556m
Q1'27 revenue guided to US$10.3-10.8bn vs US$11.1bn ests (5% miss at midpoint), with EPS of US$44-46 broadly in line
New US$14bn buyback authorisation lifts total remaining to US$15.5bn
Tariffs escalate as US and China trade fresh curbs across solar, tech and critical minerals
[8:47 am] A flurry of trade actions this week saw Washington move on polysilicon, transceivers and tungsten while Beijing retaliated with drone curbs and sanctions, straining a fragile truce ahead of a Trump-Xi meeting next month.
Trump readies tariffs of at least 15% and minimum import prices on polysilicon, wafers, cells and modules, with Roth Capital anticipating a 25-35% tariff, sending First Solar down as much as 7.3% and T1 Energy down 13%
FCC is drafting an order to ban Chinese optical transceivers, which made up 8.7% of China's shipments in June, hitting Zhongji Innolight down as much as 14% while US, European and Japanese rivals rallied
US bans exports of tungsten scrap and battery black mass from later this month, requiring domestic sale, in a bid to secure critical minerals and cut China reliance
China retaliates with case-by-case review on drone exports, leveraging DJI's roughly 70% share of the US commercial market, plus sanctions on six US entities
Beijing frames its response as generally restrained but warns of further countermeasures if new US restrictions land
Chinese suppliers control more than half the high-speed transceiver market, leaving cloud players few near-term alternatives and potentially softening the proposed FCC policy
Oil steadies as Iran and Oman edge toward Hormuz shipping deal
[8:45 am] Iran says a shipping agreement with Oman is in final drafting, raising hopes of reopening the Strait of Hormuz after a five-month war that has choked global energy supply.
Iran's foreign ministry says a joint statement with Oman is in final review, with a deal possible if third parties do not obstruct the process
Proposed arrangement would see ships enter the Gulf via an Iran-controlled route and exit through Omani waters, with security and environmental fees charged
Deputy FM frames it as a temporary two-to-four month route, stressing it does not mean full reopening, which Iran ties to a change in US behaviour and lifting the port blockade
Trump claims a US-Iran deal could land within 48 hours and flags denuclearisation as a second phase, though Tehran denies negotiating directly with Washington
Attacks persist, with Houthis claiming a missile strike on a Saudi tanker in the Red Sea and a cargo ship reportedly hit near the Omani port of Al Khasab
Alphabet slides 4% as AI chief Jeff Dean exits in leadership shakeup
[8:43 am] Alphabet fell as much as 5.4% after AI architect Jeff Dean departed to launch a startup, prompting a broader restructuring of the company's AI leadership.
Dean, Google's 30th employee and a Google Brain co-founder, leaves with fellow AI veterans Oriol Vinyals, Quoc Le and Sanjay Ghemawat to launch Discovery Loop, a startup automating scientific research
Alphabet is backing the venture as founding investor and cloud partner, alongside seed co-leads Radical Ventures and Khosla Ventures
Departures add to recent AI talent losses, following Noam Shazeer's exit to OpenAI and John Jumper's to Anthropic
Demis Hassabis steps back from day-to-day DeepMind operations to become GDM Chair and Alphabet Chief Scientist, retaining Isomorphic Labs
Hedge funds hammered in July as AI selloff forces fire sales
[8:42 am] A brutal reversal in crowded AI and momentum trades drove steep hedge fund losses in July, with Citadel emerging as the standout winner.
Situational Awareness plunged 67% and was forced to offload most of its public equities book to Citadel at a 10% discount to meet margin calls
PivotalPath's TMT index fell 10%, its worst benchmark, after momentum, crowded longs and equity beta had compounded at roughly 25% annually over three years
Whale Rock's flagship fell 21.7% and Altimeter dropped 11%, though both remain strongly positive for the year at 35.1% and 34% respectively
Citadel's flagship Wellington fund rose 5.9% on the Situational Awareness deal, lifting its year-to-date gain to 12%
Source: Bloomberg
Tech trade may lean more on retail after July rout, JPMorgan warns
JPMorgan says a brutal July for tech hedge funds could structurally shrink their capacity to hold the sector, leaving it more exposed to retail-driven swings.
TMT sector hedge funds lost more than 10% in July on preliminary Pivotal Path data, excluding Situational Awareness which was forced to sell the bulk of its public portfolio
Losses point to forced liquidations of semiconductor and memory exposure across other tech-focused funds
Philadelphia Semiconductor Index shed 21% in July, its worst month since 2008, as investors rotated out of top AI names on spending concerns
JPMorgan expects tighter risk frameworks and concentration limits, plus reduced prime broker balance sheet allocation, to curb funds' ability to hold volatile tech
If that capacity is structurally reduced, the tech trade grows more dependent on retail and more vulnerable to leveraged ETFs, retail options buying and margin accounts
Source: Bloomberg
SpaceX slides as $101bn lockup expiry looms
[8:41 am] Insider selling restrictions lift Thursday just as the stock trades below its IPO price, drawing heavy short interest.
Up to 911.5 million shares unlock Thursday, more than doubling the tradeable float to as much as 1.55 billion from about 639 million
Shares slumped more than 10% Wednesday to near US$110, having fallen 38% below their June 16 high and reversing a rally that had briefly added over US$250bn in market cap
Short sellers now hold 35% of the tradeable float, sitting on US$5.3bn in paper profits, with the lockup overhang expected to persist until December
First quarterly result triggered a 13% slide on higher-than-expected AI spending, though revenue beat ests on the back of the profitable Starlink business
Nine-stage unlock structure defers many backers until early December, when tradeable shares jump to 5.33 billion
Source: Bloomberg
Good morning!
[8:27 am] ASX 200 futures are down 9 pts (-0.09%). Here's what happened overnight:
Major US benchmarks gave back early gains to finish mostly lower
S&P 500 (-0.17%), Nasdaq (-0.83%), Russell 2000 (-0.59%) but the Dow (+0.49%) closed at fresh all-time highs
S&P 500 up as much as 0.74% in early trade, but this follows a four-day win streak where the index rallied 5.7%
Trump said a Strait of Hormuz deal "Could happen. Tomorrow or the next day," though Brent edged 1.2% higher to US$79.64 a barrel
Copper (+1.83%) surged to all-time highs of US$6.80/lb, while gold (+4.1%) recorded its best day since 28-Jan, rallying above US$4,200