ASX 200 Live Today - Thursday, 20th August
The ASX 200 is trading higher as a massive miner, healthcare and tech rally offset persistent declines for banks, industrials and telcos.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Thursday, August 20. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Reporting season is heating up and we've got you covered. Our reporting season calendar has over 250 stocks plus earnings and dividend estimates.
ASX 200 green for the first time in six sessions
[3:15 pm] The S&P/ASX 200 is set to snap a six-day losing streak, though three sectors (Materials, Healthcare and Tech) are doing all the heavy lifting, offsetting sizeable declines for Telcos, Industrials and Financials. The index is currently up 21 pts (+0.24%), well-off session highs of 0.63%.
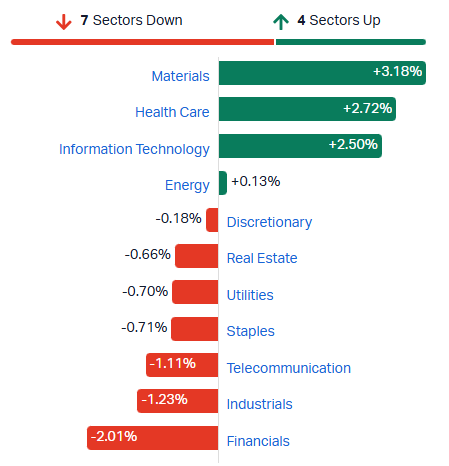
S&P/ASX 200 sectors (Source: Market Index)
Apologies for the somewhat thin volume of blog posts today. It's pretty chokkas soloing the blog and wrangling other things. My inbox is always open if you have any questions or feedback (which might even turn into a post/section). You can reach me at [email protected]. A lot to unpack today, so a bit of a longer, rambling style closer.
The US Treasury Department's move to double its buyback of long-dated bonds is an interesting one. Here's the nutshell from what I've read from various analysts, commentators and sites:
How Bessent justified it (as not QE): "This increase in buyback operation sizes reflects Treasury’s desire to provide greater liquidity support in longer-dated nominal sectors where there is consistent strong sponsorship from market participants, as evidenced by the significant volume of high-quality offers Treasury routinely receives in longer-dated buyback operations."
The buybacks are not enough when you consider all the AI/data centre capex issuance over the past few months, and massive deficit increases, globally
Markets will likely say this hike from $2bn to $4bn is not enough, and force the Treasury to do even more
This move doesn't necessarily increase liquidity, if at all. The US is just buying long-dated debt with ... short-dated debt (since the government doesn't run a surplus)
Gold surged 4.3% overnight to US$4,522/oz, and now a bellwether like Newmont sits just ~6% off its 29 January all-time high, while gold itself is still ~20% below its own 29 January record. It points to a funny relationship between mining equities and commodity prices. Right now gold equities are printing money, but their valuations stay vulnerable to any pullback in the gold price. The flip side is that gold only needs to show signs of stabilising for the equities to rebound quickly. Copper sits in a more uncertain phase. Prices are near all-time highs, yet copper names have refused to follow amid uncertainty about US import tariffs. But if copper simply trades sideways from here, the equities eventually have to follow.
Today's reporters were relatively upbeat:
Zip (+17.4%): FY26 numbers relatively in-line, FY27 guidance was very strong (26% EBTDA growth vs. 10% UBS ests, US TTV growth of more than 30% vs. UBS implied ests of 21%). Short interest has eased from April peaks of ~12.7%, but at a still-elevated 8.26%. So potentially some short squeezing there on the guidance beat
Super Retail (+14.5%): FY26 revenue up 3.2% to $4.2bn (in-line) but normalised NPAT down 2.8% to $226m (12% beat), the big surprise may have been he FY27 trading update, with total sales up 3.5%
Codan (+13.3%): Is the gift that keeps on giving, it reaffirmed its FY26 guidance about a week ago, and today's numbers eked out a small beat vs. market expectations, while FY27 is targeting revenue growth of 20%.
The ASX 200 is trading slightly higher as the recent bond yield and macro picture drives a more selective rally. Look at the financials index, which has now tanked 9.2% since 6 August, down ten of the last eleven sessions, as pretty much every lender has pointed to a sharp slowdown in loan originations. The other move is in the high-flying industrial names like SKS, DOW, SSM and SHA, most of which have rallied strongly over the last twelve months and posted strong FY26 results, yet are now fading or seeing extreme price volatility on results day. It looks like those share prices need to take a breather and consolidate. Meanwhile, healthcare stocks are in the midst of a recovery for the ages. The S&P 500 healthcare sector is trading at fresh all-time highs, and so are other biotech-related ETFs. Along with the better-than-feared results from Cochlear and CSL, we'll have to see just how far this sector can trend.
Pepper Money 1H26 earnings call highlights: Record originations even as mortgage market slows
[1:35 pm] Highlights from Pepper Money's 1H26 earnings call, where management talked to record volume growth, the servicing expansion via RAMS and HSBC, and a softening mortgage application backdrop
On the mortgage market slowdown: management pointed to federal changes to CGT, negative gearing and SMSF residential lending having "a marked impact", with Equifax mortgage inquiry data down 20% in the three months to July versus a year earlier and down 15% since the May budget
On outperformance despite the slowdown: mortgage originations grew 63% on PCP to $4.5bn, the highest in any half, growing at 7.1 times system, with prime lifting to 79% of originations from 70%
On application trends into August: the CEO flagged a "complete halt" of SMSF residential lending with those applicants shifting to commercial SMSF, offset by rising non-conforming and owner-occupied applications, plus strength in refi, debt consolidation and construction lending
On the outlook for inquiries: management was pragmatic that "inquiry volumes are likely to continue slowing as interest rate uncertainty persists and inflation remains above the RBA's target band"
On SMSF pull-forward: management confirmed there "definitely was" pull-forward of residential SMSF lending before June, though it is a small percentage of the overall originations profile
On margins: total NIM rose 12bps on PCP to 2.1%, with mortgage NIM up 13bps to 1.64% helped by lower funding costs and full pass-through of RBA rate increases
Company page: Pepper Money (PPM)
Super Retail FY26 earnings call highlights: rebel margin recovery and a value push as the consumer stays under pressure
[12:43 pm] Highlights from Super Retail Group's FY26 earnings call, where management talked to the fuel crisis impact, rebel's margin turnaround and a resilient but choppy sales backdrop into FY27
On the trading backdrop: management flagged a strong first half disrupted by the fuel crisis over the key Easter period, with the CEO stressing "the consumer is doing it really tough" and cautioning "I would not be banking too much" on margin upside
On the World Cup benefit to rebel: volumes were lifted 70% versus four years ago and sold out early, though management declined to quantify it and confirmed July was a "clean number" with no flow-through, meaning it will be cycled in FY27
On rebel's margin turnaround: the second-half gross margin gain reflected full-price sales of licensed World Cup product, improved promotional discipline and better availability, though management stressed "we have a lot of work to do in that space"
On Supercheap Auto inflation: oil-based products including lubricants, aerosols and paints are carrying inflation that is partly absorbed and partly passed on, with customers showing a stronger value orientation and response to promotions
On the FY27 start: like-for-like sales up 1.5% and total sales up 3.5% over the first seven weeks, with the best-performing oils campaign a "wash" year-on-year, though management stressed this is just seven weeks of a 53-week year
Company page: Super Retail Group (SUL)
Vicinity FY26 earnings call highlights: premium repositioning drives a step change in FY27 earnings growth
[12:42 pm] Highlights from Vicinity Centres' FY26 earnings call, where management talked to the portfolio repositioning, development returns and a moderating but resilient sales backdrop
On the FY27 inflection: management framed the year as "a meaningful inflection point", with FFO per security guidance of 16.0 to 16.2cps implying growth of 5.3% to 6.6%, supported by a full year of Chatswood Chase income, Galleria opening in November and a stronger FY26 base
On Chatswood Chase returns: the $625m transformation now expects a stabilised yield of around 6.7%, up ~70bps, and an unlevered IRR of around 11%, up ~100bps, with the uplift "all based on income" and estimated development profit of more than $250m
On the sales backdrop: portfolio MAT growth was 3.3%, with management calling sales "quite resilient" but choppy, and July finishing at around 3% comp growth (about 4% across mini majors and specialties), an uptick on May and June
On luxury moderating: cost of living pressures hit the aspirational customer, though the category still delivered exceptional productivity of around $61,000 per square metre
On leasing spreads: the full-year 4.2% was a record, but Q4 spreads moderated to around 2%-2.5% and FY27 guidance assumes a more conservative ~3%, with occupancy at 99.6% and ~26% tenant churn supporting active curation
On capital recycling: with 16 assets sold in three years, management said "we've broken the back of it", with Box Hill North on the market and one or two other potential trades, but the core divestment program materially complete
Company page: Vicinity Centres (VCX)
Brambles FY26 earnings call highlights: US repair crunch a "perfect storm" with a fix due by December
[12:41 pm] Highlights from Brambles' FY26 earnings call, where management detailed the US repair capacity constraints, the path to recovery, and confidence in offsetting structural cost increases
On the US disruption: management characterised the constraints as "not the result of a single factor" but a convergence of a tight labour market, subcontractor exits and a Q4 demand spike, together an $90m underlying profit hit, adding "I hope you now see it really was a perfect storm"
On service recovery: there have been "no missed customer orders since mid-June", with the CEO confident of resolving repair capacity constraints by December, and confirming "there have been no further subcontractor exits from our network since April"
On the FY27 earnings drag: the CFO guided a total year-on-year underlying profit impact of $35m to $55m from the constraints, sitting within group guidance of 2%-6% profit growth, with a mid to high single-digit decline in H1 followed by low double-digit growth in H2
On offsetting structural costs: with labour inflation "an issue for everybody, every business sector in the US", management expects to recover it as part of normal cost-to-serve increases through pricing and productivity, prioritising internal efficiencies before going to customers on price
On the demand backdrop: consumption "has definitely normalised", with the Q4 spike driven by one-off events like the FIFA World Cup and the 250th 4th of July that will not repeat, though management said "I would prefer stronger like-for-likes" as that drives the business
Company page: Brambles (BXB)
NRW FY26 earnings call highlights: Margin uplift and M&A firepower as pipeline swells to $29bn
[12:40 pm] Highlights from NRW Holdings' FY26 earnings call, where management talked to margin expansion, Fredon's growth runway, and appetite for further acquisitions
On the underlying result: "if you back out Fredon's contribution, the balance of the group delivered a very impressive 22% year-on-year increase", with the CFO noting every segment delivered earnings growth
On the refinance and M&A firepower: the bank facility was extended and lifted by $300m to $700m plus a $100m accordion, giving the group capacity "to be able to act quickly and efficiently in the event that we did want to undertake any M&A transactions"
On M&A discipline: management flagged recently withdrawing from a process as one of two remaining bidders "because of value", underlining "the discipline in terms of strategic value versus where the market is at the moment"
On Fredon's growth runway: the CFO confirmed the business should do "$1 billion in FY27" off the $840m pro forma base, with the CEO saying prior assumptions of 20%-plus growth were "probably undercooked"
On Fredon margins: second-half margins stepped up considerably, with management "targeting 6% by at least run rating by the end of FY 2027"
On mining margins into FY27: the usual range is "between 9% and 11%, depending on the capital intensity", with client-supplied equipment on the new Meandu project (run rate ~$150m) sitting at the lower end
On civil margins: management sees potential to reach "the sixes" and possibly toward 7%, though flagged the focus is "more about improving the profitability across the business" than hitting revenue targets
On competitive dynamics: with the MET tender market full, "there is no capacity left in that market because all of those competitors are absolutely full", leaving NRW well placed on pricing
On capex: FY27 expected around $165m, up from $147m, with growth projects like Meandu funded by client capital
Company page: NRW Holdings (NWH)
Gold stocks surge, now positive year-to-date
[12:02 pm] The All Ords Gold Index is up 8.1% in early trade, now up 4.4% year-to-date. Gold prices experienced a massive 4.3% rally overnight to US$4,522/oz after the US Treasury Department made a surprise move to ramp up buybacks of long-dated government debt, signaling it wants to lower long-term borrowing costs after yields hit multi-decade highs. It's quite extraordinary to see most gold names up 30-40% in the past month, but still flattish year-to-date.
Ticker | Company | % Chg | Price | 1 Month | YTD |
|---|---|---|---|---|---|
MEK | Meeka Metals | 14.3% | $0.12 | 26.3% | -55.6% |
OBM | Ora Banda Mining | 13.3% | $1.58 | 57.5% | 2.9% |
RMS | Ramelius Resources | 10.8% | $3.97 | 36.7% | -3.1% |
RRL | Regis Resources | 10.2% | $8.18 | 44.8% | 8.8% |
GMD | Genesis Minerals | 9.8% | $7.97 | 42.3% | 11.3% |
VAU | Vault Minerals | 9.1% | $6.49 | 38.7% | 19.3% |
RSG | Resolute Mining | 9.0% | $1.28 | 35.6% | 4.1% |
EVN | Evolution Mining | 8.8% | $14.89 | 43.1% | 18.4% |
EMR | Emerald Resources | 8.5% | $7.03 | 41.2% | 11.9% |
BC8 | Black Cat Syndicate | 8.4% | $1.16 | 32.6% | -4.5% |
PRU | Perseus Mining | 8.3% | $6.10 | 30.6% | 10.7% |
WGX | Westgold Resources | 8.3% | $6.20 | 39.8% | -1.7% |
SBM | St. Barbara | 8.2% | $0.66 | 53.5% | 14.8% |
PNR | Pantoro Gold | 8.1% | $2.62 | 33.4% | -46.6% |
CMM | Capricorn Metals | 8.0% | $17.23 | 45.0% | 23.1% |
ALK | Alkane Resources | 7.6% | $1.72 | 23.5% | 29.1% |
BGL | Bellevue Gold | 7.2% | $1.63 | 35.3% | -3.6% |
NEM | Newmont | 7.0% | $177.26 | 38.3% | 18.1% |
NST | Northern Star Resources | 7.0% | $24.11 | 26.0% | -1.8% |
AMI | Aurelia Metals | 6.6% | $0.41 | 37.3% | 65.3% |
CYL | Catalyst Metals | 3.4% | $6.73 | 23.9% | -8.8% |
Australian unemployment rises to 4.5% in July as employment unexpectedly falls
[11:41 am] Australia's jobless rate climbed to 4.5% in July, above the 4.4% ests, while employment fell against expectations for a gain.
Unemployment rate rose to 4.5% vs 4.4% ests, with the number of unemployed up 4,000
Employment fell 16,000 vs ests for a 15k gain, a sizeable miss driven mostly by males, where employment dropped 11,000
Participation rate fell 0.2 percentage points to 66.9%, with the employment-to-population ratio also down 0.2 points to 63.9%
Underemployment rate steady at 6.4%, while the underutilisation rate rose 0.1 points to 10.8%
Hours worked down 0.6% in July, led by New South Wales and Western Australia, both down 8 million hours
Top ASX 200 losers
[10:27 am] High-flying industrial names like Downer, SRG, NRW and more, are selling off, despite reporting strong year-on-year growth. Yield-sensitive names like Suncorp and other insurers trading lower as long-dated yields eased overnight.
Ticker | Company | % Chg | Price |
|---|---|---|---|
DOW | Downer EDI | -12.48% | $6.52 |
HLI | Helia Group | -9.68% | $5.13 |
MPL | Medibank Private | -8.05% | $4.63 |
SLC | Superloop | -7.51% | $3.08 |
SHL | Sonic Healthcare | -6.75% | $21.97 |
BSL | Bluescope Steel | -6.38% | $30.10 |
SRG | SRG Global | -5.37% | $3.88 |
NWH | NRW | -4.16% | $6.91 |
NHF | NIB | -3.47% | $7.23 |
TLC | Lottery Corporation | -2.80% | $5.21 |
HUB | Hub24 | -2.77% | $77.53 |
IAG | Insurance Australia Group | -2.70% | $7.92 |
AIA | Auckland International Airport | -2.64% | $7.20 |
VNT | Ventia Services Group | -2.58% | $5.66 |
QBE | QBE Insurance | -2.56% | $22.09 |
SUN | Suncorp Group | -2.34% | $17.92 |
SGM | Sims | -2.18% | $22.18 |
CGF | Challenger | -1.94% | $9.61 |
BEN | Bendigo & Adelaide Bank | -1.83% | $10.21 |
JDO | Judo Capital | -1.77% | $1.00 |
Top ASX 200 gainers
[10:27 am] Lots of stocks on the move today, so we've separated the top gainers and losers post (and extended the list to 20 stocks). Zip is surging on an FY27 guidance beat, while gold miners open 8-10% higher as gold prices surged ~4% overnight.
Ticker | Company | % Chg | Price |
|---|---|---|---|
ZIP | Zip Co | 16.28% | $3.00 |
SUL | Super Retail Group | 15.84% | $14.55 |
OBM | Ora Banda Mining | 11.15% | $1.55 |
GGP | Greatland Resources | 10.44% | $13.44 |
RMS | Ramelius Resources | 10.34% | $3.95 |
GMD | Genesis Minerals | 10.33% | $8.01 |
RRL | Regis Resources | 10.24% | $8.18 |
VAU | Vault Minerals | 10.00% | $6.55 |
RSG | Resolute Mining | 9.15% | $1.28 |
CDA | Codan | 9.13% | $47.45 |
PNR | Pantoro Gold | 8.88% | $2.64 |
EVN | Evolution Mining | 8.48% | $14.84 |
EMR | Emerald Resources | 8.26% | $7.02 |
WAF | West African Resources | 7.90% | $3.76 |
WGX | Westgold Resources | 7.87% | $6.17 |
MI6 | Minerals 260 | 7.85% | $0.85 |
PRU | Perseus Mining | 7.73% | $6.07 |
CMM | Capricorn Metals | 7.68% | $17.18 |
NST | Northern Star Resources | 7.45% | $24.22 |
KCN | Kingsgate Consolidated | 7.41% | $5.22 |
Cuscal lifts statutory profit 49% and guides to mid-twenties FY27 growth
[9:51 am] The B2B payments provider beat ests at the statutory profit line on two acquisitions, though net operating income came in slightly short.
Underlying net operating income up 20% to $347.7m vs $354.8m ests (2% miss)
Statutory NPAT up 49% to $42.7m vs $38.1m ests (12% beat)
Underlying NPAT up 20% to $46.2m
Aggregate transaction volume up 12%, reflecting the acquisitions and growth across core capabilities
Final dividend of 7.0cps, taking the full-year dividend to 11.5cps vs 11.5cps ests (in line)
FY27 guidance of mid-20% underlying NPAT growth implies roughly $58m, sitting a touch above the $56.1m ests, with transaction volume growth guided at the same rate
MD Craig Kennedy said the two deals have significantly increased scale across Australia and New Zealand, with FY27 focused on integration and delivering synergies
Company page: Cuscal (CCL)
Sonic Healthcare hits FY26 guidance with profit up 17%
[9:47 am] The global pathology group delivered organic revenue growth of 5% and realised acquisition synergies in Europe, landing broadly in line with ests.
Revenue up 13% to $10.86bn vs $10.95bn ests (1% miss)
Underlying EBITDA up 11% to $1.93bn vs $1.94bn ests (in line), achieving guidance of $1.87bn-$1.95bn
Underlying NPAT up 17% to $621m vs $604m Morgans ests (3% beat)
Total FY26 dividends up 1cps to $1.08 per share, in line with ests, maintaining the progressive policy
Organic revenue growth of 5%, with strong growth in advanced diagnostics and substantial synergies realised from recent German and Swiss acquisitions
CEO Dr Jim Newcombe flagged a comprehensive operating review of the US business is underway, alongside a significant program to modernise global digital infrastructure
Company page: Sonic Healthcare (SHL)
Dexus meets FY26 guidance but flags a sharp FY27 earnings step down
[9:45 am] The diversified property group delivered on guidance and swung to a much larger statutory profit, though FY27 AFFO guidance implies a double-digit decline as trading profits and fees normalise.
AFFO of $483.9m or 45.0cps, in line with guidance and flat on the pcp
Distributions of $397.4m or 37.0cps, an 82.1% payout ratio
Statutory NPAT of $482.2m, up from $136.1m in FY25 on stabilising cap rates and positive revaluations
NTA per security up 1% to $8.92, with portfolio valuations up circa 1.0% on prior book values
Look-through gearing of 33.4%, toward the lower end of the 30-40% target range, with $2.5bn of cash and undrawn facilities
Office occupancy of 95.7% and industrial occupancy of 94.6%, with rent collections at 99.7%
Raised $2.0bn of third-party equity and exchanged or settled circa $1.9bn of divestments, taking the total to $2.5bn since FY24 and beating the $2bn FY25-FY27 target early
Strategic review underway of the infrastructure funds from the 2023 AMP Capital deal, covering $7.3bn of third-party FUM and roughly $35m of management fees, with finalisation potentially delayed until the APAC appeal is heard in October
FY27 AFFO guidance of 37.5-39.5cps (mid 38.5cps) implies a 14% decline on FY26, with distributions held at 37.0cps
CEO Ross Du Vernet flagged lower trading profits and performance fees, continuing funds headwinds, higher finance costs and practical completion of Atlassian Central as the FY27 drags, alongside a materially lower contribution from FUM under review
Company page: Dexus (DXS)
Zip lifts cash earnings 58% and guides FY27 well ahead of ests
[9:40 am] The buy now pay later group beat FY26 ests on cash earnings, with FY27 guidance implying materially more growth than UBS had modelled.
Total transaction volume up 27.2% to $16.7bn vs $16,681m UBS ests (in line), with US TTV up 42.5% in USD
Total income up 24.6% to $1,347.4m vs $1,334m UBS ests (1% beat), with revenue margin easing to 8.1% from 8.3% on higher US mix
Cash gross profit up 26.2% to $642.3m vs $628m UBS ests (2% beat), with cash net transaction margin steady at 3.9%
Cash EBTDA up 57.9% to $268.9m vs $263m UBS ests (2% beat), with operating margin expanding 420bps to 20.0%
Net bad debts of 1.77% of TTV versus 1.52% in FY25, within management targets, with US bad debts of 1.73%
Active customers up 3.7% to 6.5m vs 6.6m UBS ests (2% miss), with merchants up 13.8% to 97.4k
FY27 cash EBTDA guidance of $340m implies 26% growth and sits 10% above $309m UBS ests
FY27 US TTV growth guidance of greater than 30% compares with the 21% growth implied by UBS ests
Completed $150m of buybacks in FY26 with a further $50m program announced for FY27, plus up to $37.5m of on-market purchases for the employee share trust
Considering a share consolidation to be put to the 2026 AGM, and continues to weigh a potential US dual listing
Company page: Zip Co (ZIP)
Goodman lifts operating profit 16% as data centres drive WIP to $19.7bn
[9:36 am] The industrial property group met FY26 ests and guided to 9% FY27 earnings growth, with data centres now dominating a development pipeline that grew over 50% during the year.
Operating profit up 15.7% to $2,674.5m vs $2,665m NPAT ests (in line)
Operating EPS up 10.1% to 129.9cps vs 129.6cps ests (in line)
Development earnings up 34% to $1,792.2m, the biggest contributor to the result
Property investment income up 7% to $722.1m, with the total portfolio up 4% to $89.0bn and cap rates tightening to 5.0%
Management earnings of $690.1m, with external AUM up 5% to $75.4bn and $3.2bn of third-party equity raised across four new partnerships
Distribution held at 30.0cps vs 30.2cps ests (in line)
WIP up over 50% to $19.7bn across 50 projects at a forecast 8.2% yield on cost, with data centres now 78% of the book and roughly 50% of projects leased or in advanced negotiation
Power bank up to 6.4GW across 16 cities from 5.0GW and 13 cities, with ~0.5GW of data centre developments underway
FY27 OEPS growth target of 9% implies ~141.6cps, around 1% below 143.1cps ests
CEO Greg Goodman flagged hyperscaler capex expectations continuing to rise with many customers facing undersupply into 2027 and 2028, and a 20-year, 50MW lease recently signed with a hyperscale customer in Tokyo
Company page: Goodman Group (GMG)
Fortescue lifts EBITDA 9% on record shipments but profit and dividend miss ests
[9:34 am] The iron ore miner delivered record shipments and a 25% jump in free cash flow, though underlying profit and the dividend fell short of Macquarie ests and FY27 unit costs are set to rise.
Record iron ore shipments of 201.3Mt vs 199Mt Macquarie ests (1% beat)
Hematite C1 unit cost of US$18.74/wmt vs US$18.72 Macquarie ests (in line)
Underlying NPAT up 3% to US$3.5bn
Statutory NPAT of US$2.9bn vs US$3.02bn Macquarie ests (4% miss), including a US$525m non-cash Iron Bridge impairment and a US$73m compensation claim expense
Cash of US$5.1bn and net debt of just US$0.9bn, with gross debt to EBITDA of 0.7 times and gross gearing of 23%
Fully franked final dividend of 46cps, taking the FY26 total to $1.08 per share vs $1.18 Macquarie ests (8% miss), a 65% payout of underlying NPAT
FY27 shipment guidance of 197-207Mt (mid 202Mt) is in line with 202Mt Macquarie ests and broadly flat on FY26, including 11-14Mt from Iron Bridge
FY27 Hematite C1 cost guidance of US$20.50-US$21.75/wmt (mid US$21.13) implies a 13% increase on FY26, though sits 1% below US$21.45 Macquarie ests
FY27 metals capex guidance of US$3.7bn-US$4.7bn (mid US$4.2bn) implies a 17% step up, and is broadly in line with Macquarie ests once Energy spend is included
Company page: Fortescue (FMG)
Codan lifts profit 69% and guides to FY27 growth well ahead of ests
[9:31 am] The defence communications and metal detection group beat single-broker ests across the board in FY26, with FY27 revenue guidance implying a materially higher base than currently modelled.
These ests all refer to Macquarie's forecasts as at 13 May.
Revenue up 30% to $875.0m vs $847.7m ests (3% beat)
Communications revenue up 22% to $506.2m vs $496.2m ests (2% beat), above the 15-20% target range, with segment profit up 45% to $156.0m vs $148.9m ests (5% beat) and margin of 31%, hitting the FY27 target 18 months early
Metal Detection revenue up 42% to $362.0m vs $344.0m ests (5% beat), with segment profit up 65% to $162.4m vs $158.2m ests (3% beat) and margin up to 45% from 39%
EBITDA up 57% to $288.9m vs $278.1m ests (4% beat), with margin up to 33.0% from 27.2%
EBIT up 67% to $244.1m vs $235.4m ests (4% beat), with margin up to 27.9% from 21.7%
NPAT up 69% to $175.2m vs $169.4m ests (3% beat), slightly above the guidance provided on 29 April
EPS up 69% to 96.5cps
FY26 fully franked dividend up 70% to 48.5cps, including a final of 29.0cps
Communications orderbook up 50% to $380m, with defence customers now 58% of segment revenue versus 38% in FY25 and unmanned revenue more than doubling to ~$215m
Net cash of $35.7m vs. net debt of $88.2m at 31 December, a $123.9m swing in six months
FY27 revenue growth targeted in the order of 20%, implying ~$1,050m against $963.8m ests (9% above), with 1H27 expected to significantly exceed 1H26 subject to emerging global electronics supply chain constraints
CEO Alf Ianniello flagged elevated defence spending and geopolitical tensions continuing to drive unmanned systems demand, with Minelab supported by a favourable gold price
Company page: Codan (CDA)
Maas Group posts record FY26 but scraps final dividend for buybacks
[9:25 am] The Dubbo-based diversified construction, materials and property group delivered record earnings on a surge in electrical infrastructure work, though the board has pivoted capital away from dividends.
Underlying revenue up 27% to $1,263.8m vs $1,331m ests (5% miss)
Underlying EBITDA up 37% to $300.3m vs $263m ests (14% beat), in line with updated $300m-$310m guidance
Civil Construction and Hire underlying EBITDA up 64% to $65.1m on revenue up 47% to $424.9m, driven by Electrical
Construction Materials underlying EBITDA flat at $115.4m despite revenue up 24% to $629.6m, with weather and fuel costs weighing on Quarries and Concrete
Commercial Real Estate underlying EBITDA up 20% to $59.4m, including $57.4m of investment property fair value gains, roughly 62% of which relate to properties yet to settle
Continuing ops underlying EBITDA excluding fair value uplift up 37% to $143.3m, above the $130m-$135m guidance range
Underlying EPS up 51% to 34.2cps vs 27.8cps ests (23% beat)
No final dividend declared vs. Macquarie ests of a 4.4 cps final dividend, with the board redirecting capital to buybacks after $55.1m invested since February and AGM approval to be sought to lift capacity to 20% of issued capital
Electrical work in hand of ~$1.2bn to be delivered over 18 months, including the $855m Firmus order secured in August, with the $1.703bn Construction Materials sale to Heidelberg on track to complete in October
CEO Wes Maas said the Firmus contracts give locked-in, visible earnings growth in FY27 and beyond, with the company guiding to strong revenue and profit growth from continuing operations
Company page: Maas Group Holdings (MGH)
Brambles grows earnings 4% but US repair issues drag and FY27 guidance lands soft
[9:21 am] The pallet pooler met its revised FY26 guidance, though a ~US$90m hit from US repair capacity constraints weighed and FY27 guidance implies growth below ests.
Revenue up 2% to US$7.04bn vs US$7.04bn ests (in line), with price realisation and volume contributing equally and net new business growth of 3%
Underlying profit up 4% to US$1.49bn, or ~11% growth excluding the ~US$90m adverse impact from US repair capacity constraints
Operating profit after tax up 5% to US$948.5m vs US$943.1m NPAT ests (1% beat)
Total FY26 dividends up 16% to 46.15 UScps vs 43.4 UScps Morgans ests (6% beat)
Completed US$509m of buy-backs in FY26, with the current US$400m program on track to finish in FY27
FY27 revenue guidance of 2-4% constant currency growth (mid 3%) sits below the 4.3% growth implied by $7,340m FY27 ests
FY27 underlying profit guidance of 2-6% constant currency growth (mid 4%) sits just below the ~5% implied by $993m FY27 NPAT ests
FY27 free cash flow guidance of US$800-950m (mid US$875m) implies a 17% decline on FY26
Growth is weighted to the second half, with a mid-to-high single digit decline in 1H27 offset by low double-digit growth in 2H27
CEO Graham Chipchase said order fulfilment has improved materially since mid-April, with US repair constraints on track to be resolved by the end of 1H27, though 3.4 million excess US pallets will not be fully utilised until the end of FY28
Company page: Brambles (BXB)
Pepper Money lifts profit 15% as servicing wins reshape the business
[9:17 am] The non-bank lender delivered record originations and AUM in 1H26, with two large portfolio servicing mandates set to nearly double assets under management.
Total originations up 40% to $6.3bn, a record half, with mortgage originations up 63% to $4.5bn and asset finance up 2% to $1.7bn
Total AUM up 20% to a record $24.0bn, with mortgage AUM up 32% to $12.5bn and asset finance AUM down 4% to $6.0bn after a $1.0bn whole loan sale
Net interest income up 17% to $184.5m, with NIM up 12bps to 2.10%
Statutory NPAT up 7% to $50.4m and pro-forma NPAT up 15% to $53.9m, including $3.5m of costs from the lapsed Challenger approach
Loan loss expense up 19% to $48.7m on volume growth and heavier downside weightings, with provision coverage steady at 0.79%
Fully franked interim dividend of 7.2cps, up 12% on the pcp, at the top of the 60% payout policy
Appointed servicer of the $15.4bn Westpac RAMS portfolio, which completed 1 August, taking total AUM to just under $40bn, with the HSBC Australia portfolio mandate expected to complete in 1H27
CEO Mario Rehayem flagged a reduction in new application activity following federal changes to CGT, negative gearing and SMSF residential lending
Company page: Pepper Money (PPM)
AFG lifts profit 39% as manufacturing loan book hits record
[9:16 am] Australian Finance Group, a mortgage aggregator and lender, delivered broad-based earnings growth in FY26 with recurring income now underpinning around 90% of earnings.
NPAT up 39% to $49m
Underlying NPATA up 33% to $54m
Manufacturing loan book up 30% to a record $7.1bn, with NIM of 125bps and underlying segment ROE of 30%
Broker Services income up 13% to $24m, and asset and commercial finance settlements up 19% to $4.3bn
Underlying ROE lifted from 19% to 23%, with the cost-to-income ratio down to 55% and 94% cash conversion
Full-year fully franked dividend of 9.5cps, including a final of 4.8cps
FY27 sees roughly $13m of annualised EBITDA uplift carried over from FY26 investments, with only 10% of earnings directly exposed to short-term residential volume
CEO David Bailey flagged residential lodgements have softened since June as borrowers respond to tax policy settings and rate expectations, though he said underlying housing demand remains intact
Company page: Australian Finance Group (AFG)
Northern Star delivers record FY26 profit as KCGM mill expansion ramps up
[9:14 am] Northern Star reported record earnings on a higher realised gold price, with underlying profit and the dividend both ahead of Macquarie ests, though gold sold slipped and FY27 output hinges on the KCGM commissioning.
Revenue up 19% to $7.6bn
Average realised gold price up 26% to $4,925/oz
Gold sold down 6% to 1.54Moz
Underlying NPAT up 26% to $1.8bn, with underlying EPS of $1.24 vs $1.14 Macquarie ests (9% beat)
FY26 dividend of 55cps fully franked at the upper end of policy vs 53cps Macquarie ests (4% beat)
$500m on-market buy-back with $129m completed to date
FY27 group production guidance of 1,500-1,650koz vs. Macquarie ests of 1,600koz (1.5% miss)
FY27 AISC guidance of $3,050-3,450/oz (mid $3,250) vs $3,096 Macquarie ests (5% higher on cost, broadly in line)
KCGM production guidance of 550-650koz reflecting early ramp-up, with output weighted to the second half
MD Stuart Tonkin flagged an "important inflection point", with the mill expansion set to "structurally reset the cost base" as free cash generation lifts through the ramp-up
Company page: Northern Star Resources (NST)
Medibank lifts FY26 profit as health momentum builds and dividend rises
[9:11 am] Medibank grew operating profit and underlying earnings in FY26 broadly in line with Macquarie ests, with policyholder growth, strong Medibank Health momentum and a higher dividend, though net investment income fell.
Group operating profit up 6.7% to $813.5m vs $823.4m Macquarie ests (1% miss), driven by resident Health Insurance, Medibank Health momentum and controlled corporate costs
Net investment income down 13.9% to $178.9m, including a $28.9m reduction across the growth and defensive portfolios
Underlying NPAT up 2.9% to $636.8m vs $638.2m Macquarie ests (in line)
Underlying EPS up 2.9% to 23.1c vs 23.2c Macquarie ests (in line)
Statutory NPAT attributable to shareholders up 27.5% to $638.7m vs $643.3m Macquarie ests (in line)
Fully franked final ordinary dividend of 10.9cps
Full-year dividend up 6.7% to 19.2cps vs 19.4cps Macquarie ests (in line), an 83.0% payout ratio within the 75%-85% target range
Non-recurring cybercrime costs of $34.9m recognised, with FY27 costs expected below $20m as the IT security uplift is now largely embedded
FY27 outlook: Resident PHI gross margin broadly consistent with FY26, solid non-resident gross profit growth, and Medibank Health segment profit growth of c.25% including a full-year Better Medical contribution
CEO David Koczkar said people "continue to prioritise their health" despite household budget pressure, with one in four Australians delaying a GP visit due to cost
Company page: Medibank (MPL)
Super Retail beats on earnings despite profit decline as project investment weighs
[9:07 am] Super Retail Group's FY26 sales hit a record and normalised earnings landed well ahead of ests, even as deliberate project investment and higher financing costs pushed profit before tax lower.
Group sales up 3.2% to $4.2bn vs $4.19bn ests (in line), with group like-for-like growth of 1.8%
Segment EBITDA up 2.1% to $774m vs $741m ests (4% beat)
Group gross margin up 10bps to 45.7%
Normalised PBT down 7% to $306m, reflecting project investment and higher financing costs
Normalised NPAT down 2.8% to $226m vs ~$202m ests (12% beat), aided by a lower effective tax rate
Normalised EPS of 100cps vs 89.5cps ests (12% beat), statutory NPAT down 7.2% to $206m
Fully franked final dividend of 33cps, taking full-year ordinary dividends to 65cps at the upper end of payout policy
FY27 has started positively with total sales up 3.5% and like-for-like up 1.5% over the first seven weeks, though management flagged Middle East tensions, rising rates and inflation as consumer headwinds
Consensus SSS is for 1.6% in 1H27
CEO Paul Bradshaw said the group delivered record sales "in the face of significant headwinds" including Middle East instability, unfavourable weather and interest rate pressure on households
Company page: Super Retail Group (SUL)
APA delivers record FY26 EBITDA above guidance midpoint, lifts growth pipeline to $3.5bn
[9:04 am] APA Group has posted a strong FY26 result with underlying EBITDA above the guidance midpoint, margin expansion and a 22nd consecutive year of distribution growth.
Underlying EBITDA up 8.3% to $2,183m vs $2,177m ests (in line), exceeding the guidance midpoint
Underlying EBITDA margin up 370bps to 77.9%, aided by $80m of cost-out initiatives that beat the $50m target, with a $100m annualised run-rate flagged for FY27
Statutory NPAT up 81.4% to $234m, with total statutory revenue ex pass-through up 1.9% to $2,764m
Free cash flow up 3.2% to $1,118m, underpinning distributions and growth funding
FY26 distribution of 58.0cps, up 1.8%, in line with ests and guidance, marking the 22nd straight year of growth
FY27 EBITDA guidance of $2,260m to $2,340m implies 5.4% growth, with the $2,300m midpoint in line with ests, distributions guided to 59.0cps (+1.7%) also in line, and the organic growth pipeline lifted to ~$3.5bn from $3.0bn
Company page: APA Group (APA)
NRW delivers record FY26 earnings on strong momentum and Fredon acquisition
[9:02 am] NRW Holdings posted record revenue and earnings for FY26, beating consensus on the top line while lifting profitability across all segments and establishing EMIT as its fourth operating pillar via the Fredon deal.
Revenue up 31.4% to $4.3bn vs $4.19bn ests (1% beat), reflecting strong activity across all sectors plus a nine-month Fredon contribution
Underlying EBITA up 38.8% to $288.6m
Underlying NPAT up 43.6% to $182.7m vs $176.1m consensus NPAT (4% beat, though consensus is on a reported basis)
Underlying EBITA margin improved to 6.7% from 6.4% in FY25
Fully franked final dividend up 53% to 14.5cps
New EMIT segment contributed $684.3m revenue and $36.1m underlying EBITA, broadening exposure to health, defence, data centres and infrastructure
FY27 revenue guidance of $4.6bn to $4.8bn (midpoint $4.7bn) vs $4.58bn ests (3% beat), with ~85% already secured
FY27 guidance for underlying EBITA of $320m to $330m
Company page: NRW Holdings (NWH)
US national debt tops $40 trillion for the first time
[8:56 am] The US national debt has surpassed $40 trillion, having added its most recent trillion in just five months as deficits balloon and interest costs mount.
Total public debt outstanding hit $40.05 trillion as of 18 August, up from $19.4 trillion a decade ago and having more than doubled across the Trump and Biden presidencies
The pace is accelerating, with the last trillion added in about five months versus 192 years to reach the first, and July alone running roughly $14bn of new debt a day
Treasury reported a $432.3bn deficit in July, the highest monthly total since March 2021, with the year-to-date shortfall nearing $1.8bn and the annual deficit projected to hit $2.1 trillion by 30 September
Interest on the debt has reached nearly $1.2 trillion this year, now the largest budget line outside Social Security and Medicare
The fiscal strain is feeding markets, with Treasury yields at pre-GFC highs prompting Treasury to lift buybacks at the long end of the curve to support bonds
Fed's July hold masked broad appetite for a rate hike, minutes show
[8:55 am] Minutes from the Fed's July meeting revealed several officials favoured a rate hike and many warned tightening would be needed if inflation did not decline, though softer data since has eased that pressure.
FOMC voted 9-3 to hold the federal funds rate at 3.5% to 3.75%, the fifth straight meeting on hold following three cuts in late 2025
Dallas' Logan, Cleveland's Hammack and Minneapolis' Kashkari dissented in favour of a quarter-point hike, while non-voters Schmid (Kansas City) and Musalem (St. Louis) have since signalled they would have backed a hike
Most participants expected inflation to step down as tariff and energy effects wane, but many flagged it could prove more persistently elevated, with the outlook "highly uncertain" and clouded by the re-escalation of the Iran war
Chair Warsh drew criticism for failing to articulate a rationale for the hold at his press conference, pushing long-dated bond yields to a near two-decade high on doubts over the Fed's 2% commitment
Warsh floated cutting the number of annual policy meetings from eight to six, a significant operational shift, though no change will take effect this year
Source: Bloomberg
UAE cuts off all trade with Iran after alleged missile fire
[8:54 am] The UAE has imposed an indefinite trade embargo on Iran after accusing Tehran of firing two ballistic missiles at its waters, severing a lifeline that supplied roughly a third of Iranian imports.
UAE halted all trade, commercial exchanges and financial transactions "until further notice" after two ballistic missiles reportedly landed in its territorial waters, both causing no damage or casualties
Iran denies the attack, with Tehran calling the accusation "baseless" and suggesting a "false flag operation" amid its broader war with the US and Israel
The UAE supplied more than 30% of Iran's imports worth some $21bn in 2024 and acts as a critical re-export hub, giving Iran discreet access to third-country goods and a route to move money around sanctions
Escalation risk remains elevated, with US-Iran talks collapsed, the 60-day ceasefire window expired, and Strait of Hormuz traffic running below a tenth of pre-war levels
US and Canada near trade deal as Trump pauses 50% tariffs and eyes metals relief
[8:53 am] Washington delayed threatened 50% tariffs on Canadian goods after both sides signalled a tentative deal, with metals and auto duties set to be cut.
Trump paused planned 50% Section 338 tariffs on billions of dollars of Canadian goods for three days, less than two hours before they were due to take effect, citing a tentative deal still subject to finalisation
The proposed deal would halve tariffs on Canadian steel and aluminium to 25% and cut duties on the non-US content of Canadian autos to 15% from 25%, though rates may not apply across the board and derivative products could differ
Canada is understood to have committed to removing barriers on US autos, dairy and alcohol, with US spirits exports to Canada down 70% since 2025 amid provincial retail boycotts
Trump said the Keystone XL pipeline would be revived, having already permitted the Bridger Pipeline expansion to carry Canadian oil to Wyoming, with energy the largest US import from Canada at more than 4 million barrels a day
Markets moved sharply on the metals news, with Algoma Steel up as much as 24% in Toronto while US producers Nucor fell 8.9% and Century Aluminium dropped 11% on the prospect of cheaper Canadian competition
Bond traders seek shelter in short-dated debt
[8:52 am] Global markets are wrestling with rising long-dated yields and heavy AI-related borrowing, pushing investors toward safety even as US equities hold near records.
Short-dated bonds have become the consensus safe-haven trade, with an index of one to three-year maturities up 1% this year versus a 4% loss for bonds maturing in 10 years or more
US 30-year yields hit their highest since 2007, prompting Treasury Secretary Bessent to deploy debt buybacks in a sign of concern over the selloff
SK Hynix unveiled a $29bn buyback to ease worries about AI capex, sending its ADRs up 6.1% in premarket trade, though Asian chipmakers still fell with the Kospi sinking almost 6%
Alphabet sold its first Australian dollar bonds, paying just under 7% for longer-dated funding, its highest-ever cost and a sign of how much the tech borrowing binge is testing debt markets
Source: Bloomberg
What Treasury's buyback move means for bond markets
[8:48 am] An explainer on why the Trump Administration is intervening in the bond market and what is really at stake for investors.
What: Treasury is doubling the maximum size of its debt buybacks from $2bn to at least $4bn per operation, effectively becoming a larger buyer of older, longer-dated bonds to inject liquidity and pull yields lower at the long end of the curve. This operation runs Sept 9 through Nov 4, but Treasury has flagged it will provide "more information" on future buybacks on Nov 4, which commentary reads as a signal that further intervention is likely
Why: This is being read as the second notable bond market intervention by the Administration, after Trump cited the bond market when announcing his April 2025 "90-day tariff pause" and, notably, the 10-year yield now sits above the peak seen back then
Why it matters so much: The US government needs lower rates more than anyone, having spent $1.4trn on interest alone over the past 12 months, a figure projected to reach $1.7trn a year by November 2028 as borrowing costs have more than doubled since 2020
The threshold to watch: For debt servicing costs to simply stop rising, the 5-year yield needs to fall to around 3.25%, a roughly 110bps drop just to hold interest costs at $1.4trn, which is why the bond market is increasingly viewed as the key long-term fundamental
Treasury doubles debt buybacks to steady bond market
[8:46 am] The US Treasury will more than double its debt buybacks to ease pressure on longer-dated yields, sending yields lower and equity futures higher.
Buyback operation size to lift from a $2bn to "at least" $4bn maximum, targeting the 10-20yr and 20-30yr segment that has faced a buyers' strike since late June
Change runs from Sept 9 through Nov 4, positioned as a liquidity support measure rather than a debt paydown
10-year note closed down 5.7bps to 4.647% and the 30-year bond fell 9bps to 5.196% on the announcement
Evercore's Krishna Guha said the move could force near-term short-covering and deter investors from going max short, but changes nothing on fundamentals given heavy hyperscaler debt issuance and large deficits
Critics flagged the move as de facto yield curve control that could complicate the Fed's inflation fight, with commentary framing Bessent's motives as politically driven ahead of the election
Source: CNBC
Good morning!
[8:12 am] ASX 200 futures are up 27 pts (+0.30%). Here's what happened overnight:
Major US benchmarks broadly higher, snapped a three-day losing streak, though closed off best levels
S&P 500 (+0.21%), Dow (+0.22%), Nasdaq (+0.16%) and Russell 2000 (+0.50%)
Breadth was very strong, with the Equal-weight S&P 500 (+1.04%) surging on sizeable gains for sectors like Healthcare (+3.5%), Discretionary (+2.1%), Materials (+1.6%) and Staples (+0.8%)
US Treasury blindsided bond markets with a surprise decision to at least double buybacks of long-dated debt, dragging 30-year yields off two-decade highs
The relief landed on the same day total US public debt crossed $40 trillion for the first time, a milestone the street read as the reason Bessent felt compelled to act at all
Moderna surged 176% on the first successful late-stage trial of an mRNA cancer vaccine, while Fed minutes showed several officials wanted a rate rise as far back as July
Yes, a US$25bn market cap company added about ~$45bn in market cap