ASX 200 Live Today - Monday, 31st August
The S&P/ASX 200 is set to fall as Fed Chair Warsh's Jackson Hole speech weighed on Wall Street. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Monday, August 31. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Reporting season is heating up and we've got you covered. Our reporting season calendar has over 250 stocks plus earnings and dividend estimates.
ASX 200 flat as bank bounce offsets miner pullback
[2:12 pm] That's a wrap! The S&P/ASX 200 is down just 9 pts (-0.10%), a surprisingly flattish session after the hawkish takeaways from the Fed's annual Jackson Hole conference.
Financials now on a two-day win streak after falling 10% between 7-27 Aug
Energy also on a two-day streak, with Brent up 2.1% to US$90.1 a barrel on Monday after US and Iran exchanged strikes for the first time in roughly four weeks
A fairly defensive session, with Staples and Telcos catching a bid after recent reporting season volatility (Telcos down ~6.6% between 10-17 Aug to a near two-year low)
Materials tumbled on a higher US dollar, with the DXY up 0.55% overnight to 99.67
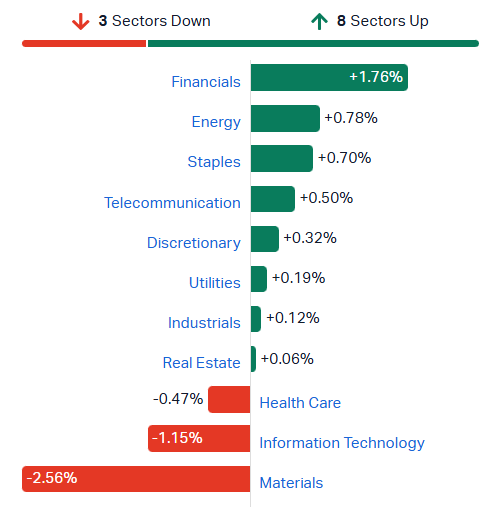
S&P/ASX 200 sectors (Source: Market Index)
China's factory gauge ticks up but stays in contraction
[1:11 pm] August manufacturing PMI beat expectations without escaping contraction, while construction activity slid to its weakest since the start of the pandemic, keeping pressure on Beijing to deliver more stimulus.
Manufacturing PMI of 49.8 in August from 49.2 in July, ahead of the 49.5 median estimate but a second month below the 50 line separating growth from contraction
Sixteen of 21 industries surveyed improved, with production and new orders in electrical machinery and equipment above 53%, while chemical raw materials sat below 50
Non-manufacturing PMI of 49.0 missed expectations, with the construction gauge falling to 46.9, the lowest since the pandemic began, which the statistics bureau attributed partly to heavy rain and typhoons
Goldman Sachs estimates growth of about 4% year-on-year at the start of the third quarter, down from 4.3% and below Beijing's 4.5-5% target, with chief China economist Hui Shan noting the slowdown is demand-driven and has spread beyond previously resilient areas
Policy support expectations building, with analysts generally expecting the PBOC to hold rates but seeing a reserve requirement ratio cut as more likely later this year
ANZ's Raymond Yeung said "growth momentum is fading" and that markets are waiting on policymakers to announce large stimulus
Source: Bloomberg
Macquarie flags capital management upside at St Barbara after surprise special dividend
[1:08 pm] The broker kept its $0.96 target price, noting the Simberi sell-down muddied the reported figures while the special dividend and potential buy-back caught the market off guard.
"The market reaction to the result and capital management initiatives is unsurprising given the short interest (4.8%) and low trading multiple. We see further options for re-rating upon clarity around the permitting process for 15-Mile and updated guidance," noted the analysts.
Reported NPAT of $490m was 1% ahead of Macquarie, driven primarily by the gain on the Simberi sell-down
Underlying NPAT loss of $29m against a $13m loss modelled by the broker, with unrestricted cash of $393m and total cash of $475m
Special dividend of 5cps declared alongside a potential 100m share buy-back, to be confirmed after the refreshed 15-Mile PFS lands in late September
FY27 guidance expected in Septemberwith the PFS refresh, against consensus forecasts of 68koz in FY27, 76koz in FY28 and 59koz in FY29, driven by the Touquoy restart around January 2027 and St Barbara's share of Simberi
EPS changes of 10% in FY27 and 141% in FY28, then broadly flat thereafter, reflecting minor shifts in the production profile between years
Company page: St Barbara (SBM)
Macquarie backs PEXA to 'win the war' despite guidance letdown
[1:06 pm] The broker keeps its Outperform rating but trims its target price to $13.90 from $15.15, arguing FY27 guidance is deliberately conservative and the IPART price cut is unlikely to land in full.
FY26 EPS of 14.9cps came in 10.8% above Macquarie and 11.2% above consensus, supported by robust Australian revenues and strong margins
Australian EBITDA margin of 55.8% against Macquarie's 55.5%, which the broker reads as evidence of cost control
UK revenue of $61.2m was 13% below Macquarie's $70m and 9% below consensus, though EBITDA losses of $41m were narrower than the $44m modelled and lower capex left UK cash flows at negative $58m versus negative $63m expected
FY27 underlying NPAT guidance of $5-20m disappointed against Macquarie's $24.6m and consensus of $24.8m, with the broker attributing the caution to weak property volumes, New Zealand pilot headwinds and the cost of signing a second Tier 1 lender before revenue arrives
Draft IPART cuts of around $70m could shrink, with the broker pointing to roughly $10m of relief from weaker volumes, about $18m of AML/CTF revenue based on a survey of almost 200 conveyancers and agents, growing ancillary revenues and flaws PEXA has identified in IPART's methodology
EPS cut 49% in FY27, 61% in FY28 and 23% in FY29, with downgrades easing to about 5% from FY30, and catalysts flagged as the IPART final report, the ARNECC conclusion, further Tier 1 lender commitments and third quarter volumes
Pexa shares tumbled 17.4% last Friday to $6.68, and up 10.7% today to $7.40.
Company page: PEXA Group (PXA)
Bond investors doubt Warsh will follow through on a September hike
[12:23 pm] Managers at ABN AMRO and Brandywine say the Fed chair's hawkish Jackson Hole message counts for little until he actually moves, having held rates steady twice already this year.
Swaps traders now price a roughly 60% chance of a hike at the mid-September meeting, with two-year Treasury yields surging the most in over two months after Friday's speech
ABN AMRO and Brandywine are both unconvinced, steering clear of and underweight long-dated Treasuries respectively on the risk of another hold
TD Securities has a hold as its base case, while DWS warns the market is doing the Fed's job and overpricing hikes the data does not support
Credibility concerns have already driven long-maturity yields to the highest levels in about two decades after Warsh stood pat in both June and July
Goldman warns a September hold without a clear rationale would risk a repeat of the July curve steepening
Friday's payrolls report is the pivotal test, with Warsh saying he is more concerned about price stability than employment and that better recent inflation prints do not yet form a trend
Source: Bloomberg
Top Aussie dollar forecasters say the rally is done
[12:20 pm] Some of the currency's most accurate forecasters say the market has pushed RBA rate-hike expectations too far and the Aussie's two-month run is close to exhausted.
SB1 Markets sees the Aussie falling as much as 3.7% by year-end, taking it to roughly 69 US cents from Friday's close of 71.64
Santander and Danske both target 70 US cents, with Danske flagging that level could be reached as early as December
The bearish calls follow a gain of more than 3.5% since the start of July, driven by sticky inflation and bets on an RBA hike as soon as next month
Wednesday's 2Q GDP print shapes as the next test, with Santander and Danske both expecting the RBA to stay on hold in September and any hike pushed into 4Q
US dollar weakness has been a key tailwind, though that support may prove less durable after Fed chair Kevin Warsh's hawkish tone at Jackson Hole
Technicals look stretched and seasonality favours a pullback, with the Aussie down an average 1% in September over the past five years
Source: Bloomberg
ASX gold miners broadly lower this morning
[11:29 am] Gold prices fell 3% on Friday to US$4,453.67/oz after Fed chair Warsh's hawkish comments at Jackson Hole, saying that inflation remains too high, and are trading around breakeven today. That has left ASX gold miners broadly lower this morning.
Ticker | Company | % Chg | Price | 1 week | Year to date |
|---|---|---|---|---|---|
EMR | Emerald Resources | -1.8% | $6.98 | -2.2% | 11.1% |
BC8 | Black Cat Syndicate | -2.5% | $1.10 | -5.4% | -9.3% |
RMS | Ramelius Resources | -2.5% | $3.86 | -1.5% | -5.6% |
NEM | Newmont | -2.9% | $177.53 | -3.1% | 18.3% |
BGL | Bellevue Gold | -3.0% | $1.61 | -5.6% | -4.7% |
AMI | Aurelia Metals | -3.2% | $0.45 | 9.8% | 83.7% |
OBM | Ora Banda Mining | -3.3% | $1.54 | -5.7% | 0.5% |
VAU | Vault Minerals | -3.5% | $6.69 | -2.3% | 23.0% |
RSG | Resolute Mining | -3.8% | $1.38 | 0.7% | 12.7% |
MEK | Meeka Metals | -3.8% | $0.13 | -7.4% | -53.7% |
CMM | Capricorn Metals | -4.2% | $16.51 | -6.4% | 17.9% |
RRL | Regis Resources | -4.2% | $8.25 | 0.0% | 9.7% |
GMD | Genesis Minerals | -4.3% | $8.20 | -2.4% | 14.5% |
NST | Northern Star Resources | -4.4% | $23.68 | -3.3% | -3.6% |
EVN | Evolution Mining | -4.5% | $14.96 | -3.5% | 19.0% |
WGX | Westgold Resources | -4.9% | $6.34 | -0.9% | 0.6% |
PRU | Perseus Mining | -5.0% | $6.40 | 3.8% | 16.1% |
ALK | Alkane Resources | -5.1% | $1.83 | 0.1% | 37.4% |
CYL | Catalyst Metals | -5.1% | $6.49 | -6.8% | -12.1% |
SBM | St. Barbara | -6.0% | $0.75 | 9.0% | 30.8% |
PNR | Pantoro Gold | -7.8% | $2.66 | -3.1% | -45.8% |
Banks pushing higher in early trade
[11:05 am] Bank stocks are higher across the board, with Westpac and CBA leading the majors and every name in the list also holding a gain over the past week.
Ticker | Company | % Chg | Price | 1 week | Year to date |
|---|---|---|---|---|---|
WBC | Westpac | 1.8% | $34.52 | 2.7% | -10.4% |
CBA | CBA | 1.7% | $159.98 | 2.8% | -0.4% |
NAB | NAB | 1.6% | $38.89 | 2.3% | -8.0% |
ANZ | ANZ | 1.4% | $37.26 | 1.5% | 2.2% |
BOQ | Bank Of Queensland | 1.2% | $6.51 | 2.8% | -0.8% |
BEN | Bendigo & Adelaide Bank | 1.0% | $10.69 | 1.6% | 0.9% |
MQG | Macquarie | 0.6% | $253.35 | 1.0% | 24.8% |
JDO | Judo Capital | 0.2% | $1.02 | 3.2% | -42.9% |
Top ASX 200 gainers and losers
[10:28 am] Pexa bounces after its FY26 result last Friday, while insurers, banks and energy stocks catch a bid. Meanwhile, gold and copper miners open broadly lower after a pullback for commodity prices last overnight.
Ticker | Company | % Chg | Price |
|---|---|---|---|
PXA | Pexa Group | 7.34% | $7.17 |
DMP | Domino's Pizza | 2.99% | $20.69 |
DBI | Dalrymple Bay Infrastructure | 2.57% | $5.18 |
LTR | Liontown | 2.09% | $1.22 |
RMD | Resmed | 2.05% | $33.41 |
SUN | Suncorp Group | 1.90% | $18.79 |
BPT | Beach Energy | 1.74% | $0.88 |
WBC | Westpac | 1.74% | $34.49 |
WHC | Whitehaven Coal | 1.68% | $8.48 |
CBA | Commonwealth Bank | 1.54% | $159.67 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
NXG | Nexgen Energy | -6.19% | $14.55 |
PNR | Pantoro Gold | -5.73% | $2.72 |
PDI | Predictive Discovery | -5.59% | $4.22 |
SLX | Silex Systems | -5.03% | $5.66 |
DYL | Deep Yellow | -4.66% | $1.64 |
WGX | Westgold Resources | -4.35% | $6.37 |
NST | Northern Star Resources | -4.24% | $23.73 |
EVN | Evolution Mining | -4.15% | $15.02 |
FFM | Firefly Metals | -3.94% | $1.83 |
RRL | Regis Resources | -3.83% | $8.28 |
Kingsgate declares a second 10c dividend on the back of record earnings
[9:37 am] The Chatree operator has followed its FY26 result with another unfranked distribution, taking calendar 2026 returns to roughly $53.2 million.
Final dividend of 10cps unfranked, with an ex-dividend date of 20 October, record date of 21 October and payment on 11 November 2026
Approx 1.88% yield based on last Friday's close of $5.31
Total dividends of 20cps across calendar 2026, including the 10cps interim paid in April, worth approximately $53.2m or a trailing yield of 3.7% based on last Friday's close
Record NPAT of $277.9m for FY26, so the full-year payout represents a modest fraction of earnings
Higher gold and silver prices and continued strong cash generation at Chatree underpinned the result and the Board's decision
Balance sheet flexibility retained for ongoing operations and growth, with the Nueva Esperanza silver-gold project in Chile still being advanced
Company page: Kingsgate Consolidated (KCN)
Black Cat swings to profit as Paulsens repays itself inside a year
[9:20 am] The Paulsens restart carried a maiden full year of meaningful production, with the acquisition and refurbishment spend recouped from cash flow. No consensus estimates are available, so comparisons are against the prior corresponding period.
Revenue up 903% to $374m
Total gold production up 132% to 90,833oz, including 24,537oz of third party ounces, with own production up 97% to 66,296oz
Gold sold up 147% to 65,951oz
NPAT of $86m versus a $26m loss
EPS of 12.0c versus a 4.6c loss
Operating cash flow of $225m versus an outflow of $13m, with the $106m invested in acquiring and restarting Paulsens fully recouped during the year
Cash, bullion and investments up 87% to $105m
Kal East hit a milestone in the fourth quarter, processing 100% company-owned ore feed through Lakewood
Company page: Black Cat Syndicate (BC8)
BetMakers triples EBITDA into a Tabcorp takeover
[9:19 am] Cost discipline did most of the work in FY26, though with a scheme of arrangement in place the result matters more as a valuation datapoint than a trading update.
Revenue up 8.8% to $92.6m, or 11.2% on a constant currency basis
Adjusted gross margin of 66.9%, up from 64.1%, or 65.5% unadjusted after a $1.3m inventory write-off
Adjusted EBITDA up 205.1% to $14.1m, with margin expanding to 15.2% from 5.5%
Operating expenses down to $49.4m from $52.5m, falling to 53.3% of revenue from 61.7% on FY25 restructuring benefits
Tabcorp scheme offers 24c cash per share, with shareholders able to elect 25%, 50%, 75% or 100% in Tabcorp scrip, capped in aggregate at 25% of total consideration and subject to scale-back
Board unanimously recommends the scheme absent a superior proposal, with directors holding around 10% of shares on issue intending to vote in favour
No FY27 guidance provided, though management flagged a strong start with 1H FY27 expected to build on the upgraded technology and expanded product suite
Company page: BetMakers Technology Group (BET)
Monash IVF beats trimmed ests but lands short of its own guidance
[9:17 am] A year of two halves for the fertility group, with first-half volume and share losses dragging earnings down despite a stronger second half. Only Bell Potter's numbers are available for comparison, so those are used as ests below.
Revenue down 0.9% to $269.5m vs $267.7m ests (0.7% beat)
Underlying EBITDA down 19.5% to $53.4m vs $51.4m ests (3.9% beat), with margin of 19.8%
Underlying NPAT down 41.2% to $16.1m vs $15.1m ests (6.6% beat), still below the June guidance range of $17m to $18m and including a $1.4m after-tax prepaid asset write-off
Reported NPAT of $8.3m
Total FY26 dividends of 2.5cps vs 2.3cps ests (8.7% beat) fully franked at a 60% payout, including a final of 1.3cps
Domestic stimulated cycle volumes improved from down 11.7% in 1H26 to down 1.6% in 2H26, with market share up 1.2 points to 20.2%
International revenue up 15% to $21.2m and EBITDA up 10% to $4.2m, with Johor Bahru revenue up 73%
Net debt of $101.2m at 1.9x leverage, with the facility lifted to $130m and extended three years
FY27 capex to fall about 50%, with no earnings guidance provided beyond an expectation that performance strengthens through the year
Company page: Monash IVF Group (MVF)
Liontown swings to a maiden profit but misses on earnings
[9:10 am] The lithium price recovery lifted the top line into line, but costs meant very little of it reached EBITDA or underlying earnings. Only Macquarie's numbers are available for comparison, so those are used as ests below.
Revenue up 115% to $639m vs $641m ests (in line), on a 35% lift in concentrate tonnes sold and a 75% increase in the SC6 equivalent realised price to US$1,379/dmt
Sales of 382kdmt vs 382kt ests (in line) and production up 33% to 392kdmt, both at a weighted average grade of 5.1% Li₂O, with FY26 guidance delivered
Underlying EBITDA up 633% to $147m vs $215m ests (31.6% miss)
Underlying NPAT of $14m vs $23m ests (39.1% miss)
Reported NPAT of $93m versus ests of an $81m loss, with $79m of exceptional items including a $113m deferred tax asset recognition
Unit operating cost up 23% to $984/dmt
Operating cash flow of $182m vs $297m ests (38.7% miss), with a year end cash balance of $561m, up 260%, after current borrowings fell $312m to $53m on conversion of the LG Energy Solution notes
Underground ramp-up on track for 2.8Mtpa by the end of FY27, with FID on the Kathleen Valley expansion due next month
Company page: Liontown Resources (LTR)
Carma doubles gross profit and guides to another 80% revenue year
[9:06 am] The online used car retailer scaled hard in its first full year as a listed company, though the EBITDA loss widened and profitability remains a calendar 2027 story. No consensus estimates are available, so comparisons are against the prior corresponding period.
Revenue up 59% to $113.8m, with retail unit growth outpacing revenue as average selling price fell 6% to $28,900 on an older vehicle mix
Total units up 86% to 5,416, split between 3,156 retail and 2,260 wholesale, the latter up 180%
Gross profit up 102% to $10.5m, with margin expanding 196 basis points to 9.2%
Pro Forma EBITDA loss widened 8% to $30.2m, though the margin improved 1,248 basis points to (26.5%) as opex fell to 35.4% of revenue from 42.9%
Statutory loss after tax of $49.6m including $13.3m of non-recurring items, leaving a Pro Forma loss after tax of $36.7m
FY27 revenue growth guided at over 80%, with retail deliveries booked from 1 July to 31 August already up 120% on the same period last year
Available funding of $41.3m at year end, including $16.0m cash and $25.3m undrawn on the bailment facility, against a cash burn of $46.7m in FY26
Breakeven flagged at 45-60 retail units per day on average, which Carma expects to reach before the end of calendar 2027
Company page: Carma (CMA)
MGX and Tanami commit $38m to a decline into Groundrush
[8:56 am] The Central Tanami Project joint venture has signed Macmahon to build an underground decline at Groundrush, unlocking the drilling platforms needed to firm up resources ahead of a 2027 development decision.
$38m contract with Macmahon Underground covering portal and vent establishment plus the initial 3.5km of decline to about 350 metres depth over a 14-month period
33,000 metres of infill drilling planned from underground platforms, targeting conversion of more than 400,000 ounces of Inferred resources into the Indicated category for mine design
Drilling only starts late in the 14-month construction window, so the resource upgrade is a CY27 event rather than a near-term catalyst
CTPJV resource stands at 31.0Mt at 2.8 g/t for 2.8Moz of contained gold, with Groundrush accounting for 11.0Mt at 3.3 g/t for 1.2Moz
Surface works already underway with Macmahon mobilising to site in September for in-pit portal construction
Company page: MGX Resources (MGX)
Genus gets the green light on a $750m Tasmanian transmission build
[8:56 am] TasNetworks has issued Notice to Proceed on the construction phase of Stage 1 of its North West Transmission Developments project, converting Genus's early works into a multi-year contract.
Total contract value of circa $750m including the previously announced early contractor involvement and early works agreements, which were valued at $122m
All conditions precedent met, with construction to commence immediately and completion scheduled for 2029, giving Genus a revenue tail across four financial years
The $628m of incremental work beyond the ECI and EWA phase is new to the order book, materially lifting Genus's contracted pipeline
Long-lead item procurement was already covered under the early works phase, reducing supply chain risk heading into the main build
Company page: GenusPlus Group (GNP)
Strike lands Hancock as its West Erregulla partner and funder
[8:55 am] Strike Energy has picked Gina Rinehart's Hancock Energy to process its share of West Erregulla gas and secured up to $60 million of new funding, clearing the two biggest hurdles to developing the field.
Hancock's Belisama facility selected as the preferred processing pathway with a binding fixed capacity charge, and upstream operatorship of L25/L26 to transition to Hancock once conditions are met
Up to $30m commercial loan from Hancock to fund Strike's share of pre-FID work, with repayments aligned to cash generation after first gas and second ranking security behind Macquarie
Macquarie has waived drawdown conditions and lifted the available tranche from $23m to $30m, releasing cash previously only accessible at FID, repayable in 2029 with no amortisation
Upstream FID targeted in FY28 with first gas in mid-CY29, so West Erregulla remains a long-dated story rather than a near-term earnings event
SEPP practical completion now forecast for 31 October 2026 with approval to generate late Q4 CY26, and capacity credit payments only start once AEMO testing is done
Walyering is producing around 13 TJ/d with both compressors brought online from 29 August and a ramp toward 20 TJ/d planned into September
Company page: Strike Energy (STX)
Trump swaps Venezuelan barrels for Iranian ones as the blockade bites
[8:48 am] Six months into the Iran war, Washington is squeezing Tehran's exports to a trickle while claiming control of a vast new reserve base in Venezuela, all with pump prices climbing into the midterms.
Trump announced a deal giving the US majority control of more than 65 billion barrels of Venezuelan reserves at "no cost" to taxpayers, negotiated with interim President Delcy Rodriguez nine months after the operation that captured Nicolás Maduro
Venezuela holds an estimated 303 billion barrels, roughly 17% of global supply, but produces only about 1% of the world's oil because of dilapidated infrastructure, so any volume response is a long-dated capex story rather than a near-term supply fix
Iranian crude loadings have collapsed to about 260,000 bpd in August, down more than 80% from 1.7m bpd a year ago and down about 70% from July, with US Central Command redirecting 82 commercial vessels and boarding two
Hormuz throughput is running at 5-6m bpd on Kpler's tracking, around a third of the 15m bpd before the war, with Trump's claim of 10m bpd well above independent estimates
Washington ramps up the pressure on Beijing while both sides keep the summit on
[8:43 am] Tariff threats, Iran sanctions and chip rivalry are all escalating at once, yet officials on both sides are still working towards Xi Jinping's state visit to Washington next month.
US is weighing a 7.5% tariff on Chinese goods over alleged excess manufacturing capacity, which would revive Trump's protectionist agenda after the Supreme Court struck down his earlier import taxes and would take tariffs to a level Beijing says was agreed in previous talks
Beijing's response has been measured, with the Commerce Ministry saying it reserves "the right to take all necessary measures" but stopping short of naming any, while Foreign Minister Wang Yi pressed the US to get relations back on the "right track"
Trump hinted he could sanction Chinese banks after Treasury Secretary Scott Bessent warned that lenders in the ecosystem turning Iranian oil into money "will be targeted", though Monday's measures swept up Chinese and Hong Kong businesses and left major financial institutions untouched
Currency markets are treating the threats as noise, with the onshore yuan holding in its tightest weekly range since early 2016 near 6.72, up almost 4% this year, and offshore implied volatility near 2015 lows
Markets swing to pricing a Fed hike after Warsh's Jackson Hole debut
[8:42 am] Kevin Warsh stopped short of promising anything, but traders read his first Jackson Hole speech as a hawkish turn and repriced the September meeting accordingly.
Rate hike odds for the September 15-16 meeting jumped to roughly 56-60% from about a third before the speech, with the two-year Treasury yield up nearly 8 basis points to 4.31%, its highest since late July
Gold fell as much as 3.2% to $4,515.30/oz for December delivery, its worst session in six weeks, with silver down 4.1% to $67.34/oz, though both are still up double digits for August
Former Fed vice chair Alan Blinder said Warsh sounded "like a man who was rationalising raising interest rates" and expects a quarter-point hike in September
Warsh dazes algos by mentioning 'hike' three times
[8:40 am] Warsh may have tricked algorithms designed to sell or short the market on any hawkish rhetoric. He mentioned the word 'hike' three times in the first five paragraphs of his speech.
Fourth paragraph: "As I learned years ago, you can take two different kinds of hikes on the trails around Jackson Hole. I can sum up my hikes with former Vice Chairman Don Kohn in two words: I survived. These steely marathon death marches revealed a side of Don I wasn't ready for."
Fifth paragraph: "There's another kind of hike—one I associate with Chairman Ben Bernanke, my old colleague. With Ben, it's a much more leisurely pace, an easy stroll along the wandering trails at the Rockefeller Preserve."
Warsh keeps the focus on prices and retires forward guidance
[8:39 am] New Fed Chairman Kevin Warsh used his first Jackson Hole address to push back on rate cut expectations, arguing inflation remains the binding constraint and that financial conditions are anything but tight.
On the inflation problem: "Inflation is running above our 2 percent target. So the Fed's predominant focus right now should be on prices", with 12-month PCE at 3.7% and the six-month run rate at 4.1%
On the better summer prints: "while this summer's PCE and CPI readings were better than expected, they do not tell me that underlying trends have meaningfully improved"
On the bar for easing: "We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do"
On financial conditions: "Credit and loan markets are showing few signs of policy restraint" and "I would be hard pressed to describe broad financial conditions as restrictive", with credit spreads near historical lows
On forward guidance: the practice "has overstayed its welcome" and quasi-commitments on rates "inhibit our own freedom to make the right calls when it's time to decide"
On the AI capex cycle: "More than half of the cap-ex growth this year can likely be ascribed to the buildout related to AI", with investment in equipment and intangibles up around 9% over four quarters
Source: Federal Reserve
Good morning!
[8:26 am] ASX 200 futures are down 12 pts (-0.39%). Here's what happened overnight:
Wall Street faded a post-Jackson Hole pop to finish lower on Friday, though all three major benchmarks still booked a winning week
S&P 500 (-0.25%), Equal-weight S&P 500 (-0.34%), Nasdaq (-0.52%), Dow (-0.02%) and Russell 2000 (-0.139%)
US weekly recap: S&P 500 (+0.49%), Nasdaq (+0.85%), Dow (+0.53%) and Russell 2000 (-1.51%)
Kevin Warsh's debut Jackson Hole keynote pushed September rate-hike odds to roughly 57% from 35%, lifting the front end of the curve and knocking gold off its highs
Trump announced a deal handing the US majority control of more than 65 billion barrels of Venezuelan oil reserves, the most consequential energy headline of the weekend