ASX 200 Live Today - Monday, 26th October
The S&P/ASX 200 is set to fall after Brent spiked to a six-month high of US$117 on Middle East supply risks. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Monday, October 26. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Janus Electric signs Texas pilot MOU with ConGlobal
[9:48 am] Janus Electric, which converts heavy diesel trucks to electric using swappable batteries, has struck a non-binding deal that could take it beyond California and across a 31-depot US network.
The MOU with ConGlobal, a major North American operator of intermodal and depot terminals, targets an initial 20-truck pilot at its Fort Worth logistics centre in Texas
Subject to the pilot and definitive agreements, the parties intend to explore a phased rollout across ConGlobal’s 31 US depots
ConGlobal mechanics would perform the conversions and servicing, while ConGlobal would manufacture containerised battery charge-and-swap stations to Janus’ specifications
Janus would contract directly with fleet operators for conversion kits, batteries and services
The MOU is non-binding with confidential terms, and runs for 90 days or until superseded by a definitive agreement
CEO Ben Hutt said the deal offers a US footprint “through an experienced operator with an extensive US network, rather than building our own facilities at every location”
Company page: Janus Electric (JNS)
Valiant on track for Comet restart with $62.5m in the bank
[9:47 am] Valiant Gold, a WA gold developer restarting the Comet underground mine near Westgold’s processing hubs, remains on track for first production in H2 FY27.
The Comet Restart Study is due before the end of Q2 FY27, with appointment of an underground drilling contractor nearing completion
Dewatering reached the 1270 Level after quarter end, about 170m below surface, with the site power station due to be commissioned by the end of October
Ore will be processed through Westgold’s Bluebird and Tuckabianna mills under an ore purchase agreement, offering a lower capital pathway to production
South Emu-Triton drilling returned 7.0m @ 4.57g/t Au from 861m, with mineralisation extending well below the existing 224koz resource
About 8,000m of drilling is underway at Boomerang to firm up the 367koz resource and assess open pit and underground options, with first assays under review
Cash and term deposits of $62.5m at the end of the quarter vs. market cap of $69m
Company page: Valiant Gold (VAL)
Brokers warm to REA’s AI strategy but stay neutral
[9:43 am] UBS and Macquarie came away from REA Group’s Investor Day more confident in its AI strategy, though both kept Neutral ratings given near-term listings and earnings risks.
REA reiterated its through-the-cycle aspirations for double-digit revenue and EBITDA growth, alongside maximising shareholder returns
REA holds a 25% share of a $6.7bn Australian addressable market, including 35% of residential core and 13% of its domestic growth engines, according to Macquarie
Likely to List, a seller-lead product launching in 2027, is a key watch for FY28 yield upside, though UBS notes monetising seller leads has been difficult in the past
UBS flagged that REA’s take rate of the average house price only rose to 22bps in FY26 from 20bps in FY20, and forecasts it lifting to 26bps by FY30 on a 10% yield CAGR
Macquarie trimmed EPS by 2% in FY27 and 1% in FY28, holding its price target at $170
Macquarie said “We are however more constructive with REA as a likely AI-winner medium-term, having growth options within current and new TAMs, and with financial flexibility”
Company page: REA Group (REA)
UBS sees no lithium rebound before year-end
[9:32 am] UBS lithium expert Sky Han says battery makers are working through excess inventory, with weakness likely to persist through the end of the year.
Spodumene prices have fallen more than 60% to US$1,260/t since mid-May highs, with chemical prices down over 40% to US$13.5k/t and lithium equities down 50–75%
Battery makers are destocking, similar to the five-month cycle from late 2022 into 2023, as falling project returns slow battery energy storage system (BESS) installations
Han sees cost support at RMB80k/t, a potential floor for prices into year-end, vs GFEX lithium carbonate futures at about RMB98k/t
Demand growth is forecast to ease to 19% in 2027 from 26% in 2026, and to the low teens into the early 2030s
Supply is forecast to grow 25% or 445kt in 2027, led by Africa (more than 160kt), China (145kt) and Australia (80kt), though this was modelled before prices rolled over
Current prices are pressuring funding for brownfield expansions and the profitability of swing producers that have re-entered the market
BlueScope lifts 1H earnings guidance on stronger US steel spreads
[9:29 am] BlueScope’s first-half earnings are set to land well ahead of Macquarie’s forecasts, with wider US steel spreads and resilient Australian demand lifting its biggest divisions.
1H FY27 underlying EBIT guidance lifted to approaching $1.1bn from $860–960m, vs $955m ests (15% beat)
North Star approaching three-quarters higher, with benchmark US mini-mill spreads now around US$810/t vs US$750/t assumed in prior guidance
Buildings and Coated Products North America around 50% higher, on stronger Steelscape volumes and prices
North America is expected to deliver earnings around two-thirds higher than 2H FY26
Australian Steel Products is expected to deliver earnings approaching double 2H FY26, on stronger domestic volumes and higher value-added sales
CEO Tania Archibald said the US “continues to demonstrate why it is such an attractive place to make and sell steel”
BlueScope shares are up 34% year-to-date, though most of that move came during the failed takeover from SGH/Steel Dynamics earlier this year. Their final offer, made on 17–18 February, was worth $32.35 cash per share, or $34.00 before deducting declared dividends. BlueScope closed at $32.36 on Friday, right around where that bid was pitched.
Company page: BlueScope Steel (BSL)
Cochlear reaffirms FY27 guidance at AGM
[9:26 am] Cochlear held its FY27 profit guidance after a challenging FY26, with CEO Dig Howitt pointing to its fully implantable device as a potential driver of new demand.
FY27 underlying NPAT guidance of $330–350m reaffirmed, with the $340m midpoint implying 6% growth on FY26’s $322m
Howitt said slower growth in several developed markets was “more pronounced, and persisted for longer” than expected in FY26
The Nexa implant made up more than 95% of developed market implant sales by June, with an average price increase of 3%
Recruitment for pivotal studies of the totally implantable cochlear implant is complete, filling significantly faster than past implant studies
Fewer than 5% of eligible adults receive a cochlear implant, and Howitt said an invisible device could remove a key barrier for some candidates
Company page: Cochlear (COH)
Biome extends lead as Australia’s top pharmacy probiotic
[9:25 am] Biome Australia, which sells its Activated Probiotics range through pharmacies and health practitioners, posted its strongest quarter of pharmacy demand on record as it shifts manufacturing onshore.
Cash receipts up 10% to $6.5m from $5.9m in Q4 FY26
Biome Daily extended its lead as Australia’s number one pharmacy probiotic by units and dollar value, with record wholesaler sell-through in the quarter, according to IQVIA
Net operating cash inflow of $100k, with manufacturing and operating payments down 17% on the pcp to $2.9m
Closing cash of $3.4m, down $170k on June, with total available funding of $6.5m and drawn debt unchanged at $1.9m
Australian-made product from Specialty Probiotics Australia is due on pharmacy shelves from November, which Biome expects to lower cost of goods and remove currency and freight exposure
Exclusive China cross-border e-commerce launch with H&S Global is planned within FY27, subject to signing a master distribution agreement
Company page: Biome Australia (BIO)
Beforepay posts record revenue as cash profit jumps 58%
[9:19 am] Beforepay, which offers pay advances and personal loans to Australian workers, opened FY27 with record revenue as larger average advances and interest on its Pay Advance product lifted earnings.
Revenue up 45% to a record $16.5m, driven by interest on Pay Advance and a larger average advance size
Pay Advances up 15% to a record $257.7m
Total advances up 17% to a record $265m, with the average advance size also up 17% to $524
Cash NPAT up 58% to $5.7m
Personal Loans advances of $7.0m, in line with the June quarter
Personal Loans net bad debts of 1.59% were helped by recoveries and Q4 provision write backs, which the company expects to normalise in future quarters
The stock is down 47% year-to-date, but some fairly interesting numbers for a ~$66m market cap company.
Company page: Beforepay Group (B4P)
Capricorn’s Lexington keeps delivering high-grade hits
[9:13 am] Capricorn Metals continues to hit high-grade gold well beyond its current mine designs at Mt Gibson, building the case for a maiden underground resource at Lexington later this quarter.
Top Lexington intercepts include 6.0m @ 57.38g/t Au from 616m, 7.0m @ 40.01g/t Au from 401m and 29.5m @ 6.65g/t Au from 760.5m
Mineralisation sits outside the Orion South underground stope designs and well below reserve pit designs, and remains open along strike and at depth
Hornet drilling hit 3.0m @ 89.88g/t Au from 120m, beneath the current reserve pit outline
Orion South returned 21.83m @ 9.54g/t Au from 371m, with more than 1,600m of prospective strike now defined
Executive Chairman Mark Clark said the results are “an important step towards validating our Range 500 growth strategy”
Company page: Capricorn Metals (CMM)
NextDC chair to step down and CEO forgoes incentives after M3 delay
[9:12] NextDC is overhauling its board and scrapping pay proposals in a bid to win back investors after last week’s M3 Melbourne power delay forced a guidance downgrade.
Chairman Douglas Flynn will retire once a successor is in place, with Spencer Stuart’s search widened to find an additional independent non-executive director
Two new directors are expected to be appointed in the first quarter of 2027, ideally with data centre, energy, infrastructure or capital management experience
Director Stuart Davis will stand for re-election at the 20 November AGM but intends to step down once the new directors are in place
A resolution to lift the director fee pool to $2.5m from $2.2m has been withdrawn, and incumbent non-executive directors will take an immediate 10% fee cut
CEO Craig Scroggie will forgo his FY27 short and long-term incentives, with the resolution to grant him about 292,000 rights withdrawn
Flynn said the board shares “the disappointment of investors resulting from our revised FY27 guidance and share price performance”
For context, NextDC introduced a $150m Growth Incentive Plan in February 2025 to retain and reward senior executives, with CEO Craig Scroggie eligible for up to $50m of the pool. Vesting is tied to total shareholder return over five years from a baseline share price of $14.14. The minimum threshold requires the stock to rise about 80%, while full vesting requires annual TSR of 17.5% compounded, or a 124% gain to roughly $31.67. After the recent selloff, the shares now need to rally around 390% just to reach the minimum, and about 510% for the maximum. So Scroggie isn't really "forgoing" the incentives, it's just that given the current state of play, the share price probably isn't going to 5x in the next four years!
Company page: NEXTDC (NXT)
Greatland keeps costs in check as Havieron construction begins
[9:09 am] Greatland delivered a clean first quarter of FY27, with production in line with UBS and costs slightly better, while construction at its flagship Havieron project got underway.
Gold production of 70,131oz vs 70,000oz ests (in line)
Net revenue of $485m from gold sales of 71,901oz at an average realised price of $5,980/oz
AISC of $2,925/oz vs $2,969/oz ests (1% lower)
Closing cash rose to $1,314m from $1,289m at 30 June with no debt, after $100m of tax instalments covering five months
FY27 guidance of 260–300koz at an AISC of $2,900–3,330/oz reaffirmed
Havieron construction started in September after final approvals, with $45.2m of development capex spent in the quarter
Company page: Greatland Resources (GGP)
Ramelius costs overshoot as rain stalls Penny haulage
[9:08 am] Ramelius’ September quarter costs came in well above UBS forecasts, though the miner expects stranded ounces to flow through next quarter and kept full-year guidance intact.
Gold production of 48,839oz (pre-reported)
AISC of $2,656/oz vs $2,408/oz ests (10% higher)
Weather disruptions to Penny haulage left 29kt of ore at 4.52g/t (4,202oz) on stockpile, to be processed in the December quarter
Cash and gold rose to $768m from $650m at June, including $210m from the Edna May sale, with $45–55m of tax on the sale due in December
Underlying free cash flow of $62m, after $53m of growth capex and $23m of exploration
FY27 guidance of 205–225koz at an AISC of $2,150–2,350/oz reaffirmed, with production planned to rise each quarter on higher grades at Dalgaranga and Cue
Buybacks of $15m in the quarter took the total to $156m, or 62% of the $250m program
Company page: Ramelius Resources (RMS)
Elevra banks US$71m from Ewoyaa exit
[9:03 am] Elevra Lithium has walked away from Ghana with cash in hand and no further development funding obligations, sharpening its focus on North America.
Elevra completed the sale of its entire Ewoyaa interest to Chinese battery materials group Huayou Cobalt for US$71m cash before fees and taxes
The deal includes Elevra’s spodumene offtake rights and removes any funding commitment to develop Ewoyaa
Proceeds will help fund the North American Lithium brownfield expansion and development at Moblan in Québec
Huayou’s separate takeover of Atlantic Lithium, which holds the remaining private-sector stake in Ewoyaa, is still progressing and was not a condition of this sale
CEO Lucas Dow said the sale “delivers our goal of improving our financial flexibility while removing the development funding obligations attached to the project”
Company page: Elevra Lithium (ELV)
Sector and portfolio playbooks from Fidelity and BlackRock
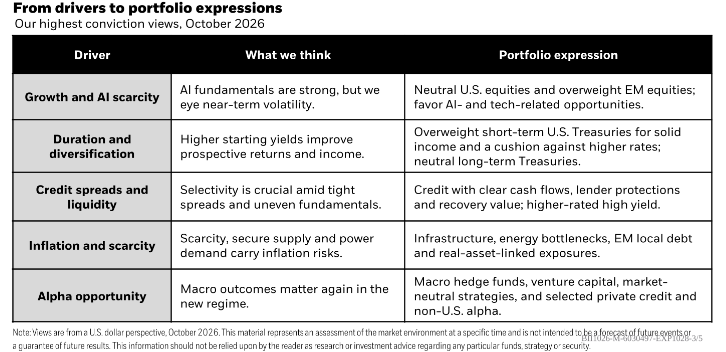
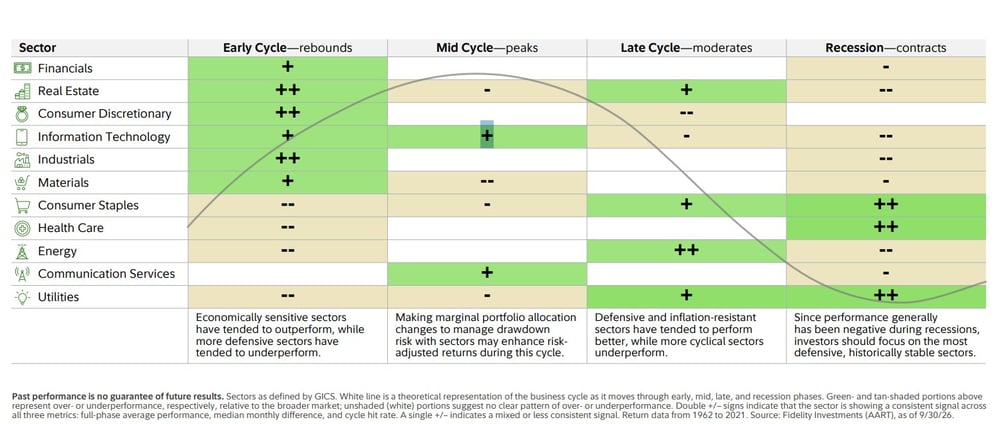
[9:02 am] Two charts doing the rounds map out where investors might position as the cycle matures and AI-driven volatility lingers.
BlackRock’s highest conviction views for October are neutral US equities and overweight EM equities, favouring short-term Treasuries, infrastructure and higher-rated high yield
Fidelity’s business cycle map shows real estate, consumer discretionary and industrials have historically led in the early cycle, while staples, health care and utilities have outperformed most consistently in recessions (1962–2021 data)
Brent hits six-month high as Trump nears Iran decision time
[8:53 am] Oil traders are pricing a renewed US bombing campaign on Iran after the 3 November midterms, with Houthi strikes on Saudi Arabia adding a fresh supply risk.
Brent rose 3.4% to US$116.62 a barrel on Friday, the highest since 29 April and up 6.2% for the week
Trump told Fox News it is “getting to be decision time” on whether to “finish it off” or make a deal with Tehran
The US has sent a third aircraft carrier strike group and 10,000 extra sailors and Marines toward the Persian Gulf, and is reducing diplomatic staff across the region
The Houthis fired missiles and drones at Riyadh’s airport and Aramco’s Yanbu facilities on Sunday, which Saudi Arabia says it intercepted
Iran is preparing to retaliate against Israel and the UAE if strikes resume, and is hitting more ships near Hormuz using guided missiles rather than drones
Gulf crude exports are above prewar levels, but product shipments remain constrained and options dealers’ gamma hedging is amplifying the futures rally
Israel votes on Tuesday, and Netanyahu’s main rival Gadi Eisenkot may be less eager to restart the war if he wins
TD Securities’ Ryan McKay expects crude to “remain skewed to the upside in the near term” with escalation risk elevated ahead of both elections
Junk debt rout deepens as CCC yields hit pandemic highs
[8:51 am] Stress in the riskiest corner of US credit is intensifying as investors question how weaker borrowers will cope with higher rates, sticky inflation and AI disruption.
The average US high-yield risk premium hit a 17-month high, while CCC yields reached their highest since the pandemic and CCC spreads a four-year high
The gap between CCC and BB spreads is the widest since the pandemic, an unusual split while the rest of the credit market remains relatively stable
More than US$5bn of US and European debt sales have been postponed this month, the biggest spate of pulled deals this year
Cable, satellite and software borrowers are the biggest laggards, with hedge fund Arini Capital losing 6.9% in the first half of October
DoubleLine’s Robert Cohen said “I do not believe the stress in CCCs is indicative of a credit cycle”
Source: Bloomberg
France dodges Moody’s downgrade
[8:51 am] Moody’s held France at Aa3 with a negative outlook, a reprieve after French bond yields rose more than any other developed market this month.
Moody’s kept France at Aa3, seven notches above junk and one notch above S&P and Fitch, which both cut in 2025
The French-German 10-year spread reached 178bp on Thursday, up from 85bp at the start of September and a level last seen in the euro debt crisis
The deficit is set to hit 5.4% of GDP this year, with PM Sébastien Lecornu targeting 5% next year but lacking a parliamentary majority
Moody’s assumes a deficit-reducing 2027 budget will eventually pass, possibly by decree, but warned protests could constrain consolidation
S&P’s next scheduled review of France is on 27 November
Source: Bloomberg
Emerging market debt draws inflows despite 5% Treasury yields
[8:50 am] Investors are treating emerging market debt as a refuge from rich-world fiscal stress rather than selling it as US yields climb.
EM bond funds have recorded 12 straight weeks of inflows, according to BofA and EPFR data
EM bond returns are nearly four times those of Treasuries since the start of 2025, and the EM spread over Treasuries has barely moved this year
JPMorgan Asset Management’s Iain Stealey said “I just don’t think people own enough emerging markets”
Budget deficits are smaller on average in EM than in developed economies according to UBS, with more borrowing now in local currencies
Dollar borrowing costs are near 10% for Mozambique, Sri Lanka and Ecuador, showing pockets of stress remain
Source: Bloomberg
Goldman cuts Kospi target by 25% but still sees 60% upside
[8:49 am] Goldman Sachs says Korean equities are pricing an overly negative outlook, even after cutting its index target following the AI-driven selloff.
Goldman cut its 12-month Kospi target to 9,000 from 12,000, citing more conservative valuation assumptions
The Kospi has fallen more than 35% from its June peak, with Samsung and SK Hynix making it a bellwether for the AI trade
The index’s forward P/E has fallen to about four, a level last seen across 18 major markets in 2006 and roughly half Indonesia’s
Goldman estimates chip valuations imply a 65% fall in 2027 sector earnings, which it calls excessively pessimistic
Goldman continues to favour power, industrials, governance plays and stocks exposed to domestic reflation and Korean pop culture
Source: Bloomberg
SK Hynix shelves Solidigm IPO as AI listings stall
[8:48 am] The pullback in AI-linked listings is spreading, with SK Hynix ditching a US float of its flash memory unit while its own July debut sits underwater.
SK Hynix shelved plans to list Solidigm in the US, which had aimed to raise US$10–15bn at a valuation of up to US$150bn
SK Hynix’s US shares closed at US$137.02, below the US$149 price of its record US$26.5bn July listing and about a third below their September high
Memory and storage stocks have shed US$1.3tn from their 2026 records, including about US$489bn from SK Hynix and US$411bn from Micron
Australian data centre operator Firmus Grid cancelled its IPO, while AirTrunk delayed its Singapore listing to next year
Source: Yahoo Finance
SpaceX rules out equity raise as AI capex surges
[8:47 am] SpaceX told JPMorgan it is not considering raising equity, leaning on debt to fund a sharp step-up in AI spending even as credit markets wobble.
Q4 capex guidance of US$35–40bn compares with US$19.6bn in Q3 and US$10.1bn in Q1
SpaceX ended Q3 with US$36.1bn in debt
Talks on a US$40bn off-balance-sheet debt structure for its AI buildout have been complicated by credit market turmoil
Connectivity revenue up 69% to US$5.2bn in Q3, with Starlink adding 1.6 million subscribers to just under 14 million
SpaceX is in talks to lease up to 80,000 US cell sites, including with Crown Castle and American Tower, sending AT&T, Verizon and T-Mobile lower
Source: Yahoo Finance
Metals traders notch second year of record profits
[8:47 am] Record copper, gold and silver prices, a tight concentrate market and lingering US tariff uncertainty have delivered another bumper year for the big trading houses.
Trafigura made a record profit of around US$2bn from metals trading in the year to September, according to people familiar
Glencore is enjoying some of its best-ever trading profits, though results were marred by a US$480m provision tied to iron ore trader Radiant World
Mercuria’s operating profit is on track to match or exceed last year’s US$300m-plus after putting more than US$4bn into metals deals
CMOC’s trading arm IXM is on track for a record year, while Vitol’s metals profit is tracking above US$100m
Ambiguity over possible US tariffs on refined copper has extended an arbitrage for traders shipping copper to the US
Source: Bloomberg
US consumer sentiment slides to five-month low
[8:46 am] US consumers’ inflation expectations are creeping higher, adding to pressure on the Fed ahead of this week’s meeting.
The University of Michigan sentiment index eased to 48 from 48.1, though it beat the preliminary reading and all ests
One-year inflation expectations rose to 4.7% from 4.6%, while 5–10 year expectations hit 3.5%, both the highest since May
Buying conditions for durable goods fell to a record low, and nearly 70% of consumers expect rates to rise, the most in over three years
Current conditions sank to the second lowest on record, but expectations improved for the first time since July
Dow sheds 1.2% as oil spike weighs ahead of Fed
[8:46 am] Rising oil reignited inflation worries on Wall Street days before the Federal Reserve’s 27–28 October meeting.
The Dow fell 1.2% to 52,215, the S&P 500 lost 0.5% and the Nasdaq slipped 0.2%, with the S&P 500 and Nasdaq down for a second straight week
Cybersecurity stocks rallied, with SailPoint, Cloudflare and Palo Alto Networks each up more than 7% after an Evercore ISI survey pointed to stronger security budgets
Apple briefly overtook Nvidia as the most valuable US company on Friday, with both worth about US$5.1tn, before Nvidia reclaimed the lead
The US 10-year yield rose 4 bp to 4.99%, giving back part of Thursday’s fall, its biggest one-day drop in more than two years
Fed funds futures price about a 5% chance of an October hike, down from 37% at the end of September, while Bloomberg Economics expects a hawkish hold with three dissents
BofA’s Michael Hartnett is staying “tactically risk-off until mid-Nov”, expecting stocks, yields and the US dollar to fall
Good morning!
[8:37 am] ASX 200 futures are down 43 pts (-0.49%). Here's what happened overnight:
Wall Street struggled as rising oil prices broadened the selloff beyond the AI trade, with the Dow bearing the brunt and the S&P 500 and Nasdaq notching a second weekly loss
S&P 500 (-0.52%), Nasdaq (-0.21%), Dow (-1.24%), Russell 2000 (-0.29%)
US weekly recap: S&P 500 (-0.47%), Nasdaq (-0.71%), Dow (+0.41%) and Russell 2000 (+2.0%)
Brent crude hit a six-month high near US$117 a barrel as Houthi attacks on Saudi Arabia and Trump's preparations for post-election Iran strikes stoked supply fears
A central bank super week looms, with the Fed, ECB and Bank of Japan all deciding as traders all but rule out an October Fed hike and eye December instead