ASX 200 Live Today - Friday, 21st August
The S&P/ASX 200 is trading lower as Healthcare stocks pull back, Discretionary and Real Estate stocks tumble. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Friday, August 21. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Reporting season is heating up and we've got you covered. Our reporting season calendar has over 250 stocks plus earnings and dividend estimates.
ASX 200 lower as Tech, Retail and Real Estate stocks tumble
[2:35 pm] That's a wrap! The S&P/ASX 200 is currently down 35 pts (-0.42%) and down 0.76% for the week. Today was a lighter session for results volume, with yesterday's reporters mostly driving the index-level moves. Goodman Group (-4.9%) continued to slide after its FY26 result, while Charter Hall (-6.5%) tumbled on a soft FY27 guidance today. Discretionary names also traded sharply lower, with Super Retail (-7.3%) giving back around half of yesterday's 15.0% results-driven rally. Financials (+0.15%) look set to snap a five-day losing streak, though the sector is still down 9.1% over the last eleven sessions.
The broader backdrop of higher oil prices (Brent up 0.4% today to a three-week high of US$93.59 a barrel) and long-duration bond yields still lingering near multi-year highs continues to weigh on equity markets. The table below shows how ASX sectors have fared over the past week. Healthcare is in the midst of an epic comeback, helped by tailwinds from a US healthcare sector at all-time highs, plus upbeat Cochlear and CSL results. Energy and materials continue to be buoyed by higher commodity prices and a weaker US dollar. Outside of those pockets, it's a dicey and choppy market.
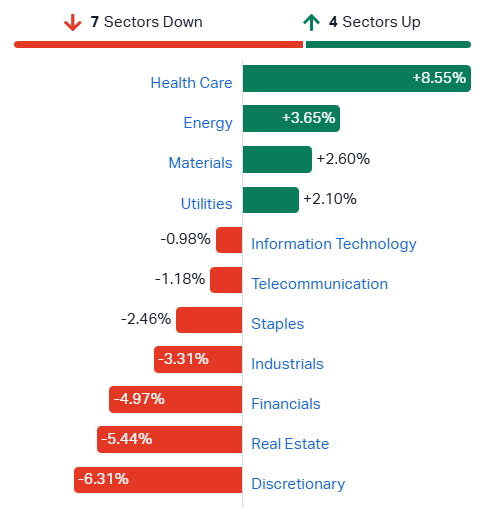
S&P/ASX 200 sector moves over the past week (Source: Market Index)
As for best and worst performing stocks of the week, pretty much everything here is results-driven (minus gold miners).
Ticker | Company | 1 Week | Price | YTD |
|---|---|---|---|---|
CSL | CSL | 23.6% | $168.39 | -2.9% |
OBM | Ora Banda Mining | 21.5% | $1.61 | 5.2% |
RWC | Reliance Worldwide Corp | 19.7% | $4.43 | 13.6% |
RRL | Regis Resources | 17.1% | $8.58 | 14.0% |
RSG | Resolute Mining | 17.1% | $1.31 | 7.1% |
ALK | Alkane Resources | 16.3% | $1.78 | 33.8% |
GMD | Genesis Minerals | 14.8% | $8.21 | 14.6% |
KCN | Kingsgate Consolidated | 14.1% | $5.31 | -5.3% |
EVN | Evolution Mining | 14.0% | $15.15 | 20.5% |
CDA | Codan | 13.9% | $48.92 | 72.1% |
Ticker | Company | 1 Week | Price | YTD |
|---|---|---|---|---|
IRE | Iress | -20.6% | $6.38 | -23.9% |
JBH | JB Hi-Fi | -17.1% | $69.19 | -28.1% |
MP1 | Megaport | -15.8% | $18.36 | 61.8% |
CNI | Centuria Capital Group | -14.6% | $1.37 | -31.6% |
IPX | Iperionx | -14.6% | $2.91 | -47.3% |
AZJ | Aurizon | -13.3% | $3.64 | -1.1% |
360 | Life360 | -13.2% | $20.72 | -35.7% |
HUB | Hub24 | -13.1% | $75.91 | -21.0% |
DOW | Downer | -13.0% | $6.62 | -16.4% |
CHC | Charter Hall Group | -11.5% | $20.67 | -15.5% |
Lithium stocks rally
[1:44 pm] Lithium stocks are trading broadly higher after Chinese lithium carbonate futures opened flattish, but now up 3.6% to 157,900 yuan a tonne. The bellwether PLS Group mirrored this price action, down around 1.5% in early trade, now trading 4.0% higher to $5.03.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
LTR | Liontown | 5.1% | $1.27 | 3.9% | -19.3% |
PLS | Pls Group | 4.0% | $5.03 | 4.7% | 19.6% |
IGO | IGO | 3.5% | $8.33 | 6.7% | 1.6% |
DLI | Delta Lithium | 2.8% | $0.19 | 2.8% | -15.9% |
AGY | Argosy Minerals | 2.3% | $0.05 | -4.3% | -62.5% |
PMT | Pmet Resources | 2.0% | $0.50 | 0.0% | -16.0% |
MIN | Mineral Resources | 1.9% | $66.77 | 3.8% | 22.7% |
VUL | Vulcan Energy Resources | 0.5% | $2.75 | -5.7% | -37.8% |
CXO | Core Lithium | 0.5% | $0.38 | 9.3% | 37.1% |
INR | Ioneer | 0.0% | $0.11 | 0.0% | -40.5% |
PAT | Patriot Resources | -1.8% | $0.06 | -11.1% | 3.7% |
GL1 | Global Lithium Resources | -2.1% | $0.69 | -7.4% | 8.7% |
EUR | European Lithium | -5.5% | $0.31 | 2.3% | 98.1% |
Kangaroo bond issuance hits record as hyperscalers turn to Australian debt
[1:39 pm] Alphabet's debut $5.5bn Australian dollar bond has opened a new funding channel for AI capex, with foreign issuance in the local market on track to break records for a fourth straight year.
Foreign issuance of Australian dollar bonds has topped US$64bn in 2026, on pace to beat last year's record, with annual sales having already broken records three years running
Alphabet raised $5.5bn (US$3.9bn) in Australia's largest ever corporate debt issuance, part of more than US$80bn of debt sold this year across six currencies to fund capex expected to reach US$205bn in 2026
The 20 year Aussie bond priced broadly in line with Alphabet's US borrowing costs once swapped back to greenbacks, which is the mechanism drawing offshore issuers to a market whose currency they generally do not need
Alphabet is paying close to 7% annually, its highest ever coupon, reflecting both higher global yields and investor concern over whether AI spending will generate returns sufficient to service the debt
Demand remains robust regardless, with orders exceeding $18bn per ANZ, roughly three times the deal size, supported by consolidated Australian pension mega funds hunting predictable fixed income and Asian investors seeking alternatives to Chinese US dollar debt
The read through is a potential issuance wave, with Betashares head of fixed income Chamath De Silva suggesting the deal could mark the start of hyperscaler issuance in Australia, against cumulative capex from the largest US players that Bloomberg Intelligence projects could reach US$6 trillion through 2030
Source: Bloomberg
China materials stocks swing from laggard to leader on gold and copper
[1:39 pm] The MSCI China Materials Index has jumped roughly 15% over the past month to outperform every other major industry group, driven by rallies in gold and copper.
Gold miners drove eight of the sector's top 10 gainers, with China Gold International Resources and Zijin Gold International each up more than 50% over the month as gold gained around 12% in August
The PBOC extended its buying streak to a 21st month, adding about 20 tonnes in July for its largest monthly purchase since 2023, alongside a weaker US dollar
Copper support came from a physical squeeze, with shrinking available LME inventories pushing the premium for immediately deliverable metal to its highest since 2021, lifting Jiangxi Copper more than 10% in a month
Valuations still sit below the market at 9.6 times 12 month forward earnings versus 10.5 times for the MSCI China Index, which is the case for the rally continuing even if commodity prices cool
Earnings estimates for the sector are up 38% this year against just 4% for the broader index, with projected 12 month earnings growth now at 54%
On the structural case, Lotus Asset Management CIO Hao Hong said AI data centre and cloud build-out means "the world needs substantially more copper, silver, rare earth and other minerals, not less"
Source: Bloomberg
Zip holds off on US listing decision as brokers lift targets after FY26 beat
[12:37 pm] Zip has parked its Nasdaq secondary listing plans pending calmer markets, even as a stronger than expected FY26 result drove target price upgrades across the street. The stock is down 11.4% today, after soaring 18.2% on Thursday.
On the US listing, CEO Cynthia Scott said Zip has progressed the process but "won't move ahead or make a decision to move ahead until we see more conducive market conditions", having already lodged a draft registration with the SEC
US revenue up 44% to US$613.1m, driven by a 9.3% lift in customers and a 43% jump in transaction value, with the stock up about 15% on the result
Majority of FY26 US volumes were non-discretionary, spanning healthcare and utility bills, which Zip frames as evidence the offering is defensive rather than cyclical
UBS lifted its target 15% to $4.70 and kept a buy, saying the better than expected guidance improves their comfort on the defensive characteristics of the category, and flagging upside to FY28 and FY29 US volume forecasts from the product pipeline
Macquarie raised its target 2.9% to $3.50 with an outperform, highlighting that US net bad debts were held within the target range alongside revenue growth and margin expansion, with that target maintained despite FY27 US volume guidance running ahead of the market
Jefferies retained a buy and a $3.80 target, noting transactions per customer have more than doubled over three years to 13 a year and seeing a path above 20 over the medium term, while Ord Minnett lifted its target 5% to $4.20
Company page: Zip Co (ZIP)
DigiCo FY26 earnings call highlights
[11:44 am] DigiCo management used the FY26 call to confirm the full 52MW of remaining SYD1 capacity is committed under letters of intent, alongside a new co-head structure and a pathway to $250m of stabilised Australian EBITDA.
On the SYD1 letters of intent: signed with multiple high-quality counterparties, with lease terms "materially longer than what we've seen previously at SYD1", escalators "around that 3% mark", and the majority of capacity going to new customers
On funding: the remaining 52MW is fully funded with no equity required, with US asset sales cutting net debt from $1.6bn to about $450m and delivering $1.2bn of pro forma liquidity
On development returns: "Just given recent cost escalations for trades and also for equipment, we think we will be slightly below the 15%, but pretty close" across the $1.2bn SYD1 and Adelaide 1 spend
On reconciling guidance to the prior $180m run rate: "You have to remove the Chicago earnings, which are around $65 million. That gets you back to $115 million," with the balance an adverse currency move to a 71c assumption
On distributions: the 15cps FY27 guidance is "mostly covered by FFO" with the board intending to return slightly more than likely FFO generation, against a medium term policy of 90% to 100%
On market conditions: US data centre moratoria have spread beyond 20 states and "a lot of that overflow capacity and demand is materialising here in Australia," with power and water access now the binding constraint
Company page: DigiCo Infrastructure REIT (DGT)
Tech stocks mostly lower
[11:42 am] The S&P/ASX 200 Tech Index is down four of the last five sessions, after closing at a fresh seven-month high last Friday. DigiCo is tumbling on a weaker-than-expected FY27 guidance, while Zip is giving back some of yesterday's ~18% gain.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
DGT | Digico Infrastructure Reit | -9.3% | $2.53 | -8.3% | -9.3% |
ZIP | Zip Co | -8.9% | $2.78 | -2.5% | -15.0% |
CAT | Catapult Sports | -6.4% | $3.49 | -2.8% | -16.1% |
MP1 | Megaport | -4.7% | $18.41 | -15.6% | 62.2% |
PPS | Praemium | -4.1% | $0.70 | -9.7% | -12.6% |
SDR | Siteminder | -4.0% | $3.76 | -2.5% | -38.7% |
NXL | Nuix | -3.7% | $1.44 | 0.0% | -20.4% |
PME | Pro Medicus | -3.6% | $198.65 | 9.5% | -10.0% |
WTC | Wisetech Global | -2.6% | $42.08 | 0.0% | -38.6% |
WBT | Weebit Nano | -2.4% | $4.06 | -15.2% | -18.8% |
DDR | Dicker Data | -1.7% | $12.58 | -0.9% | 22.3% |
DTL | Data#3 | -1.6% | $9.39 | -6.1% | 4.6% |
NXT | Nextdc | -1.4% | $13.71 | -6.6% | 11.3% |
MAQ | Macquarie Technology Group | -1.4% | $60.80 | -4.6% | -9.3% |
TNE | Technology One | -0.7% | $32.24 | -2.0% | 17.0% |
HSN | Hansen Technologies | -0.3% | $3.21 | -26.9% | -39.2% |
IFT | Infratil | -0.2% | $12.50 | -0.9% | 30.5% |
BVS | Bravura Solutions | 0.0% | $3.28 | -6.8% | 27.6% |
360 | Life360 | 0.1% | $21.15 | -11.4% | -34.4% |
CDA | Codan | 0.4% | $49.07 | 14.2% | 72.7% |
XRO | Xero | 1.7% | $86.70 | 10.3% | -23.9% |
OCL | Objective Corporation | 3.0% | $7.19 | 1.3% | -56.6% |
IRE | Iress | 3.0% | $6.43 | -20.0% | -23.3% |
AD8 | Audinate Group | 8.2% | $2.90 | 40.1% | -28.6% |
Inghams FY26 earnings call highlights
[11:22 am] Inghams management walked through a year of stabilisation, with the FY27 outlook framed around roughly $130m of incremental cost inflation and softening wholesale prices.
On the result, CEO Ed Alexander said: "The headline for financial year 2026 is that earnings were below the prior year and below the expectations that we had entering the year," with EBITDA improving from $80m in H1 to $106.6m in H2
On the FY27 cost bridge: "You take your FY26 number, you add give or take AUD 130 million of cost inflation driven by a combination of feed, Middle East, as well as embedded inflation," offset by volume, price and continuous improvement
On why guidance moderated from the Q4 exit rate: "Collectively, we are saying that is kind of $70 million incremental versus what we probably anticipated at the beginning of the calendar year," referring to Middle East and feed costs
On wholesale conditions: "We've certainly experienced pretty soft conditions through the first 7 weeks of FY 2027," with the softness flowing into retail via surplus product and discounting, though Alexander expects the correlation to fade over the medium term
On avian influenza, Alexander confirmed FY27 guidance assumes no material disruption and said: "We are not seeing any impact on demand at the moment," pointing to geographic separation across Queensland, South Australia, Victoria, WA and Tasmania as the key structural defence
On cost savings, Alexander flagged a similar target for FY27 to the $82m delivered in FY26, while conceding on inventory: "I believe that we are still carrying too much inventory"
Company page: Inghams Group (ING)
Arena REIT flags no Edge rent in FY27 guidance as it moves to re-tenant centres
[11:20 am ]Arena REIT management used its FY26 results call to detail the assumptions behind prudent FY27 distribution guidance of not less than 18cps, with the Edge Early Learning default the dominant issue.
On the guidance assumption: "We have assumed, for the purpose of prudence in the guidance, that we have received the July rent, but no further rent is received for the balance of FY 2027"
On the real estate versus the operator: "It's important to distinguish between operator-specific issues and the underlying real estate," noting the 31 Edge properties are the newest in the portfolio at an average age of 6.7 years
On re-letting timeframes: "If we've got a large number of properties that we are looking to re-tenant at a point in time, that potentially could take longer" than past single asset assignments
On replacement demand: Inbound interest since the announcement "gives us confidence that ultimately there are tenants looking to grow their networks," with term sheets already signed with a national tenant for two centres at equivalent rents over 20 year terms
On a possible buyback: "That's one that's going to be under consideration, but we've made no decision," while confirming lenders waived the review event triggered by a major tenant default with no change to commercial terms
Company page: Arena REIT (ARF)
ASX 200 slips as Tech, Real Estate and Retailers dip
[11:12 am] The ASX 200 is trading 16 pts lower (-0.18%) as yield-sensitive sectors like real estate and tech dip, and high-flying healthcare stocks take a breather.
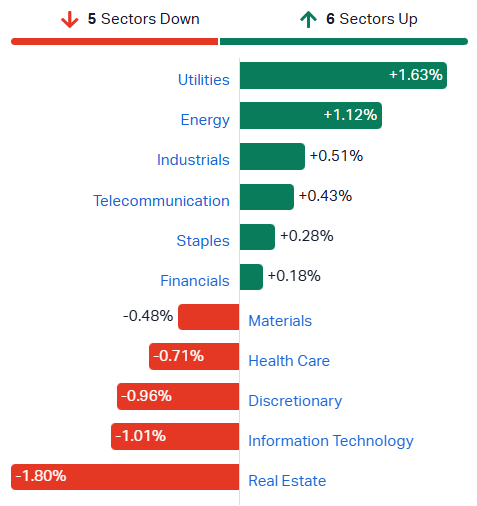
S&P/ASX 200 sectors (Source: Market Index)
Australian private sector growth softens in August as cost pressures rebuild
[10:31 am] The S&P Global flash composite output index eased to 52.5 in August from 53.2, with services carrying the expansion and manufacturing output slipping into contraction.
Composite PMI down to 52.5 from 53.2
Services activity at 52.9 from 53.6
Manufacturing output index at 49.7 from 50.3, the first contraction in goods production despite the headline manufacturing PMI holding at 52.0
New orders rose for a second month and were broad based, led by manufacturers, while export performance improved for the first time since March on a rebound in international demand for Australian manufactured goods
Input cost inflation accelerated, ending four months of easing since April's peak, with fuel, freight, commodities, raw materials and tariff pressure cited, and the pick-up more pronounced in manufacturing
Charge inflation slowed to its weakest since the start of 2026, well below cost growth, so firms are absorbing the increase rather than passing it on, which points to margin compression through the September quarter
Employment rose for the 19th time in 20 months though at the slowest pace in three months, while business confidence hit a six-month high on expansion plans and hopes of improving customer demand
Source: S&P Global
Top ASX 200 gainers and losers
[10:21 am] Energy stocks continue to trend higher as oil prices edged higher overnight, up for a fifth straight session. Meanwhile, yesterday's reporters (Zip, Telix, Megaport) are selling off, despite mixed results (Zip beat, Telix solid, Megaport very strong numbers but sold off 5% on Thurs).
Ticker | Company | % Chg | Price |
|---|---|---|---|
NWH | NRW | 8.37% | $8.23 |
KAR | Karoon Energy | 4.29% | $1.87 |
RRL | Regis Resources | 4.01% | $8.56 |
WHC | Whitehaven Coal | 3.54% | $7.90 |
ARF | Arena Reit | 3.31% | $2.50 |
YAL | Yancoal Australia | 2.94% | $5.95 |
NHC | New Hope Corporation | 2.92% | $5.83 |
TPG | TPG Telecom | 2.55% | $3.62 |
ALK | Alkane Resources | 2.54% | $1.82 |
APA | APA Group | 2.50% | $10.45 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
TLX | Telix Pharmaceuticals | -8.52% | $15.90 |
ZIP | Zip Co | -7.54% | $2.82 |
CHC | Charter Hall Group | -6.15% | $20.75 |
MP1 | Megaport | -5.85% | $18.18 |
DRO | Droneshield | -5.38% | $1.85 |
MSB | Mesoblast | -4.78% | $2.39 |
SUL | Super Retail Group | -4.64% | $13.78 |
GMG | Goodman Group | -3.39% | $27.81 |
EOS | Electro Optic Systems | -3.25% | $8.80 |
IPX | Iperionx | -3.11% | $2.80 |
Charter Hall lifts operating EPS 26.8% but FY27 guidance sits below ests
[9:50 am] Charter Hall has delivered FY26 operating earnings in line with consensus on record equity inflows, though FY27 guidance struck on no performance fees lands short of where the market sits.
Operating EPS up 26.8% to 103.2cps post-tax vs 103.3cps ests (in line), on operating earnings of $488.1m and statutory earnings of $427.9m
Distribution up 6.0% to 50.7cps vs 51.0cps ests (1% miss)
Group FUM up $10.0bn to $94.3bn including $76.0bn of property FUM, driven by $11.9bn of acquisitions and $2.1bn of net revaluation gains against $5.8bn of divestments
Record gross equity inflows of $6.7bn, weighted to institutional wholesale at $6.3bn while Direct funds contributed just $352m, alongside $17.1bn of gross property transactions
Property Investment EBITDA up 17.0% on a $3.2bn portfolio at 97.8% occupancy, 8.7 year WALE and a 5.6% cap rate, with $450m deployed in FY26 against $196m in FY25
FY27 operating EPS guidance of about 114.0cps implies 10.5% growth but sits 1% below 115.4cps ests, and assumes no performance fee revenue, while 6% distribution growth implies 53.7cps vs 54.1cps ests (1% miss)
Company page: Charter Hall Group (CHC)
GQG Partners holds margins steady but FUM slides on US$15.1bn of outflows
[9:47 am] GQG Partners has delivered a resilient first half P&L against Morgans ests, though relative underperformance drove heavy net outflows and left closing FUM well below the pcp.
Net revenue down 1.4% to US$397.2m vs US$398.8m Morgans ests (in line), with management fee revenue up 1.9% on higher average FUM
Net income down 0.8% to US$228.4m vs US$223.9m Morgans ests (2% beat), with diluted EPS flat at US$0.08
Closing FUM down 9.5% to US$156.0bn, driven by net outflows of US$15.1bn against US$8.0bn of inflows in the pcp, only partly offset by US$7.2bn of investment performance
Average FUM up 1.0% to US$164.5bn with the average fee realisation rate lifting to 48.6bps from 48.2bps on strategy and vehicle mix, so the revenue line has held up far better than closing FUM implies
Half year dividends declared down 2.5% to US$0.0716, including a 2Q26 dividend of US$0.0362, with distributable earnings down 0.7% to US$234.9m
Company page: GQG Partners (GQG)
Inghams returns to volume growth but FY27 guidance lands below ests
[9:43 am] Inghams has delivered FY26 earnings within its guidance range and at consensus, though the FY27 outlook implies a slower recovery than the market had pencilled in.
Revenue up 2.4% to $3,227.4m vs $3,198m ests (1% beat), on core poultry volume growth of 1.9% and net selling prices up 1.4% to $6.40/kg
Underlying EBITDA pre AASB 16 down 21.2% to $186.4m vs $186m ests (in line), within the $180m to $200m guidance range, with underlying EBIT down 30.0% to $153.6m
NPAT down 61.5% to $34.6m, dragged by a $12.7m tax provision after an amended ATO assessment on FY19 to FY21 R&D offsets, which Inghams is contesting
Final fully franked dividend of 6.1 cps at a 70% payout
FY26 dividend down 46.8% to 10.1 cps vs. 10.0 cps (1% beat)
Leverage of 2.2x sits above the 1.0x to 2.0x policy range, making deleveraging the stated FY27 priority alongside $80m of planned capex
FY27 guidance of $190m to $220m underlying EBITDA puts the $205m midpoint 6% below $218m ests, absorbing $30m of Middle East conflict costs and $40m to $50m of higher feed input costs
Company page: Inghams Group (ING)
Coast Entertainment returns to profit as Coomera land approval unlocks $295.9m valuation
[9:41 am] Coast Entertainment has more than tripled consolidated EBITDA and swung back to net profit, while planning approval on its Coomera landholding has triggered a strategic review.
Operating revenue up 20.8% to $116.5m (+19.0% LFL), exceeding pre-incident FY16 levels, on visitation up 29.3% to 2.0 million
Theme Parks & Attractions EBITDA up 113.6% to $18.8m excluding specific items, driven by a first full year of Rivertown and the King Claw launch
Consolidated EBITDA up 236.5% to $13.8m and NPAT of $6.1m, marking a return to net profitability
Deferred revenue up 58.7% to $20.2m on annual pass sales, locking in a stronger revenue base for FY27
Dreamworld fair valued at $295.9m and SkyPoint at $51.7m, though assets are carried at cost so no uplift flows through the accounts, with Barrenjoey engaged to review funding options
July trading moderated, with LFL ticket sales slightly below the prior period and LFL EBITDA down 7%, against three rate rises in 2026
Company page: Coast Entertainment Holdings (CEH)
Alkane Resources declares maiden dividend and $50m buyback
[9:40 am] Alkane Resources has moved to returning capital for the first time in its history, pairing a maiden final dividend with a buyback after its first full year as a merged group.
Maiden fully franked final dividend of 2.0cps for FY26, payable 1 October 2026 to shareholders on the register at 8 September 2026
On-market buyback of up to $50m approved over the next 12 months, representing less than 3% of shares on issue
Closed FY26 with $454m of cash, bullion and listed investments, which comfortably funds both initiatives while leaving capacity for organic growth spend
Capital allocation priorities set out in order, with reinvestment in the business ranked ahead of shareholder returns and balance sheet strength, so the returns are framed as surplus rather than a fixed policy
Buyback execution is discretionary, dependent on prevailing share prices and market conditions, so the $50m is a ceiling rather than a commitment
Company page: Alkane Resources (ALK)
Accent tops FY26 EBIT guidance midpoint but books a $48.6m goodwill impairment
[9:38 am] Accent delivered EBIT before impairment above the midpoint of guidance, though a non-cash writedown pushed the statutory result into a loss and the dividend was cut sharply.
Total owned sales up 4.7% to $1.53bn vs $1.55bn ests (1% miss), with LFL sales down 0.5% as a positive H1 gave way to a H2 of negative 2.0%
EBITDA down 3% to $278.9m vs $281m ests (1% miss)
EBIT before impairment down 25% to $82.6m vs $82m ests (in line), above the midpoint of the $79.5m to $84.5m guidance range
Reported EBIT of $34.0m and a statutory NPAT loss of $13.8m after the $48.6m non-cash goodwill impairment
Gross margin of 53.1% vs. 54.9% in FY25, or 54.1% excluding closed businesses, with CODB improving to 46.1% from 46.6%
Total FY26 dividends down 36% to 4.5 cps vs 3.8 cps ests (18% beat), a 78% payout at the top of the target range
FY27 to date: owned sales up 3.2% over the first 7 weeks with LFL retail down 2.0%, and $30m to $45m of identified cost, FX and store initiatives off the FY26 underlying EBIT base of $105.3m
This is a solid result, but the really suspicious thing here is that Accent rallied 12.8% on Thursday, on 6.2 million volume (vs. 20-day average of 1.23 million). So ... who is buying?
Company page: Accent Group (AX1)
Perpetual flags $63.5m TSW goodwill impairment after US$4.6bn mandate loss
[9:33 am] Perpetual has warned of a non-cash impairment against its Thompson, Siegel & Walmsley goodwill after a client flagged its intention to redeem from the International Equity strategy.
Non-cash impairment charge of $63.5m against the carrying value of TSW goodwill, to be booked as a Significant Item in the FY26 statutory result, adding to the Significant Items guidance given at the 29 July Q4 update
US$4.6bn redemption from TSW's International Equity strategy expected in Q2 FY27, which is the trigger for the impairment given the projected earnings impact on future periods
No impact on UPAT, the metric that determines the dividend payout ratio, and no effect on liquidity or banking covenant compliance, so the read through is to reported earnings and book value rather than distributions
Company page: Perpetual (PPT)
DigiCo tops FY26 EBITDA guidance but flags a softer FY27
[9:31 am] DigiCo delivered FY26 underlying EBITDA above its $125m guidance and signed LOIs for the remaining 52MW at SYD1, though its inaugural FY27 earnings outlook sits well below where the market was pitched.
Underlying revenue of $239m vs $226.4m ests (6% beat)
Underlying EBITDA of $127m vs $125.2m ests (1% beat), coming in above the $125m guidance top end
Adjusted FFO of $71m vs $59.2m ests (20% beat)
DPS of 12.0 cps, in line with both guidance and ests
FY27 underlying EBITDA guidance of $120m to $125m implies a $122.5m midpoint, 16% below ests of $146.5m, with the ex-CHI1 range of $110m to $115m representing 15% to 21% like for like growth.
FY27 capex of $300m to $500m is 2H weighted and FY27 distributions of 15.0 cps (25% growth) sit 7% below ests of 16.1 cps
Balance sheet and pipeline: gearing of 39% falls to a pro forma 18% post US asset sales, with liquidity of $706m lifting to roughly $1.2bn. The SYD1 88MW project is fully funded and phased across FY27 and FY28, supporting the pathway to Australian Platform Stabilised EBITDA of around $250m
Company page: DigiCo Infrastructure REIT (DGT)
Guzman y Gomez lifts underlying EBITDA 28.7% and guides FY27 margin above ests
[9:29 am] Guzman y Gomez has delivered record underlying earnings from continuing operations with the US exit complete, and the standout surprise sits in the capital returns rather than the P&L.
Network sales up 17.9% to $1.38bn vs $1.40bn UBS ests (2% miss), with comp sales growth of 5.3% outpaced by transaction growth and network restaurant margin up 20bps to 20.3% despite minimal menu price increases
Group revenue up 21.8% to $520.4m vs $527m UBS ests (1% miss), with franchise and other revenue up 16.3% to $91.5m
Underlying EBITDA up 28.7% to $85.0m vs $85.0m UBS ests (in line), representing 6.2% of network sales, with G&A down to 5.9% of network sales from 6.6%
Underlying NPAT up 29.7% to $53.4m on continuing operations, while the statutory group result was a $26.7m loss, better than the $33.7m loss UBS carried, with US exit costs at the low end of the guided US$30-40m range
Full year dividend of 48.0cps fully franked vs 11.4cps UBS ests, comprising a 40.6cps final including a 14.4cps special to lift the payout to about 90% of underlying earnings, with a further $100m buyback on top of the $100m already deployed and $171m cash and no debt
FY27 underlying EBITDA guidance of 6.7% to 6.9% of network sales versus UBS at 6.5%, which on the UBS network sales forecast of $1.63bn implies roughly $110m of EBITDA against the $106m carried (4% ahead), with 35 Australian openings skewed to Q4 and first seven week comps running at high single digits
Company page: Guzman y Gomez (GYG)
Credit Corp buys HSBC Australia credit card run-off book, lifts FY27 guidance above ests
[9:24 am] Credit Corp has signed a binding agreement to acquire HSBC Bank Australia's credit card run-off book for around $150m, prompting an upgrade to FY27 purchased debt ledger spend and earnings guidance.
FY27 NPAT guidance lifted to $112m to $120m from $110m to $118m, an 8% beat vs $107.3m Macquarie ests and representing 10% growth on FY26
FY27 EPS guidance lifted to 164-176 cents from 161-173 cents, an 8% beat vs 157.6 cents Macquarie ests
FY27 PDL acquisition guidance up to $300m to $380m from $200m to $280m, sitting 41% above $241m Macquarie ests, with the entire uplift in AU/NZ ($200m to $250m from $100m to $150m) while the US is unchanged at $100m to $130m
The earnings uplift is modest relative to the capital deployed, with NPAT moving just $2m on roughly $100m of additional PDL spend, reflecting a completion date early in calendar 2027 and receivables that management flags will run shorter in duration than a typical charged off book
The AU/NZ guidance uplift of about $100m sits below the roughly $150m consideration, implying part of the outlay lands in FY28 or displaces other planned purchases
Gross lending volumes guidance unchanged at $445m to $495m, with H1 FY27 NPAT guidance of $45m to $55m implying a second half skew, consistent with Macquarie's 2H27 NPAT of $60.7m against $46.6m in 1H27
Company page: Credit Corp Group (CCP)
Fisher & Paykel Healthcare beats on the first half but implied second half falls short
[9:15 am] Fisher & Paykel Healthcare has upgraded FY27 guidance on strong Hospital demand, though the full year numbers imply a softer second half than Morgan Stanley had modelled.
H1 FY27 revenue guidance of about NZ$1.24bn vs NZ$1.22bn Morgan Stanley ests (2% beat), implying roughly 14% growth on the prior corresponding half at 31 July exchange rates
H1 FY27 NPAT guidance of about NZ$280m vs NZ$251m Morgan Stanley ests (12% beat), implying roughly 24% growth excluding the impact of US tariff refunds
FY27 NPAT guidance lifted to NZ$525m to NZ$565m from NZ$500m to NZ$550m, with the NZ$545m midpoint in line with NZ$544m Morgan Stanley ests, though guidance now incorporates NZ$23m of US IEEPA tariff refunds worth roughly the entire NZ$20m midpoint upgrade
FY27 revenue guidance of NZ$2.47bn to NZ$2.57bn vs NZ$2.56bn Morgan Stanley ests, with the NZ$2.52bn midpoint a 2% miss and only the bottom of the prior range lifted
Implied second half is the sticking point, with H2 FY27 NPAT of around NZ$265m against NZ$293m Morgan Stanley ests (10% below) and revenue of about NZ$1.28bn against NZ$1.34bn (5% below), so the beat is front loaded rather than a full year upgrade
On the drivers, CEO Lewis Gradon pointed to demand for the latest hardware devices and ongoing change in clinical practice lifting consumables, with continuous improvement work feeding gross margin, which Morgan Stanley has expanding to 65% in FY27 from 64% in FY26
The Morgan Stanley data is from a slightly dated note from 26 May, which was published right after FPH's FY26 result. NZX-listed FPH shares are currently down 1.8% to NZ$42.18.
Company page: Fisher & Paykel Healthcare (FPH)
MGX swings to smaller loss as $412m cash pile funds pivot from iron ore to gold
[9:09 am] MGX Resources has closed out a transitional year in which the Koolan Island rockfall was largely offset by a stronger than expected low-grade sales program, leaving the balance sheet intact for the Central Tanami gold build.
Revenue down 38% to $204.0m FOB despite sales volumes up 3% to 2.68Mwmt, with the mix shift to 1.81Mwmt of low-grade material at 44.7% Fe (realised at just US$33/dmt FOB under fixed price contracts) doing the damage
Profit before tax and impairments up 44% to $29.1m, but a net loss after tax of $30.2m (FY25: $82.2m loss) after a $58.9m non-cash impairment effectively writing off the remaining Koolan Island carrying values
Cash and investments down 15% to $412.1m with no bank borrowings, the reduction reflecting the $50m paid for the CTPJV stake plus subsequent spend, leaving roughly two thirds of the current market capitalisation in cash
Koolan generated positive operating cashflow of $1.0m (FY25: $26.5m) at a unit cash cost of $58/wmt FOB, enough to fully fund $26.6m of rehabilitation and ramp-down, a materially better outcome than management initially guided post-rockfall
Koolan exit terms are modest but risk-shedding, with Crestlink paying at least $20.2m over five years plus up to $5m revenue share while assuming around $30m of rehabilitation liabilities, subject to FIRB and ACCC conditions and completion targeted late 2026 or into March 2027
CTPJV carries 2.8Moz at 2.8g/t for a $59.1m all-in entry cost (about $36/oz), the non-operating 1.2Mtpa CIL plant needs replacement or substantial refurbishment, and an insurance claim on the rockfall remains open with quantum still uncertain
MGX has been trading around cash for as far as I can remember. The company is winding down its Koolan iron ore project, now pivoting to gold and precious metals.
Company page: MGX Resources (MGX)
Perenti to divest BTP for $100m, books $64m non-cash loss
[9:09 am] Perenti has agreed to sell its equipment rental and parts business BTP to a Cratus Group-led consortium, freeing up capital for its contract mining pipeline.
Total consideration of $100m, comprising $80m cash on completion (subject to working capital and net debt adjustments) and a $20m deferred payment 12 months later that carries no performance hurdles or conditions
Non-cash loss of about $64m to be recognised in the FY26 accounts, implying BTP was carried well above the sale price after what management described as years of market headwinds
Completion expected by end October 2026, with the buyer still in advanced negotiations on a debt facility from a big four bank alongside equity and shareholder loans, so funding is not yet locked in
On capital allocation, CFO Michael Ellis said the proceeds support the recent Bellevue Gold and Fourmile contract wins and add capacity for the active tender pipeline and inorganic opportunities
Portfolio simplification continues, with the exit narrowing Perenti to businesses management sees as aligned with its competitive strengths and higher return hurdles
Company page: Perenti (PRN)
QuickFee delivers maiden positive NPAT after US Pay Now divestment
[9:06 am] QuickFee has posted its first positive bottom line following the sale of its US Pay Now business, with a leaner cost base driving a sharp lift in profitability despite flat revenue.
Maiden positive NPAT of $3.7m excluding the profit on sale of the US Pay Now business, the first in the company's history
EBTDA up 58% to $3.8m excluding profit on sale, with total operating expenses down 45% on pcp following the divestment
Underlying revenue down 1% to $16.8m on a normalised pcp basis excluding US Pay Now, so the earnings improvement is cost and margin led rather than growth led
Net interest margin strengthened to 15.3%, with the AUD credit facility expanded from $45m to $60m to support loan book growth into FY27
Total FY26 dividend of 1cps via a final unfranked dividend of 0.5cps, on top of the 7.5cps ($28.5m) capital return, with a special dividend of up to 1cps flagged for late 2026 once escrowed funds are received
FY27 EBTDA guidance of $4.5m to $5.5m implies 32% growth at the $5m midpoint, weighted to H2 as the QuickFee Finance solution is integrated into the Aiwyn payment platform from December 2026
Quickfee currently has a market cap of approximately $30 million, with a last close of 7.8 cents. The special 7.5 cps dividend was dished out in November 2025 (approx 62% yield).
Company page: QuickFee (QFE)
Gold know's whats up
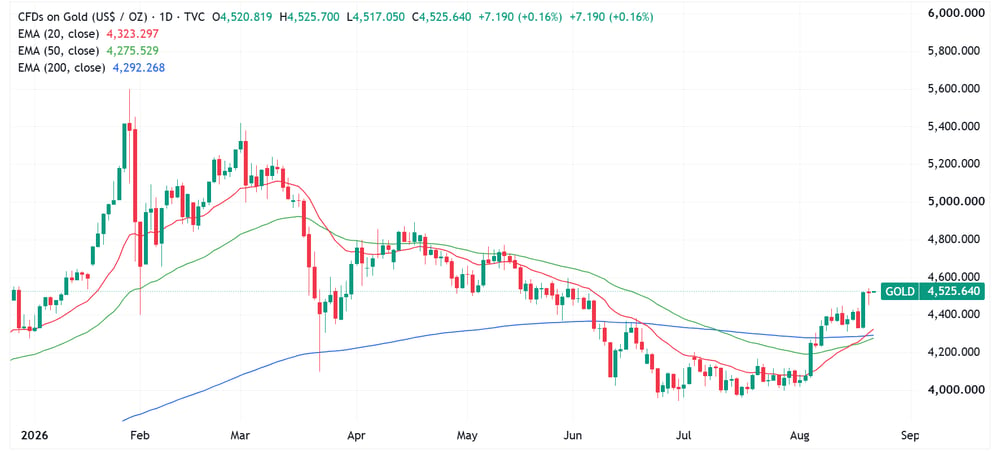
[9:02 am] An interesting overnight session for gold prices, closing fractionally lower at US$4,518 but well-off session lows of US$4,450 (-1.58%). This is in response to bond yields rising back to levels seen prior to the US Treasury announcement. Perhaps gold knows that it's going to take a lot more intervention to tame long-dated yields.
Gold daily price chart (Source: TradingView)
Trump wields tariffs as leverage as trade goals go unmet
[8:59 am] Trump's late backdown from steep Canada tariffs highlights how the administration increasingly uses levies as a bargaining chip rather than the economic cure-all it promised.
Trump paused threatened 50% tariffs on around $20 billion of Canadian goods hours before the deadline, striking a deal that could lower duties on Canadian steel, aluminium and cars in exchange for concessions including a revived Keystone XL pipeline
The strategy relies on tariffs as leverage to extract concessions from trading partners, a use that undercuts their ability to raise revenue or drive reshoring at the same time
Manufacturing gains have fallen short, with around 31,000 jobs added since January but roughly 62,000 lost on net since the start of Trump's second term
Winners include domestic steelmakers such as Cleveland-Cliffs, which has lifted prices sharply since 50% steel duties came in, with its CEO calling the policy the most effective in a generation
Consumers keep paying the premium, with tariffs equating to an average tax increase of around $1,000 per household in 2025 per the Tax Foundation, costs that stay baked into pricing
China held loan rates steady for a 15th straight month
[8:58 am] China kept its benchmark lending rates unchanged on Thursday, matching all forecasts, as policymakers lean on fiscal spending rather than fresh monetary easing to support growth.
The one-year LPR was held at 3.00% and the five-year LPR at 3.50%, with all 25 participants in a Reuters survey having tipped no change
Policymakers are favouring accelerated fiscal implementation over rate cuts to shore up growth, as banks grapple with near record-low net interest margins that limit room to ease
July data pointed to persistent weakness, with soft industrial output, retail sales and credit, and new yuan loans posting a record contraction on weak household demand
Beijing pledged at July's Politburo to accelerate fiscal spending on already-budgeted infrastructure rather than launch major new stimulus
US jobless claims edge lower, pointing to a steady labour market
[8:58 am] Applications for US unemployment benefits fell last week, holding near historic lows and signalling few layoffs across the economy.
Initial claims fell 6,000 to 206,000 in the week ended 15 August, below the 210,000 median forecast
Continuing claims rose to 1.80 million, a proxy for the number of people still receiving benefits
The four-week moving average rose to 204,000, a metric that smooths out weekly volatility
Claims remain historically subdued despite the pickup from July's 189,000 reading, the lowest since 1969
The labour market stays steady but two-sided, with employers slow to fire yet also slow to hire, leaving it tougher for those seeking work
US ramps up economic warfare on Iran as oil climbs for a fifth day
[8:58 am] Oil extended its rally after Trump threatened an "economic D-Day" on Iran and its trading partners, with the market focus shifting from military action to a coordinated campaign to choke Tehran's economy.
Trump's proposed measures would target Iran's access to banks, shipping registries, cash transfers, swap lines, front companies and smuggling networks, with an immediate focus on China as the biggest buyer of Iranian oil
Bessent will detail the plan on Monday, framing it as the greatest coordinated economic isolation in history and warning allies they are "either with us or against us"
The Strait of Hormuz remains effectively closed to Iranian exports under the US naval blockade, though crude from other Gulf producers continues to move through the waterway despite heightened shipping risks
The UAE severed economic ties with Iran, previously its top trade partner, after accusing Tehran of firing missiles at its territory
Analysts are sceptical the pressure bites, noting Iran has weathered decades of sanctions with workarounds in place, while China called for diplomacy and said sanctions will not work
Bond yields back at pre-buyback levels
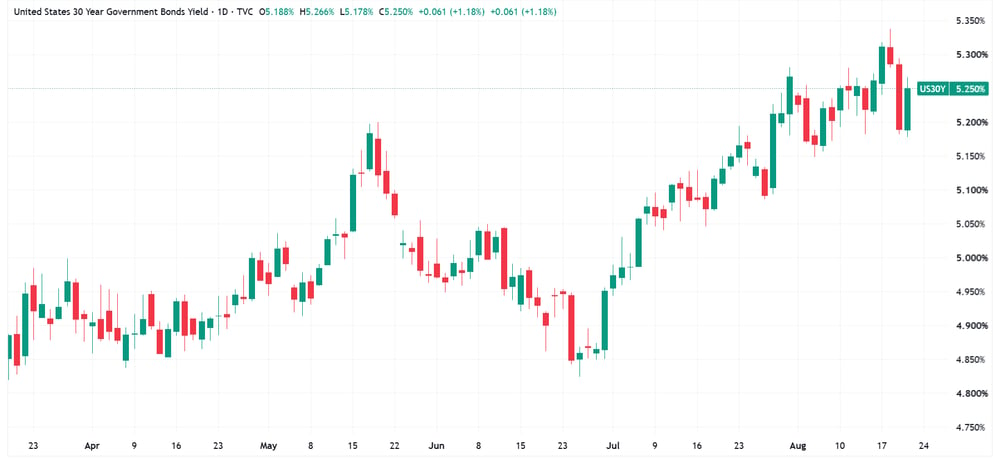
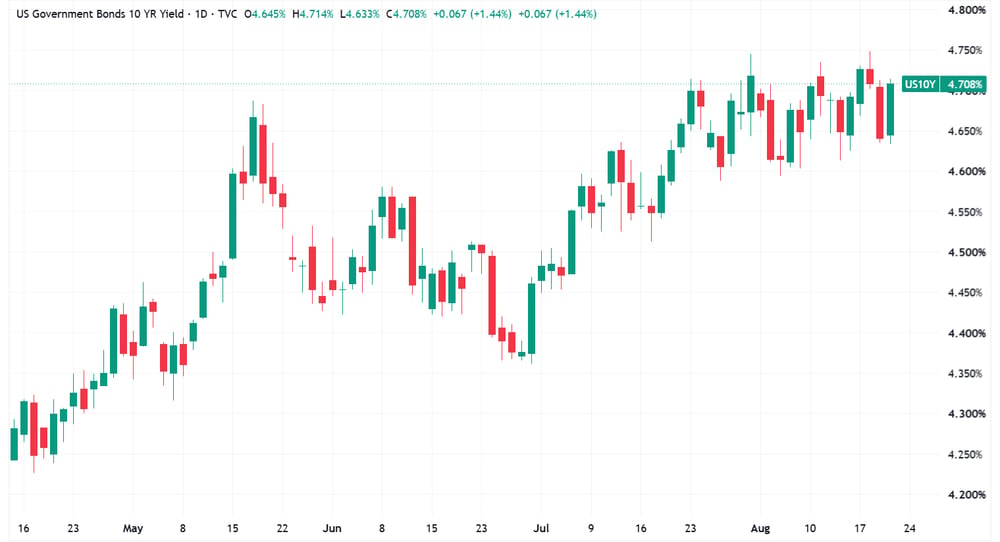
[8:51 am] The US 30-year yield is back near pre-buyback levels while the 10-year is at 4.71%, fractionally above levels seen prior to the US treasury announcement.
US 30-year bond yield daily price chart (Source: TradingView)
US 10-year bond yield daily price chart (Source: TradingView)
JPMorgan warns Treasury buybacks are a band-aid for US fiscal woes
[8:49 am] JPMorgan has cautioned that the Treasury's expanded bond buybacks will only temporarily lower long-term yields and fail to address an unsustainable fiscal position.
The buybacks will lower long-term yields temporarily but do not solve the underlying problem, according to JPMorgan
The US is running a roughly 6% budget deficit near full employment, with national debt having surpassed $40 trillion
JPMorgan estimates a funding gap exceeding $3.5 trillion in the coming fiscal years
Without meaningful fiscal reform, attempts to suppress yields will undermine Treasury's "regular and predictable" issuance approach, raise the term premium and ultimately push long-term borrowing costs even higher
US bond buybacks fail to calm surging yields
[8:47 am] Longer-dated US Treasuries fell a day after the Treasury's surprise move to boost buybacks, signalling investors remain unconvinced it can offset mounting fiscal and inflation pressures.
The 30-year yield up 6 bps to as much as 5.25% after Bessent comments and sitting near its pre-announcement level, with some yields having touched a 19-year high
Treasury pledged to "at least" double buybacks of bonds maturing between 10 and 30 years, a move analysts flagged as tactical rather than structural, with speculation it could also scale back new long-end auction sizes
Yields are being driven higher by the near $2 trillion budget deficit, elevated inflation and a flood of debt from tech companies funding AI investment
Treasury Secretary Bessent said he has "a big tool kit" to support the market, though strategists warned the long-end selling needs firmer signals on auction size cuts to reverse sustainably
The pressure is global, with UK and most European rates edging higher toward multi-year peaks as major developed markets face shared fiscal strain and sticky inflation
Source: Bloomberg
Good morning!
[8:20 am] ASX 200 futures are down 28 pts (-0.31%). Here's what happened overnight:
Major US benchmarks trended lower to close at session lows, with the S&P 500 and Nasdaq now down 1.9% and 2.5% for the week
S&P 500 (-0.87%), Nasdaq (-1.00%), Dow (-1.32%), Russell 2000 (-1.34%)
US 30-year yield up 6 bps to 5.25%, reversing almost the entirety of yesterday’s fall after the Treasury Department doubled its buyback to surpass long-term yields
Brent crude (+1.7%) reached its highest level since July 22 after Trump unveiled a sweeping economic offensive against Iran, adding to the inflation worries already driving the global bond selloff