In a nutshell:
Wall Street capped a volatile week higher, with tech rebounding from Thursday's AI wobble and the S&P 500 finishing within reach of a record ahead of bank earnings
Trump's diesel deal with Putin waived Russian sanctions through April 2027, and Moscow partially lifted its export ban over the weekend
Middle East risks flared over the weekend after a Houthi strike killed 12 at Riyadh's airport, while Bloomberg reported Russia is supplying Iran with missiles
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,812 | +0.59% |
Dow Jones | 51,655 | +0.83% |
NASDAQ Comp | 27,366 | +0.64% |
Russell 2000 | 2,807 | +0.46% |
Global Indices | ||
 S&P/TSX | 35,665 | +1.48% |
 Shanghai Composite | 3,814 | +0.05% |
 DAX | 25,087 | +1.13% |
 Hang Seng | 24,211 | +1.79% |
 Nifty 50 | 72,472 | +1.23% |
 Nikkei 225 | 69,031 | -0.02% |
 FTSE 100 | 10,552 | +1.06% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,193.87 | +1.47% |
 Copper | 6.66 | +2.21% |
 WTI Oil | 91.66 | +0.19% |
Currency | ||
 AUD/USD | 0.697 | -0.20% |
Cryptocurrency | ||
 Bitcoin (USD) | 83,520 | +0.66% |
 Ethereum (AUD) | 3,637 | +1.09% |
Miscellaneous | ||
US 10 Yr T-bond | 5.244 | +0.25% |
VIX | 14.84 | -3.70% |
US Sectors
Sector | % Chg |
|---|---|
| Real Estate | +1.88% |
| Consumer Discretionary | +1.69% |
| Health Care | +1.58% |
| Financials | +0.91% |
| Utilities | +0.82% |
| Materials | +0.65% |
Sector | % Chg |
|---|---|
| Industrials | +0.49% |
| Information Technology | +0.36% |
| Consumer Staples | +0.11% |
| Energy | -0.18% |
| Communication Services | -0.40% |
S&P 500 Session Chart
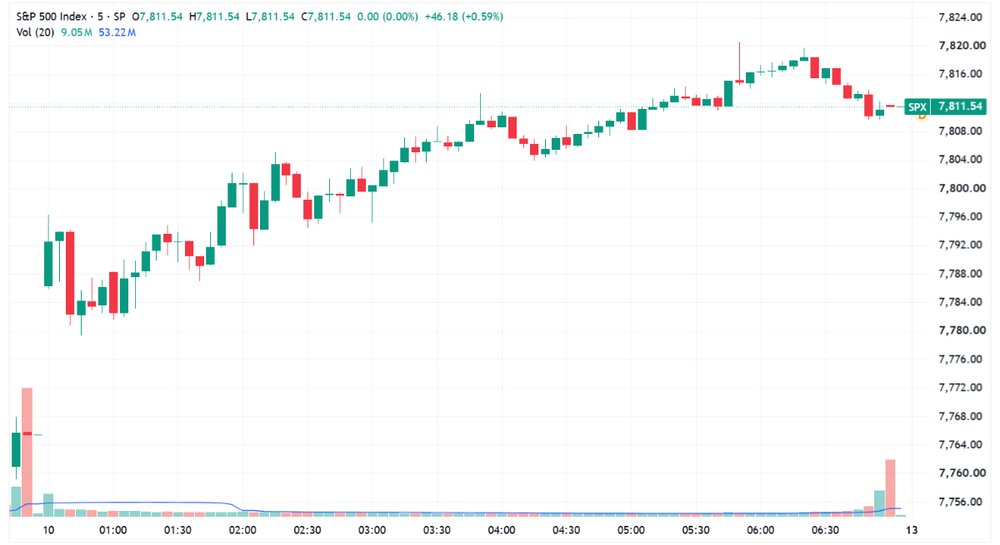
S&P 500 trended higher to close near best levels (Source: TradingView)
Overnight Markets
Major US benchmarks finished higher and near best levels, with all three indices notching weekly gains
US weekly recap – S&P 500 (+1.15%), Nasdaq (+0.64%), Dow (+0.93%), Russell 2000 (-0.91%)
Long-dated Treasury yields steadied but stayed elevated, with the 10-year hovering around 5.25%, close to the 24-year high reached earlier in the week (YF)
Earnings season kicks off Tuesday with the major Wall Street banks, with expectations for blockbuster third quarter results as the AI trade keeps the rally alive (YF)
AI stocks steadied after Bloomberg reported OpenAI expects annualised revenue to reach or exceed $70bn by year-end, easing Thursday's jitters over an FT report it topped out near $50bn (YF)
Telecom stocks were hammered after SpaceX agreed to buy a nationwide 800 MHz spectrum portfolio for Starlink Mobile, with T-Mobile down 13% and AT&T and Verizon off 10% each at midday (CNBC)
Bull market turns four on Monday, with its 119% advance sitting mid-pack against every bull run since the 1950s, says Truist's Keith Lerner (YF)
Midterms historically bullish, with the S&P 500 rising in 21 of the last 23 cycles from one month before the vote to two months after, says Deutsche Bank's Jim Reid (YF)
Stocks
Delta Air Lines Q3 adjusted revenue up 15.7% year-on-year to $17.58bn, ~1% below ests, adjusted EPS of $1.72 missed ests by ~5%. Fuel bill jumped 62% to $4.1bn on the Iran war, prompting a guidance cut and a $6bn higher annual fuel bill (YF)
Apple shares slipped after Nikkei reported October production orders for the iPhone 18 Pro and Pro Max were cut 15% from original plans (CNBC)
Moderna jumped 9% to its highest since 2021 after the New York Times detailed a public-private push to accelerate cancer vaccine development, with Pfizer and Merck also higher (YF)
Nvidia is in early talks to boost its investment in open-weight model developer Reflection AI or offer the startup computing power (BBG)
SpaceX shares rose on its spectrum deal, which Evercore ISI called the clearest signal yet that Starlink Mobile is moving toward a direct-to-consumer US service (YF)
Geopolitics
Houthi strike on Riyadh's main airport killed at least 12 and wounded more than 300, the third attack on King Khalid International this week, with all flights diverted (CNN)
Russia is supplying Iran with missiles, a Western official said, as Tehran is said to have preserved its missile and drone factories despite months of bombing (BBG)
Kremlin said Putin relayed an Iran war proposal to Trump in agreement with Iranian President Masoud Pezeshkian (CNBC)
Trump said it is "time for Ukraine to get a new president", blaming Zelenskiy for high US diesel prices after he criticised the Putin deal (CNBC)
Trump struck the diesel deal after Zelenskiy ignored half a dozen US requests to stop attacking Russian oil refineries, a US official told Axios (Axios)
Tariffs & Trade
Trump struck a diesel deal with Putin, saying Russia will supply 300,000 tonnes immediately, 500,000 tonnes in November and 1 million tonnes thereafter to US and global markets (CNBC)
US Treasury waived sanctions on Russian diesel through April 2027 under a temporary general license issued Friday (CNBC)
Russia partially lifted its diesel export ban from Saturday, allowing 500,000 tonnes to reach international markets as oil companies begin negotiating export contracts (BBG)
Trump said he is considering suspending the federal gasoline tax and teased an upcoming diesel announcement ahead of Friday's Putin deal (CNBC)
China plans to resume refined fuel exports after a brief halt over the Golden Week holiday, adding to pressure on oil prices, says PVM's Tamas Varga (CNBC)
Central Banks
RBI rolled out its strongest rupee defence since the 2013 taper tantrum, opening a dollar window for state oil refiners and adding a reserve requirement on FX derivatives (BBG)
Economy
US consumer sentiment slid to a five-month low of 46.3 in October's preliminary University of Michigan read, below the 48 expected, as cost-of-living frustration mounted (YF)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Copper Miners | 85.75 | +4.29% |
| Gold Miners | 89.28 | +2.95% |
| Silver Miners | 86.85 | +2.56% |
| Steel | 103.8 | +1.80% |
| Lithium & Battery Tech | 69.73 | +1.03% |
| Uranium | 38.9 | +0.88% |
| Strategic Metals | 60.97 | +0.64% |
Industrials | ||
| Aerospace & Defense | 206.65 | +0.86% |
| Agriculture | 28.33 | -0.04% |
| Global Jets | 27.45 | -0.11% |
| Construction | 90.7 | -0.35% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 206.49 | +3.00% |
Renewables | ||
| Hydrogen | 42.66 | +1.79% |
| Solar | 43.75 | +0.99% |
Technology | ||
| Cybersecurity | 50.08 | +4.46% |
| Cloud Computing | 30.11 | +3.86% |
| Data Center & Digital Infrastructure | 27.97 | +3.02% |
| Robotics & AI | 35.48 | +1.87% |
| FinTech | 24.9944 | +1.83% |
| Electric Vehicles | 32.7906 | +0.55% |
| Semiconductor | 559.4 | -0.69% |
ASX Today
Genus Plus buys NZ telco infrastructure contractor Universal Communications Group for NZ$38.25m upfront plus NZ$1.75m deferred and up to NZ$25m in FY27-FY28 earn-outs, a 5.1x EV/EBIT multiple. UCG holds a long-term Chorus maintenance contract and posted unaudited FY26 revenue of NZ$96m and EBIT of NZ$7.8m. Immediately EPS accretive (GNP)
Ryman Healthcare posts 379 occupation right sales in Q2 FY27, resales up 14% on pcp to 312 and an eight-quarter high, against 67 new sales. Aged care occupancy lifted 3.3ppt to 94.0% and new stock fell 67 units to 347. Reaffirms FY27 build guidance (RYM)
SCEE Group acquires Victorian fire protection and HVAC provider Entire Operations for up to $112.1m, with $70m cash on completion and up to $42.1m in earn-outs tied to FY27-FY29 EBIT. Implies 5.5x FY26 EV/EBIT at maximum base earn-out. Entire booked $191m revenue and $17.5m EBIT in FY26 (SXE)
Summerset Group sells 415 occupation rights in Q3, resales up 36% on pcp to 240 but new sales of 175 down year-on-year as Middle East conflict uncertainty stalled prospective residents’ home sales. YTD sales up 10% to 1,228. Says August’s DMF lift to 30% hasn’t dented contracting rates (SNZ)
What To Watch Today
Commodities strength: A very strong overnight session across the commodity complex, led by zinc (+3.2%), platinum (+2.8%), silver (+2.7% to US$60.77/oz), copper (+2.4% to US$6.75/lb), palladium (+2.1%) and gold (+1.4% to US$4,194/oz). There was no clear driver, with the US Dollar Index slightly higher and bond yields flattish. The resource-related ETFs on our overnight watchlist traded higher. Copper Miners soared 4.2% (still ~12% below its 26-Aug record) and Gold Miners gained 2.9%, while Rare Earths/Strategic Metals and Uranium lagged with gains of less than 1%.
Software breaks out: The iShares Expanded Tech Software ETF has looked constructive for weeks, with relatively shallow pullbacks, higher lows and a hold above its 50-day moving average. It gained 2.8% overnight to close at its highest level since 4-Nov-25. That follows a very strong Friday session for local tech (which is largely software), with Pro Medicus, WiseTech, Life360 and Xero all up 3-4%. Local names have traded far less constructively than their US peers, and Friday was the first sign of strength after a 15-20% tumble in recent weeks. Perhaps we’ll see more follow-through today.
Key Events
Stocks trading ex-dividend:
Mon 12 Oct: Civmec (CVL) – $0.035, Dominion Income Trust 1 (DN1) – $0.633, Turners Automotive Group (TRA) – $0.056, Washington H. Soul Pattinson (SOL) – $0.63
Tue 13 Oct: Katana Capital (KAT) – $0.05, Perenti (PRN) – $0.045, Sandon Capital (SNC) – $0.005, Star Combo Pharma (S66) – $0.003
Wed 14 Oct: United Overseas Australia (UOS) – $0.02
Thu 15 Oct: Acorn Capital Investment Fund (ACQ) – $0.035, Australian Foundation Investment Company (AFI) – $0.092, Cobram Estate Olives (CBO) – $0.045, Fat Prophets Global Contrarian Fund (FPC) – $0.03, Horizon Oil (HZN) – $0.01, K&S Corporation (KSC) – $0.06, Rivco Australia (RIV) – $0.018, WAM Research (WAX) – $0.05
Fri 16 Oct: Gowing Bros (GOW) – $0.03, WAM Microcap (WMI) – $0.053
Other ASX corporate actions today:
Dividends paid: CAR Group (CAR), Inghams (ING), Macmahon (MAH), TPC Consolidated (TPC)
Earnings: None
IPOs: None
AGMs: None
Economic calendar (AEST):
No major economic announcements.