In a nutshell:
Blue chips led a mostly higher Wall Street as the Dow outpaced a flat Nasdaq, with chipmakers swinging on renewed AI doubts
Oil and bond yields retreated after an unconfirmed report of a Qatar-Pakistan compromise plan to revive US-Iran talks
SpaceX posted its first quarterly profit as a public company while Netflix cut its 2026 ad revenue forecast after the bell
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,713 | +0.28% |
Dow Jones | 52,496 | +1.02% |
NASDAQ Comp | 26,425 | -0.02% |
Russell 2000 | 2,773 | +1.65% |
Global Indices | ||
 S&P/TSX | 36,108 | +0.50% |
 Shanghai Composite | 3,735 | +0.12% |
 DAX | 25,304 | -0.06% |
 Hang Seng | 23,868 | -1.32% |
 Nifty 50 | 73,853 | -1.17% |
 Nikkei 225 | 64,075 | -1.30% |
 FTSE 100 | 10,733 | -0.29% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,125.09 | -0.38% |
 Copper | 6.58 | +0.65% |
 WTI Oil | 98.18 | -0.37% |
Currency | ||
 AUD/USD | 0.7 | -0.04% |
Cryptocurrency | ||
 Bitcoin (USD) | 82,782 | +1.02% |
 Ethereum (AUD) | 3,494 | +1.97% |
Miscellaneous | ||
US 10 Yr T-bond | 5.117 | -0.37% |
VIX | 17.31 | -6.13% |
US Sectors
Sector | % Chg |
|---|---|
| Health Care | +2.33% |
| Real Estate | +1.69% |
| Utilities | +1.15% |
| Financials | +1.12% |
| Consumer Discretionary | +0.71% |
| Materials | +0.31% |
Sector | % Chg |
|---|---|
| Consumer Staples | +0.28% |
| Energy | +0.17% |
| Industrials | +0.06% |
| Information Technology | -0.34% |
| Communication Services | -0.89% |
S&P 500 Session Chart
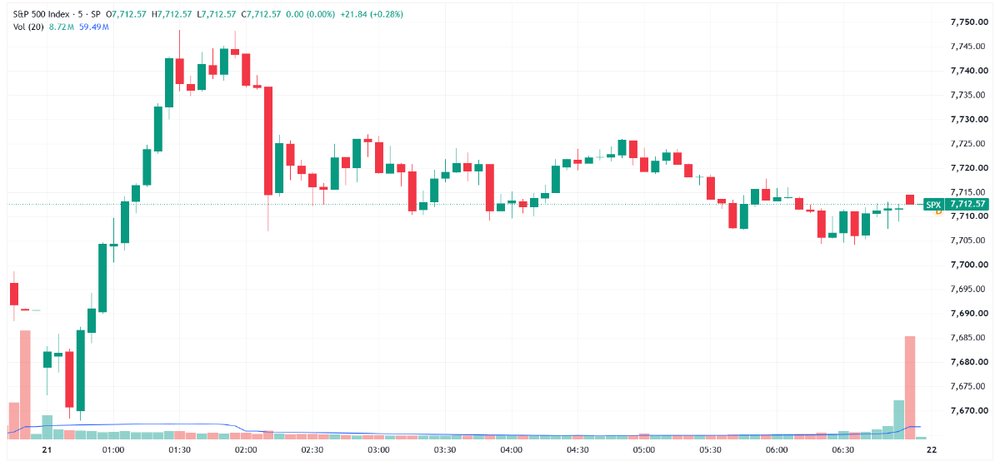
S&P 500 opens lower, rallies in the first hour of trade and closes off best levels (Source: TradingView)
Overnight Markets
Major US benchmarks mostly higher, opened lower but the Dow rallied as much as 600 points by mid-morning before gains faded into the close
A clear pivot and capital rotation is underway, with the Equal-weight S&P 500 up 3.8% since 30-Sep, while the Nasdaq is down 1.6% over the same period
Nomura stays constructive on memory and expects supply constraints to persist through at least 2028, arguing the market is underestimating AI demand. It says OpenAI and Anthropic’s combined revenue still grew ~507% year-on-year in Q3, with the headline slowdown distorted by reporting scope, customer shifts and seasonality. It reiterated Buy ratings on SK Hynix and Samsung
Treasuries rallied as oil retreated from multi-week highs, with yields falling 3 to 6 bps across maturities, led by longer-dated debt (BBG)
Brent eased from near five-month highs to around US$109 a barrel as traders bet on diplomatic progress between the US and Iran, despite escalating tanker attacks and Houthi strikes on Saudi Arabia (CNBC)
About 400 S&P 500 members rose as bets on solid earnings offset renewed tech volatility, while chipmakers swung between gains and losses on doubts over the AI trade (BBG)
Oil's risk premium understates the escalation risk after the 3 November midterms, says RBC head of global commodities Helima Croft (CNBC)
7,500 is the key S&P 500 level to watch, about 2.5% below current levels, with a break costing the market the benefit of the doubt, says CNBC's Mike Santoli (CNBC)
Stocks
SpaceX Q3 revenue jumped to $14.58bn from $7.8bn in Q2, 15% ahead of ests, while EPS of $0.35 more than doubled the $0.15 expected for its first quarterly profit since listing. Capex came in below ests and shares rose about 2% after hours (YF)
General Motors Q3 revenue up 2.9% to $50.0bn, adjusted EPS of $3.70 beat ests by ~2%. But the midpoint of its narrowed 2026 EPS guide of $12.75 to $13.75 sits below ests and it flagged rising commodity costs and softer truck sales. Shares fell despite a new $20bn buyback (RT)
3M Q3 adjusted EPS of $2.50 beat ests by ~5% and the industrial group raised its full-year guidance, with shares jumping more than 5% to help lift the Dow (CNBC)
GE Aerospace raised its 2026 guidance but Q3 free cash flow of $2.04bn missed the $2.2bn expected, a test for the commercial aerospace upcycle as shares slipped (CNBC)
Iran & Energy
Qatar and Pakistan reportedly presented a US-Iran compromise proposal including confidential IAEA inspections of Iranian nuclear sites and the transfer of interest on $6bn of frozen Iranian funds held in Qatar. The report remains unconfirmed (TK)
Iran's Revolutionary Guard said two "non-compliant" oil tankers were set ablaze in the Strait of Hormuz after hitting mines laid by its naval unit, Tasnim reported (CNBC)
Front-end WTI strength ahead of contract expiry signals a tight crude market, reflecting falling Middle East export volumes as tanker attacks and Houthi strikes intensify, says PVM's Tamas Varga (CNBC)
Tariffs
Trump administration sued over 50% tariffs on Canadian goods, with a food importer arguing the president lacked authority to invoke a never-before-used section of US law and seeking refunds (BBG)
Central Banks
Traders trimmed bets on Fed rate hikes over the coming year as oil retreated, ahead of next week's 27-28 October FOMC meeting (BBG)
Economy
US housing starts fell 5.2% to an annualised 1.22 million in September, a four-month low and below every estimate in a Bloomberg survey, while single-family permits hit the lowest since early 2023 (BBG)
US pending home sales fell 7.3% month-on-month in September and were down 11.3% year-on-year (CNBC)
German producer prices rose 6.7% year-on-year in September, the fastest since March 2023 and up 1.9% month-on-month, driven by energy costs
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Strategic Metals | 54.06 | +1.31% |
| Steel | 103.41 | +0.51% |
| Uranium | 35.18 | -0.26% |
| Gold Miners | 86.1 | -0.43% |
| Lithium & Battery Tech | 64.27 | -0.53% |
| Silver Miners | 81.39 | -0.60% |
| Copper Miners | 79.15 | -0.68% |
Industrials | ||
| Global Jets | 26.19 | +2.38% |
| Construction | 87.15 | +0.14% |
| Agriculture | 28.17 | -0.11% |
| Aerospace & Defense | 206.15 | -0.77% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 210.5 | +3.16% |
Renewables | ||
| Solar | 41.75 | +1.07% |
| Hydrogen | 37.1238 | -0.15% |
Technology | ||
| FinTech | 24.6878 | +1.78% |
| Cloud Computing | 29.09 | +1.64% |
| Cybersecurity | 45.22 | +0.78% |
| Data Center & Digital Infrastructure | 25.9 | +0.78% |
| Robotics & AI | 33.59 | +0.72% |
| Electric Vehicles | 30.74 | +0.49% |
| Semiconductor | 500.01 | -0.38% |
ASX Today
Bega Cheese reaffirms FY27 EBITDA guidance of $240-245m at its AGM, with first half earnings relatively flat and growth weighted to the second half on Branded volumes and innovation. Plans ~$110m of capex to expand manufacturing capacity, following the Strathmerton closure and Laverton logistics transformation (BGA)
SkyCity Entertainment reiterates its August earnings outlook at its AGM, with 1Q FY27 trading consistent with 4Q FY26 and the cost-out program ahead of schedule at around a quarter of targeted annual benefits. One-off change costs of NZ$17-22m to hit FY27 reported earnings. Board aims to resume dividends in FY28 (SKC)
Vulcan Steel posts 1Q FY27 revenue of NZ$353.7m, up 39%, with sales tonnes per day up 27% and EBITDA up 51% on a stronger Steel segment and Roofing Industries. Underlying EBITDA ex-Roofing up 21%. Net debt improved to NZ$216m from NZ$227m at 30 June (VSL)
What To Watch Today
Is this the start of new leadership? The easy money in the AI trade may be behind us. Recent sessions suggest capital isn’t leaving the market but rotating into defensive pockets like Healthcare, Real Estate, Utilities and Financials. Below are takeaways for two of them. I’ve left out Utilities, as heavyweights AGL and Origin earn a chunk from LNG, and Financials, which are really just a banks story.
Healthcare: The S&P/ASX 200 Healthcare Index has done a round trip. It’s now just above breakeven for the year after being down as much as 34%. Most of that recovery comes from CSL, which has more than doubled from its 3 June low of around $92. The stock trades on roughly 15x forward earnings, while the market expects only about 5% earnings growth in FY27 and FY28. That makes it hard to justify CSL climbing much further on fundamentals (though the rule with rotation is to follow it, not fight it right?). Elsewhere, Ansell and Ramsay Health Care both crushed FY26 earnings expectations and have been grinding higher since August. In hindsight, the best time to buy was right after those blowout results.
REITs: Charter Hall is probably the name to watch (the most sensitive to changes in the 10-year from memory, and names like Goodman have far too much data centre exposure). UBS research from 29 September argues this cycle differs from 2022-23, when the stock sank 60% as the RBA hiked 400 bps. Back then, an unwind of performance fees amplified the drop. This time, hikes are milder, valuations have already been reset and deal volumes are unlikely to fall as sharply. UBS says EPS growth should be “far more resilient this time around”.
Goodbye miners? As new leaders emerge, miners have flopped, with some commodities having become somewhat correlated with the AI trade. Price action in recent days has been lethargic, and overnight the copper miners, gold miners and uranium ETFs all slipped around 0.2-0.5%.
Key Events
Stocks trading ex-dividend:
Wed 21 Oct: None
Thu 22 Oct: N1 Holdings (N1H) – $0.004, Plato Income Maximiser (PL8) – $0.006
Fri 23 Oct: None
Other ASX corporate actions today:
Dividends paid: Adrad Holdings (AHL), Charter Hall Social Infrastructure REIT (CQE), EVZ (EVZ), Fitzroy River Corp (FZR), Kelsian Group (KLS), Reece (REH)
Earnings: None
IPOs: None
AGMs: Argo Global Listed Infrastructure (ALI), Argo Investments (ARG), Bega Cheese (BGA), EBOS Group (EBO), Sigma Healthcare (SIG), Transurban Group (TCL)
Economic calendar (AEDT):
5:00 pm: UK Inflation