In a nutshell:
Wall Street closed lower but well off its worst levels as a brutal chip selloff ran into a powerful bid for software and cybersecurity
The AI trade split in two after the leaders of Anthropic, OpenAI and xAI called for a deliberate slowdown in frontier model development, hammering semiconductors while security and incumbent software names rallied
Rates and oil continue to weigh on markets, with the US 10-year briefly crossing 5% for the first time since 2023 and Brent up another ~2% to US$106 after Saudi Arabia shut its East-West pipeline
Commodities didn’t stand a chance against this higher rates and energy backdrop, with copper down ~2.3% to a fresh two-week low of US$6.4/lb
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,620 | -0.48% |
Dow Jones | 52,421 | -0.29% |
NASDAQ Comp | 26,186 | -0.56% |
Russell 2000 | 2,892 | -0.40% |
Global Indices | ||
 S&P/TSX | 35,703 | +0.01% |
 Shanghai Composite | 3,885 | -0.07% |
 DAX | 25,441 | -0.50% |
 Hang Seng | 24,918 | +0.45% |
 Nifty 50 | 74,782 | -0.16% |
 Nikkei 225 | 63,493 | -0.81% |
 FTSE 100 | 10,698 | +0.44% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,297.02 | -1.23% |
 Copper | 6.33 | -2.23% |
 WTI Oil | 101.39 | +1.34% |
Currency | ||
 AUD/USD | 0.7139 | 0.00% |
Cryptocurrency | ||
 Bitcoin (USD) | 78,750 | +2.70% |
 Ethereum (AUD) | 3,562 | +1.92% |
Miscellaneous | ||
US 10 Yr T-bond | 4.961 | -0.28% |
VIX | 17.1 | +7.95% |
US Sectors
Sector | % Chg |
|---|---|
| Communication Services | +2.79% |
| Health Care | +1.35% |
| Consumer Staples | +1.27% |
| Financials | -0.35% |
| Consumer Discretionary | -0.48% |
| Real Estate | -0.78% |
Sector | % Chg |
|---|---|
| Energy | -0.86% |
| Materials | -1.03% |
| Utilities | -1.34% |
| Industrials | -1.44% |
| Information Technology | -1.67% |
S&P 500 Session Chart
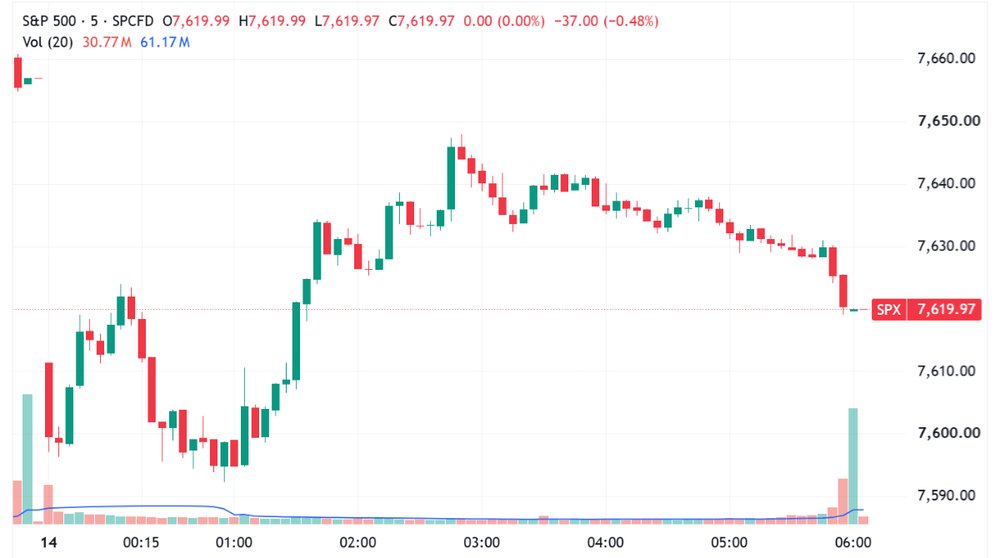
S&P 500 lower but off worst levels (Source: TradingView)
Overnight Markets
Major US benchmarks closed lower but well off session lows, the S&P 500 still trades within 3% of all-time highs
A savage chip rout sent the Philadelphia Semiconductor Index down about 5.9%, with Nvidia, Broadcom, Intel and AMD all sharply lower after AI industry leaders backed slower frontier development (BBG)
Cybersecurity was the standout winner, with the Global X Cybersecurity ETF up 10% as investors bet on fatter enterprise security budgets (CNBC)
Incumbent software names rallied on the view that slower AI progress buys them time to adapt, with the iShares Expanded Tech Software ETF up 5.0%
US 10-year Treasury yield touched 5.012% intraday, its highest since October 2023, before easing to about 4.99%, while the two-year added 3 bps to 4.66% and the 30-year flat at 5.35% (CNBC)
Bank of America's Savita Subramanian lifted her year-end S&P 500 target to 7,400 from 7,100 and set a 12-month target of 7,800, still the lowest call on Wall Street (BBG)
The AI listing pipeline reshuffled, with OpenAI's Sam Altman calling a 2026 float ill-advised while Anthropic presses on towards a Nasdaq debut before year-end (CNBC)
Asian equities bore the brunt, with South Korea's Kospi down 3.26% as SK Hynix fell 6.35% and Samsung Electronics lost 4.05%, while Japan's Nikkei 225 closed 0.81% lower (TK)
Trump dismissed AI guardrails on Truth Social, calling doomsday warnings a hoax and singling out Anthropic's Dario Amodei while claiming the administration already holds criminal and regulatory power over AI firms (QZ)
Stocks
Bank of America fell about 5% after CEO Brian Moynihan guided third-quarter investment banking fees to $1.6bn to $1.8bn against ests near $2bn, with trading revenue seen roughly flat (RT)
CrowdStrike surged about 15% to a record close near $237, building on momentum from its Fal.Con conference where it unveiled agent-monitoring tools Falcon Guardian and SafeMind (CNBC)
Novo Nordisk will trade day to day as Novo under a rebrand unveiled Monday, with CEO Mike Doustdar saying a culture reset is needed as Eli Lilly extends its lead in obesity (CNBC)
SoftBank Group tumbled 10.7% in Tokyo, the single biggest drag on the Nikkei, after Altman ruled out a 2026 listing for OpenAI, the Japanese group's largest AI holding (AP)
Iran & Energy
The Iran-Gulf meeting in Salalah was postponed after Saudi Arabia sought amendments to the Iran-Oman proposal on Hormuz, with Omani officials citing the interest of consensus and setting no new date (AJ)
Trump said Iran wants to make a deal quickly and badly, comments that helped temper the crude rally sparked by the Saudi East-West pipeline closure (YF)
Iran's foreign ministry categorically denied Trump's accusation that Tehran-backed militias inside Iraq were behind the drone attacks that forced Saudi Arabia to shutter the pipeline (CNN)
Tariffs
China's foreign ministry rejected the AI slowdown push, with spokesman Guo Jiakun saying fearmongering, confrontation and vicious competition only disrupt global AI governance and serve nobody's interest (BBG)
Trump and Xi Jinping are due to meet on 24 September, with AI governance on the agenda alongside trade, after Beijing hit back at calls to curb Chinese model developers (NPR)
Trump rejected the slowdown outright while in Ireland, saying the US is leading China in AI and he intends to keep it that way because whoever wins AI wins (CNBC)
Canada is pursuing a unique alliance with the EU rather than membership, Mark Carney said, after a Wall Street Journal report that Ottawa was exploring associate member status amid the trade war with Washington (RT)
China's state security minister Chen Yixin called for faster build-out of an AI security risk control system, describing AI as the main battleground of global technological competition (WR)
Central Banks
Goldman Sachs switched its Fed call to a 25 bp hike on Wednesday from no change, with chief US economist David Mericle noting market pricing had moved to nearly 90% after Friday's CPI (YF)
Macro Risk Advisors expects a 10% S&P 500 correction if the Fed starts hiking, arguing squeezed margins will hit profit outlooks, with traders now almost fully priced against about 60% odds a week ago (BBG)
Christine Lagarde said the energy shock is proving longer-lasting, flagging continued volatility in energy prices with euro area inflation still well above target at 3.3% (FXS)
Economy
China's new yuan loans rose just 60 billion yuan in August, far below the 400 billion yuan expected and the 590 billion yuan a year earlier, after July's record 340 billion yuan contraction (RT)
Outstanding yuan loan growth slowed to 4.9% year-on-year from 5.1% in July, the weakest pace on record, with household borrowing contracting for a sixth straight month (RT)
Canada's headline CPI held at 3.0% year-on-year in August, matching ests, with prices down 0.1% month-on-month as slower gasoline inflation offset higher rents and travel tour costs (CBC)
US average diesel prices hit a record $6.23 a gallon, up around 60% since the Iran war began, prompting Trump to blame Ukrainian strikes on Russian refineries rather than the Gulf conflict (NBC)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Lithium & Battery Tech | 69.97 | -2.13% |
| Strategic Metals | 68.93 | -2.31% |
| Steel | 106.11 | -2.62% |
| Gold Miners | 94.14 | -3.05% |
| Uranium | 42.19 | -3.08% |
| Silver Miners | 93.27 | -3.21% |
| Copper Miners | 85.62 | -3.29% |
Industrials | ||
| Agriculture | 28.96 | +0.10% |
| Global Jets | 28.18 | +0.04% |
| Aerospace & Defense | 216.77 | -1.02% |
| Construction | 92.42 | -2.55% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 204.6 | +0.82% |
Renewables | ||
| Solar | 46.22 | -1.97% |
| Hydrogen | 43.1755 | -3.93% |
Technology | ||
| Cybersecurity | 44.31 | +10.66% |
| Cloud Computing | 28.35 | +4.50% |
| FinTech | 26.5944 | +1.74% |
| Robotics & AI | 34.76 | -1.47% |
| Electric Vehicles | 33.39 | -2.45% |
| Data Center & Digital Infrastructure | 27.22 | -3.68% |
| Semiconductor | 497.4 | -5.63% |
ASX Today
CurveBeam AI receives FDA 510(k) clearance for its CT-based bone mineral density technology using supine multidetector CT scans. Will now pursue clearance to extend BMD measurement to its weight-bearing HiRise platform, opening a SaaS revenue path across the CT portfolio (CVB)
Netwealth Group to acquire AI-enabled advice workflow platform Paradino for $20m upfront, comprising $15m cash and $5m scrip, plus up to $9m in earn-out and retention over four years. A further $10m will be invested over two years, with no material near-term earnings impact (NWL)
Panther Metals sells its Mikado Gold Project tenements to Brightstar Resources (BTR) for $350,000 cash, providing non-dilutive funding. Also signs a non-binding HOA for Brightstar to fund and manage mining, haulage and processing at Burtville East, with net proceeds shared 50:50 after cost recovery (PNT)
What To Watch Today
More resources pain: Commodities faced a broad-based pullback as Brent continued its march towards US$110 a barrel and yields edged higher to ... you know how it goes [insert ‘highest since xx’ line here]. Copper tanked 2.3% to US$6.4/lb weighed by both macro pressures and stalling US tariffs on refined copper imports, zinc fell 2.0% and now down 6.3% in the last three, gold down 1.1% to US$4,298/oz or the lowest in five weeks and nickel fell 0.9% to US$16,350/t, the lowest since 8 July. The resources ETFs in our overnight watchlist finished broadly lower, with Copper Miners, Silver Miners, Uranium, Gold Miners, Steel and Rare Earths/Strategic Metals all down 2-3%.
A bid for software: iShares Expanded Tech-Software ETF up 5.0% overnight, and within 3% of the recent 27-Aug high (while local tech stocks have moved in a straight line down and ~21% away from recent highs). Nasdaq-listed Life360 shares opened the session flat, finished 3.7% higher. Perhaps we can see some positive flows for local tech.
Key Events
Stocks trading ex-dividend:
Tue 15 Sep: Data#3 (DTL) – $0.182, Duratec (DUR) – $0.025, Focus Minerals (FML) – $0.08, Guzman y Gomez (GYG) – $0.406, Lovisa Holdings (LOV) – $0.33, Neuren Pharmaceuticals (NEU) – $0.15, Plato Income Maximiser (PL8) – $0.006, Qantas Airways (QAN) – $0.198, Ramelius Resources (RMS) – $0.03, Red Hill Minerals (RHI) – $0.108, Spheria Emerging Companies (SEC) – $0.011, Westgold Resources (WGX) – $0.10, Whitefield Income (WHI) – $0.009
Wed 16 Sep: Auckland International Airport (AIA) – $0.056, Aurelia Metals (AMI) – $0.01, BKI Investment Company (BKI) – $0.02, Capricorn Metals (CMM) – $0.05, IMDEX (IMD) – $0.018, Inghams Group (ING) – $0.061, PWR Holdings (PWH) – $0.05, Servcorp (SRV) – $0.16, Service Stream (SSM) – $0.035
Thu 17 Sep: a2 Milk Company (A2M) – $0.067, EDU Holdings (EDU) – $0.03, Embelton (EMB) – $0.20, Flight Centre Travel Group (FLT) – $0.30, Lycopodium (LYL) – $0.37, SKS Technologies Group (SKS) – $0.065, Solaris Australian Equity Income Plus (SET) – $0.005, South32 (S32) – $0.075, Supply Network (SNL) – $0.44, Tourism Holdings Rentals (THL) – $0.063, WAM Income Maximiser (WMX) – $0.007, West African Resources (WAF) – $0.20
Fri 18 Sep: Adrad (AHL) – $0.026, Centrepoint Alliance (CAF) – $0.018, Macmahon (MAH) – $0.013, Vita Life Sciences (VLS) – $0.05
Other ASX corporate actions today:
Dividends paid: Data#3 (DTL), Duratec (DUR), Focus Minerals (FML), Guzman y Gomez (GYG), Lovisa (LOV), Neuren Pharmaceuticals (NEU), Plato Income Maximiser (PL8), Qantas Airways (QAN), Ramelius Resources (RMS), Red Hill Minerals (RHI), Spheria Emerging Companies (SEC), Westgold Resources (WGX), Whitefield Income (WHI)
Earnings: New Hope (NHC)
IPOs: None
AGMs: None
Economic calendar (AEST):
11:30 am: China House Price Index
12:00 pm: China Industrial Production, Real Estate Sales and Fixed Asset Investment
4:00 pm: UK Unemployment