In a nutshell:
Wall Street fell for a second session but off worst levels as small gains for chipmakers cushioned the benchmarks
US 10-year Treasury yield crossed 5.0%, the highest since 2007 as futures moved to price better than a 90% chance of a Fed rate hike on Wednesday, which would be the first since July 2023
Brent rose almost 2% to US$108.49 as Saudi Arabia's East-West pipeline remains offline, keeping roughly 4% of global supply at risk
Fed decision at 4:00 am AEST tomorrow morning, the US 2-year yield is currently ~100 bps above the federal funds rate of 3.50–3.75%, lots of possible scenarios here (a hike is near-certain but will Warsh opt for a dovish hike or guide to a new hiking cycle)
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,586 | -0.45% |
Dow Jones | 52,093 | -0.63% |
NASDAQ Comp | 25,982 | -0.78% |
Russell 2000 | 2,870 | -0.76% |
Global Indices | ||
 S&P/TSX | 35,582 | -0.34% |
 Shanghai Composite | 3,864 | -0.54% |
 DAX | 25,402 | -0.15% |
 Hang Seng | 24,667 | -1.00% |
 Nifty 50 | 74,004 | -1.04% |
 Nikkei 225 | 63,484 | -0.01% |
 FTSE 100 | 10,658 | -0.37% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,292.3 | -0.16% |
 Copper | 6.38 | +0.82% |
 WTI Oil | 105.48 | +4.03% |
Currency | ||
 AUD/USD | 0.7129 | 0.00% |
Cryptocurrency | ||
 Bitcoin (USD) | 75,444 | -3.94% |
 Ethereum (AUD) | 3,356 | -5.91% |
Miscellaneous | ||
US 10 Yr T-bond | 4.996 | +0.71% |
VIX | 17.2 | +0.58% |
US Sectors
Sector | % Chg |
|---|---|
| Energy | +2.26% |
| Materials | +0.37% |
| Health Care | -0.08% |
| Real Estate | -0.23% |
| Information Technology | -0.34% |
| Financials | -0.34% |
Sector | % Chg |
|---|---|
| Industrials | -0.64% |
| Communication Services | -0.84% |
| Consumer Staples | -0.85% |
| Utilities | -1.20% |
| Consumer Discretionary | -1.76% |
S&P 500 Session Chart
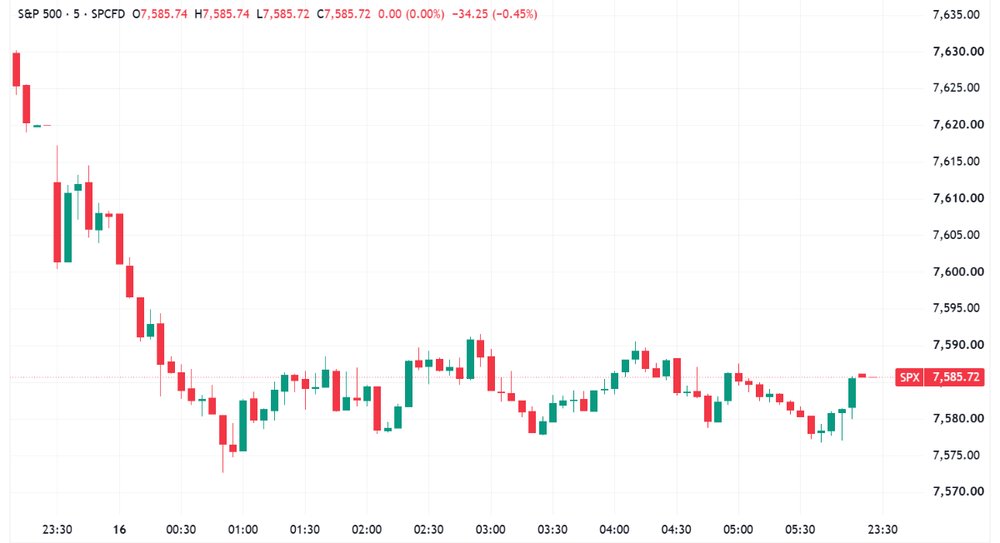
S&P 500 trends lower, closes off worst levels (Source: TradingView)
Overnight Markets
Major US benchmarks lower but off worst levels as small gains for names like Micron (+0.3%), Nvidia (+0.5%), Meta (+0.7%) and AMD (+2.1%) cushioned the indices
S&P 500 down five of the last seven sessions, trading at the lowest since 3-Aug
US 10-year yield officially closed above 5.0% for the first time since July 2007, pressured by AI corporate issuance, with surging debt sales from AI companies limiting capital allocation by primary dealers and other financial institutions
Gold hovered near five-week lows around $4,300 an ounce as elevated oil prices hardened expectations for a Fed hike this week
Bank of America fund manager survey showed a net 49% of respondents overweight global equities, down from 56% last month, with a disorderly rise in bond yields now the biggest tail risk (BBG)
Wells Fargo cut its year-end S&P 500 target to 7,700 from 7,950, with strategist Ohsung Kwon flagging 5% to 10% downside risk and multiple compression in the late innings of the cycle (CNBC)
Barclays strategists said the approaching 5% threshold on 10-year yields marks a historically important inflection point beyond which rates typically become a persistent headwind for equities (CNBC)
Stocks
Eli Lilly upgraded to buy from hold at Berenberg, which said the drugmaker is firing on all cylinders and sees upside to FY2026 guidance as it holds its obesity market lead (CNBC)
Qualcomm rose more than 4% and AMD gained 2% as AI-linked names rebounded from the prior session's chip rout, with Coherent adding nearly 2% (CNBC)
Geopolitics
Houthi forces hit the Khamis Mushait military airbase in southern Saudi Arabia with missiles and drones, striking aircraft hangars, radar systems, runways and ammunition depots in retaliation for Saudi strikes in Yemen (RT)
Saudi Arabia could exhaust exportable crude within days unless it restores the East-West pipeline, potentially removing as much as 4% of global supply, Saudi buyers and traders said (RT)
The East-West pipeline normally reroutes about 4 million barrels a day to the Red Sea port of Yanbu, bypassing the Strait of Hormuz, and repairs could take several weeks (RT)
Goldman Sachs senior commodity strategist Grigsby said the infrastructure attacks mark a meaningful escalation and raise the probability of an upside scenario where Brent exceeds $120 (CNBC)
ING analysts said prices are likely to remain well supported until there is clarity on the extent of damage and the duration of the East-West outage (RT)
Commodity vessel transits through the Strait of Hormuz remained in single digits, well below the 10-day average of about 14, with Gulf-Iran talks still postponed (RT)
Zelenskyy said no energy-strike deal had been finalised after Trump posted that Moscow and Kyiv had both agreed to halt attacks on energy infrastructure (BBG)
Half of Russia's six top diesel-producing refineries significantly cut back or completely halted output in September after damage sustained in drone attacks (RT)
Tariffs
New US tariffs took effect on a small number of Canadian goods on Tuesday, with some products removed from coverage, under proclamations modifying the Section 338 action against Ottawa (CTV)
Trump said a trade deal with Canada could be reached "fairly soon", claiming Ottawa is eager to sign an agreement as the 18-month trade war drags on (CTV)
China's statistics bureau said export resilience is powering growth, with the global AI investment boom lifting demand for Chinese semiconductors and tech hardware (CNBC)
Central Banks
Fed funds futures priced roughly a 92% probability of a 25 basis point hike on Wednesday, which would mark the first increase since July 2023
A hike would lift the target range to 3.75% to 4.00% from 3.50% to 3.75%, with December follow-up odds above 75% (Qz)
Bank of Japan hike odds sat above 90% for its 17-18 September meeting, which would deliver the first simultaneous US and Japan increase since July 2006 (SED)
BMO Wealth Management strategist Carol Schleif said the Fed has little choice but to hike, arguing the bond market has signalled for weeks that higher rates are warranted (CNBC)
Natixis Americas chief US economist Hodge said Warsh will stress the decision is discrete and does not pre-commit the Fed to action at subsequent meetings (Qz)
Economy
China August retail sales grew 0.4% year-on-year, slowing from 0.6% in July and missing the 0.8% forecast in a Reuters poll of economists (CNBC)
China August industrial output rose 5.2% year-on-year, accelerating from 4.5% in July and beating expectations for a 4.8% rise in a Reuters poll of 42 analysts (RT)
China urban fixed-asset investment fell 7.2% in the first eight months from a year earlier, steepening from a 6.7% decline through July and matching analyst expectations (CNBC)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Steel | 106.58 | +0.44% |
| Lithium & Battery Tech | 70.02 | +0.07% |
| Gold Miners | 94.13 | -0.01% |
| Silver Miners | 92.71 | -0.60% |
| Strategic Metals | 68.3 | -0.91% |
| Uranium | 41.77 | -1.00% |
| Copper Miners | 84.59 | -1.20% |
Industrials | ||
| Agriculture | 28.88 | -0.28% |
| Construction | 91.98 | -0.48% |
| Global Jets | 27.88 | -1.06% |
| Aerospace & Defense | 214.0 | -1.16% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 202.0 | -1.27% |
Renewables | ||
| Hydrogen | 43.51 | +1.19% |
| Solar | 45.09 | -2.44% |
Technology | ||
| Cybersecurity | 45.3 | +2.23% |
| Semiconductor | 498.85 | +0.36% |
| Data Center & Digital Infrastructure | 27.14 | -0.29% |
| Robotics & AI | 34.63 | -0.37% |
| Electric Vehicles | 33.2128 | -0.44% |
| Cloud Computing | 28.19 | -0.56% |
| FinTech | 25.68 | -3.42% |
ASX Today
Briscoe Group delivers record H1 sales of NZ$374.2m, +0.8%, though NPAT slips 5.8% to NZ$27.6m as gross margin narrows 58bp to 40.85%. Sporting goods +2.6% on a heavy events calendar offsets softer homewares, with heating and luggage both weak. Interim dividend 10.0cps (BGP)
Infratil lifts FY27 proportionate EBITDAF guidance to NZ$1.32-1.42bn from NZ$1.30-1.40bn after CDC Data Centres raised its own FY27 range to $710-750m from $680-720m on a further 70MW of contracts and cost savings. Data centres now account for just over half of NZ$22bn total asset value (IFT)
Wiluna Mining has terms out for a $180m IPO at 65-85c a share, valuing the WA gold producer at $471.7-539.4m and targeting an ASX return around 26 October via Argonaut and Barrenjoey. Proceeds cover $40m of Byrnecut debt and $45.6m working capital, with exploration the near-term focus after a July CIL tank rupture halted mining (AFR)
What To Watch Today
Fed decision tonight: The Fed has a few options, but none of them hit the mark against a backdrop of Brent at US$108, the US 10-year at 5.0% and the 2-year at 4.67%, versus a federal funds rate of 3.50-3.75%. What the Fed does matters less than what it signals about its view of the economy. Does Warsh flag a round of "adjustment hikes", two or three more and done, or does he lean into language that guides to a fresh hiking cycle, which aggressively reprices near-term rate forecasts? The catch is that the more dovish he sounds, the more the market does the tightening for him, as long-end yields push higher on rising inflation expectations. It's a lose-lose, and at a time when physical oil markets are getting really tight.
Commodities hold, miners not so much: Copper rose 0.98% to US$6.47/lb, with aluminium (+0.14%), silver (+0.72%), palladium (+1.4%) and zinc (+0.7%) also higher. Gold slipped 0.1% to US$4,293/oz. The bounce in commodity prices didn't carry into equities, with most of our resource-related overnight ETF watchlist lower, including Copper Miners (-1.2%), Uranium (-1.0%), Rare Earth/Strategic Metals (-0.9%) and Silver Miners (-0.6%). Gold Miners finished flat. It's an uncomfortable market, with little sign of equity risk premium going back into these stocks.
Key Events
Stocks trading ex-dividend:
Wed 16 Sep: Auckland International Airport (AIA) – $0.056, Aurelia Metals (AMI) – $0.01, BKI Investment Company (BKI) – $0.02, Capricorn Metals (CMM) – $0.05, IMDEX (IMD) – $0.018, Inghams Group (ING) – $0.061, PWR Holdings (PWH) – $0.05, Servcorp (SRV) – $0.16, Service Stream (SSM) – $0.035
Thu 17 Sep: a2 Milk Company (A2M) – $0.067, EDU Holdings (EDU) – $0.03, Embelton (EMB) – $0.20, Flight Centre Travel Group (FLT) – $0.30, Lycopodium (LYL) – $0.37, SKS Technologies Group (SKS) – $0.065, Solaris Australian Equity Income Plus (SET) – $0.005, South32 (S32) – $0.075, Supply Network (SNL) – $0.44, Tourism Holdings Rentals (THL) – $0.063, WAM Income Maximiser (WMX) – $0.007, West African Resources (WAF) – $0.20
Fri 18 Sep: Adrad (AHL) – $0.026, Centrepoint Alliance (CAF) – $0.018, Macmahon (MAH) – $0.013, Vita Life Sciences (VLS) – $0.05
Other ASX corporate actions today:
Dividends paid: APA Group (APA), Codan (CDA), EarlyPay (EPY), Helloworld Travel (HLO), Lendlease Group (LLC), MA Financial Group (MAF), Magellan Financial Group (MFG), Vicinity Centres (VCX)
Earnings: None
IPOs: None
AGMs: Contact Energy (CEN)
Economic calendar (AEST):
9:50 am: Japan Balance of Trade
4:00 pm: UK Inflation
10:30 pm: US Retail Sales
4:00 am: Fed Interest Rate Decision (Ests: 25 bp hike to 4.0%)