Coles shares tumble as flat 1H27 Supermarkets earnings miss forecasts by 7%
A rotation-fuelled staples rally left Coles priced for safety. Flat first-half earnings and a 7% miss just pulled the rug.
Mentioned
KEY POINTS
- Coles expects first-half Supermarkets EBIT to be flat at about $1.23bn, roughly 7% below UBS forecasts, citing price investment, heavier competitor promotions and higher fuel costs.
- Supermarkets comparable sales rose 2.7% in the first quarter, slowing from 4.6% a year earlier and trailing Woolworths, which posted 6.9% Australian food sales growth this week.
- Shares fell as much as 12.7%. A defensive rotation had lifted the Staples index to its highest level since August 2022, leaving Coles priced for safety, not a downgrade.
Coles (COL) says price investment, heavier competitor promotions and rising fuel costs will leave first-half Supermarkets earnings flat, well-short of market expectations of mid-single digit growth.
The sizeable guidance miss follows a series of sales slowdown warnings from top retailers including JB Hi-Fi, Wesfarmers and more, earlier this week (more on that below).
CEO Leah Weckert said “while Supermarkets sales growth remained in line with the prior quarter, we know household budgets are under pressure and customers are shopping more deliberately across retailers and channels."
The stock opened the session 6.9% lower to $21.83.
1Q27 at a glance
Supermarkets sales up 3.6% to $10.32bn
Supermarkets comparable sales up 2.7%, slowing from 4.6% in 1Q26 and tracking below FY27 ests of ~3.5%
eCommerce sales up 22.9% to $1.62bn, lifting penetration to 15.7% from 13.3% in 1Q26
Liquor sales down 1.3% to $831m, in line with comparable sales, as convenience stores grew and Warehouse trends improved
1H27 Supermarkets EBIT expected to be flat at about $1.23bn vs UBS ests of $1.32bn (7% miss)
Supermarkets sales growth has moderated in the first four weeks of 2Q27, with Coles relaunching its Every Day Price program to regain momentum
Jefferies expects Coles shares to trade weakly after Q1 supermarket same-store sales rose just 2.7%, lagging Woolworths by more than expected. Woolworths posted a 6.9% rise in Australian food sales earlier this week.
Analyst Michael Simotas says “price investment is required, which combined with operating deleverage and higher fuel costs implies a meaningful consensus downgrade.”
The 1Q27 commentary also represents a sharp U-turn compared to what Coles said less than three months ago at the FY26 result on 25 August.
"We enter FY27 in a strong position, with supermarkets having gained market share and significantly improved customer satisfaction scores over the past year."
"In the first few weeks of FY27, sales momentum was well ahead of 4Q FY26, with a temporary moderation during a competitor’s collectibles campaign in late July and early August.
"Following the end of the collectibles campaign, sales recovered quickly back to levels consistent with 4Q FY26"
Not one bit of optimism in sight
The Coles guidance downgrade follows a string of downbeat trading updates and AGM commentary from earlier this week, including:
JB Hi-Fi (JBH):
JB Hi-Fi Australia comparable sales fell 1.4% vs ests of down 1.3% (in line), The Good Guys fell 0.4% (in line) and JB Hi-Fi New Zealand rose 10.7% (slight miss)
JB Hi-Fi said “the Group continues to see variability in trading and heightened competitive activity, with customers remaining focused on value and increasingly shopping during promotional events”
Super Retail Group (SUL):
Group like-for-like sales rose 0.2%, with Supercheap Auto up 2.5%, while rebel (up 0.3%), BCF (down 1.1%) and Macpac (down 11.7%) are all tracking below ests for 1H27
Super Retail pointed to higher fuel prices weighing on BCF and promotional timing and a milder winter hitting Macpac, while Supercheap Auto and rebel both gained market share
Wesfarmers (WES):
Bunnings sales growth has moderated since 2H26 on weaker seasonal and commercial sales in recent weeks, while Kmart and Officeworks are tracking broadly in line with 2H26
Wesfarmers said “elevated inflation and higher interest rates continue to impact demand in parts of the Australian economy and are placing pressure on household and business budgets”
Vicinity Centres (VCX):
Portfolio sales rose 3.0% in 1Q27, with specialty and mini-majors up 3.6% from 2.0% in 4Q26 and occupancy steady at 99.6%
CEO Peter Huddle said “shoppers remain deliberate in how they spend... discretionary spending remains evident, with jewellery, cosmetics, and Apparel & Footwear performing particularly well”
Where to from here?
Coles is getting absolutely obliterated. The stock opened 6.9% lower and tumbled as much as 12.7% by 10:24 am AEDT.
The broader context is that the AI trade has wobbled in recent weeks, sparking a rotation out of all things AI and into defensive pockets of the market like Healthcare, REITs, Staples and Banks. The S&P/ASX 200 Staples Index rallied as much as 8.7% between 1 and 26 October to its highest level since August 2022. But that re-rate was driven more by a capital rotation than any genuine improvement in fundamentals or growth.
That leaves Coles trading well above where it otherwise would be, right as it delivers a material earnings downgrade. Analysts were expecting first-half Supermarkets EBIT growth of about 7%, and Coles now expects none.
What’s interesting is that Woolworths is up 1.2% at the time of writing to $39.96. Normally, a downgrade from Coles would drag Woolies down with it. The resilience might suggest the Ooshies campaign has genuinely resulted in market share for Woolies, or that Coles’ challenges are its own.
Coles is now trading just above breakeven for the year, on a total return basis.
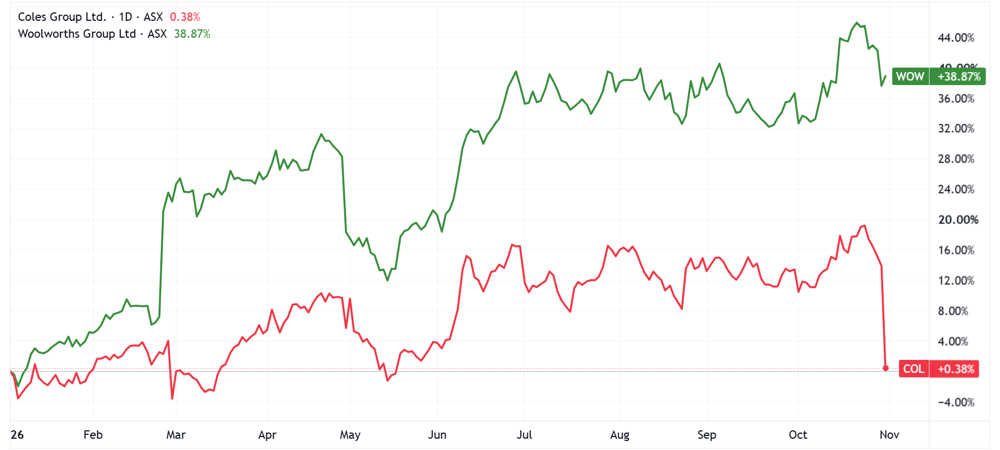
Coles vs. Woolworths year-to-date price charts, including dividends (Source: TradingView)