ASX 200 Live Today - Tuesday, 11th August
The S&P/ASX 200 is trading higher as energy, mining and healthcare stocks continue to trend higher, offsetting losses from defensive sectors
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Tuesday, August 11. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Reporting season is heating up and we've got you covered. Our reporting season calendar has over 250 stocks plus earnings and dividend estimates.
ASX 200 higher, RBA holds but keeps door open to more hikes
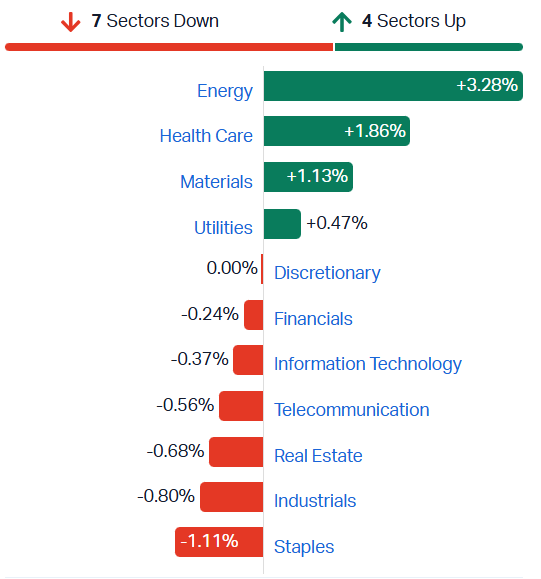
[2:38 pm] That's a wrap! The ASX 200 is currently up 0.35% as the high-flying Energy (+3.6%), Healthcare (2.0%) and Materials (+1.2%) sectors carry the index higher, offset by softness across Staples, Industrials, Tech and Telcos.
The index nudged a little higher on a relatively unsurprising RBA decision, which held rates at 4.35% but signalled it is ready to tighten further if inflation risks build. Key highlights from the RBA statement include:
Cash rate held at 4.35%, following three increases already this year, with the decision unanimous
Inflation still judged too high and not expected to return to around the midpoint of the target range until late 2027, with upside risks to that projection
Middle East conflict keeping oil and related commodity prices elevated and feeding through to broader goods and services prices
Housing momentum turning, with prices falling in some capital cities and new housing loans declining noticeably
Labour market has eased by a little more than expected, though leading indicators point to only limited further softening near term
Board reiterated it will lift the cash rate again if upside risks materialise, keeping the policy stance tilted restrictive
Westpac's soft Q3 sets a subdued tone for bank reporting season
[1:37 pm] Westpac's Q3 update disappointed on margins despite the tailwind of higher rates, with cash earnings broadly in line but revenue growth modest and solid lending and deposit volumes unable to offset intensifying competition. Management flagged a sharp drop in mortgage applications since the Federal Budget, and shares closed 5.9% lower. Brokers generally trimmed earnings forecasts on softer margins, partly offset by an improved expense outlook, while focus centred on fading replicating portfolio tailwinds and a deposit shift towards term products.
Analyst Highlights
Morgan Stanley retained Underweight, lowered target from $30.50 to $30.00: called it a disappointing update with mounting revenue and margin headwinds and little room for error on loan losses or costs, cutting EPS forecasts across FY26 to FY28.
JPMorgan retained Underweight, lowered target from $34.00 to $33.60: viewed it as a broadly in line quarter with core margin up slightly and institutional margins improved, making only minor EPS cuts on softer margins and fee income, with post Budget mortgage applications a key investor focus.
Macquarie retained Underperform, target unchanged at $30.00: saw an acceptable quarter but more challenged revenue growth as replicating portfolio tailwinds eased, with a solid capital position and benign asset quality despite modest deterioration expected ahead.
UBS retained Buy, target unchanged at $45.00: noted earnings growth failed to keep pace with assets and a deposit mix shift towards term deposits pressured margins, though substantial excess capital may drive shareholder return pressure.
Analysts' take on Integral Diagnostics
[1:35 pm] Integral Diagnostics' preliminary FY26 result on Monday missed revenue, earnings and profit expectations, though margins held broadly in line with guidance, with management also confirming a new CFO effective October. Shares closed down 2.3% on the day.
Analysts focused on the revenue shortfall, splitting on whether it reflected New Zealand currency headwinds or genuine domestic share loss around GP referrals and the Capitol network build out, while the margin result was viewed more favourably as evidence of cost discipline. Sentiment leaned constructive on valuation grounds, with the combined CEO and CFO transition framed as a clean slate moment ahead of the formal August result.
Analyst Highlights
Bell Potter retained Buy, lowered target from $3.80 to $3.60: sees this as the first result reflecting the full Capitol merger impact, with referral network build out taking longer than anticipated and the CFO transition raising impairment risk, though believes long term investors could use the weakness to accumulate.
Jarden retained Buy, lowered target from $3.25 to $2.95: attributes much of the miss to currency rather than operations but views the earnings slowdown as evidence of genuine underperformance, flagging referral share loss in key states and execution risk in motivating doctors on fixed price contracts.
RBC Capital Markets retained Outperform, lowered target from $2.85 to $2.60: sees the leadership change as increasing risk to long term targets but views balance sheet deleveraging and capex discipline as tracking to plan, maintaining valuation based conviction despite near term uncertainty.
Treasury Wine's FY26 upgrade puts Penfolds back in the spotlight
[1:34 pm] Treasury Wine Estates upgraded its FY26 EBITS guidance on Monday off the back of stronger Penfolds performance, with the pre-release landing at or above the top end of prior expectations and ahead of consensus, though further Americas impairments weighed on reported NPAT. Shares traded up as much as 7.9% before closing 4.2% higher.
Analysts broadly credited Penfolds as the earnings engine, supported by improving China depletion momentum and grey market discipline, but most stopped short of calling the Americas turnaround complete, wanting clearer evidence of a genuine US earnings inflection before building conviction.
Analyst Highlights
UBS retained Neutral, raised target from $5.00 to $6.25: views the Penfolds recovery as increasingly de-risked and earnings quality as improving as legacy issues resolve, with management nearing its leverage target and scope for valuation upside as the turnaround progresses.
JPMorgan retained Neutral, raised target from $5.20 to $5.90: sees Penfolds strength as the key earnings driver and Americas weakness as a deliberate trade-off, but flags execution risk in the scale of brand divestment and wants evidence of demand stabilisation before turning more positive.
RBC Capital Markets retained Sector Perform, raised target from $5.00 to $5.10: welcomed decisive action on US supply chain rebalancing and views impairments as sensible non-cash portfolio clean-up, though wants more detail on regional depletion mix and further demand evidence before turning more constructive.
ASX 200 higher on Energy, Healthcare and Miners
[12:50 pm] The S&P/ASX 200 is up 0.26% after two days of slight declines, and still within 0.2% of all-time highs.
A very strong bid for energy stocks, with the S&P/ASX 200 Energy Index now trading at its highest since 6 May. Today's session feels like more than just a strong overnight lead (Brent up 6.6%), with energy stocks starting to price in a higher-for-longer oil backdrop. Usually when oil spikes, local energy names gap up and chop around the open price. Interestingly, Iranian outlets noted that Iran has completely ruled out any future negotiations with the Trump administration, declaring it will wait out his term until 20 January 2029.
S&P/ASX 200 sectors (Source: TradingView)
Amotiv talks up offshore growth, Chinese OEM wins and cost discipline as it names CEO succession
[12:48 pm] Management framed the FY26 call around beating guidance in a tougher market, offshore diversification and the Unified program, alongside news that CEO Graeme Whickman will step down.
On offshore diversification: "The offshore contribution now 18% of revenue up from effectively nothing five years ago... it's been a significant part of the buffer against continued subdued ANZ conditions"
On the Chinese OEM position: "We've got supply relationships with every major Chinese OEM selling into this market... all that tells you is that we are the preeminent go to supplier"
On the four-wheel-drive market backdrop: "That fourth quarter exit rate is probably the sharpest move we've seen all year, and that's why we're planning it for FY27 on the basis that the new vehicle sales will stay soft"
On steel cost pressure: "We've seen some pretty extreme steel price increases in the last three, six months, you know, approaching the 30% mark... we are right now offshoring as much as we can"
On the offshore volume opportunity: "By the time we get to FY28, we believe that the volume that we've been winning offshore, meaning in Europe and US will actually in the medium term outstrip any decline domestically"
On the FY27 outlook: "You should expect modest revenue and underlying EBITDA growth in FY 2027 with growing offshore revenue pricing a mode of unified offsetting some subdued ANZ conditions"
On the CEO succession: "I've led Amotiv for eight years and I believe it's the right time for me to begin that next chapter of my career and for the company to go and find its next leader"
Company page: Amotiv (AOV)
Arena REIT down 32% in two days
[12:40 pm] Arena REIT was hit by at least four broker downgrades today, after the company issued notices of default to troubled tenant Edge Early Learning on Monday.
Jefferies downgraded to Hold from Buy; cut target to $2.74 from $3.62
UBS downgraded to Neutral from Buy; target cut to $2.71 from $3.92
Morgan Stanley downgraded to Underweight from Equal-weight; target cut to $2.65 from $3.75
Ord Minnett downgraded to Hold from Buy; target cut to $2.85 from $3.35
Arena REIT tumbled 22% on Monday to $2.56 after Edge requested rent deferral or abatement in late July amid a corporate restructure and failed to pay rent due on 3 August.
Arena declined to agree to any deferral or abatement. Edge represents about 14% of Arena's annual rental income, though Arena holds a pooled bank guarantee and security deposits totalling about $4 million, and FY26 distributable income and distributions are unaffected.
Centuria Industrial REIT talks up rent reversion, data centre optionality and its NTA discount
[12:38 pm] Management framed the FY26 call around embedded rental upside, an emerging data centre pipeline and the disconnect between direct-market pricing and the REIT's listed value.
On the valuation disconnect: "One of the defining features of CIP today is the disconnect between direct market evidence and its listed market valuation... the REIT continues to trade at a material discount to NTA"
On divestment validation: "In FY26, CIP divested $200 million of assets at an average 17% premium to book value... We view this as powerful third party validation of the portfolio's carrying values"
On embedded rent reversion: "We estimate the portfolio was approximately 17% under-rented on average, providing a significant runway for future earnings growth beyond FY27"
On the FY27 guidance swing factor: "The range that we have provided for FFO guidance is pretty much dependent on the leasing of Bundamba and Fairfield, we have forecast that will be leased in the second half of FY 2027"
On the data centre strategy: "CIP's strategy is to generate real estate returns from the data center opportunity without operating risk. CIP does not operate data centers, it owns and leases the underlying data center assets"
On unrecognised data centre value: "Management believes a significant portion of the future data center optionality is not reflected in current carrying values or in the REIT's current market value"
On the buyback versus rising debt costs: "With the rise in debt cost, it is not as accretive to earnings as it once was when we contemplated commencing the buyback 12 months ago"
Company page: Centuria Industrial REIT (CIP)
Helia leans on portfolio resilience and capital returns as new business shrinks
[12:11 pm] Management framed the H1 call around a resilient in-force book, disciplined cost-out and continued capital returns, against a tougher new business backdrop.
On the result: "Helia has delivered another strong result in a more challenging operating environment, and this reflects the resilience of the in-force portfolio, continued cost discipline and very strong balance sheet"
On the GWP slump: "GWP was A$61.6 million, down 44% on 1H 2025 mainly driven by the loss of CBA new business from January 2026 and softer first home buyer volumes following the expansion of the government's 5% deposit scheme"
On the government scheme: "Helia continues to advocate for a more targeted government scheme, one that directs public support to borrowers who need it most, while operating alongside a sustainable private LMI market"
On claims and equity protection: "What gives us comfort is that the house price appreciation across those high delinquency years have been material providing significant positive equity protection"
On deliberate reserving caution: "Experience continues to be very favorable. We are deliberately being cautious in the business given the environment and the outlook... it was somewhat of a balancing act between continuing very favorable experience but recognizing the environment does look more challenging"
On the claims lag before losses emerge: "First of all got to come through the delinquency. Second precondition is that typically you've then got to have house price depreciation that takes the policy into negative equity and then there's an actual loss"
Company page: Helia Group (HLI)
Gold miners now up 25% in eight days
[11:49 am] The All Ords Gold Miner Index is up 2.4% to the highest since 22 April and just above breakeven year-to-date. The index is on track to record an eight-day win streak, taking gains to 25%.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
NEM | Newmont | 5.1% | $167.58 | 23.6% | 11.6% |
RSG | Resolute Mining | 4.6% | $1.18 | 27.9% | -3.9% |
BGL | Bellevue Gold | 3.4% | $1.60 | 25.3% | -5.5% |
EMR | Emerald Resources | 3.2% | $6.71 | 25.2% | 6.8% |
GMD | Genesis Minerals | 3.1% | $7.56 | 29.2% | 5.6% |
CMM | Capricorn Metals | 3.0% | $16.51 | 27.9% | 17.9% |
VAU | Vault Minerals | 2.7% | $6.18 | 25.1% | 13.6% |
EVN | Evolution Mining | 2.3% | $14.04 | 22.1% | 11.7% |
ALK | Alkane Resources | 2.0% | $1.61 | 21.3% | 20.8% |
RMS | Ramelius Resources | 1.9% | $3.77 | 20.1% | -7.8% |
NST | Northern Star Resources | 1.8% | $23.43 | 17.3% | -4.6% |
RRL | Regis Resources | 1.8% | $7.58 | 23.8% | 0.7% |
PRU | Perseus Mining | 1.7% | $5.70 | 17.4% | 3.4% |
SBM | St. Barbara | 1.7% | $0.61 | 31.5% | 5.2% |
WGX | Westgold Resources | 1.5% | $5.90 | 23.1% | -6.4% |
BC8 | Black Cat Syndicate | 1.3% | $1.13 | 23.5% | -7.0% |
OBM | Ora Banda Mining | 0.5% | $1.37 | 17.3% | -10.3% |
PNR | Pantoro Gold | 0.0% | $2.58 | 26.5% | -47.3% |
CYL | Catalyst Metals | -0.2% | $6.53 | 12.0% | -11.5% |
AMI | Aurelia Metals | -1.3% | $0.38 | 15.2% | 55.1% |
MEK | Meeka Metals | -2.6% | $0.11 | 27.3% | -58.5% |
Thinking out loud on the Austal deal: is Hanwha offering nearly the whole company for two-thirds of it?
[11:46 am] Some napkin maths on why the Hanwha proposal for Austal USA looks compelling.
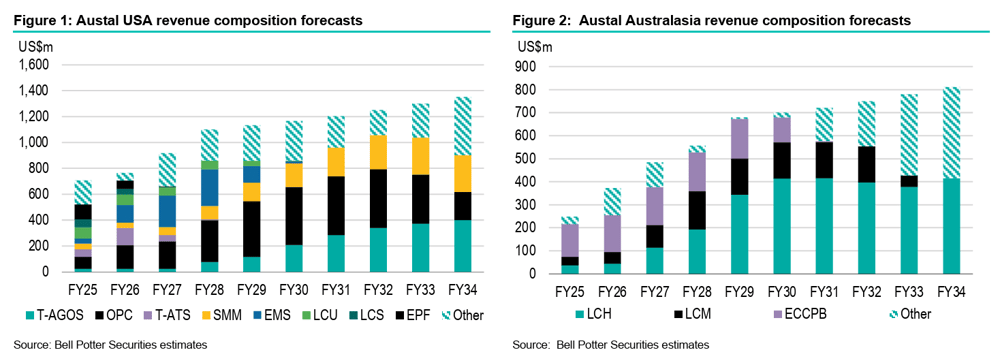
The offer midpoint is US$1.125bn EV or ~A$1.6bn at today's exchange rate, vs. a market cap of ~$1.88bn even after today's 15.8% rally, so the midpoint is around 85% of the entire group and the top end effectively equals the whole company
Bell Potter's estimates (below) note that Austal USA does around two-thirds of group revenue, so being offered close to the full market cap for two-thirds of the business sounds like a strong deal
Note that enterprise value is not proceeds, as the cash and debt-free basis plus tax and transaction leakage means what lands for shareholders is probably less than the headline
Austal jumps on Hanwha offer while Life360 and Amotiv slide
[11:37 am] A round-up of how today's reporters are trading after their results and announcements.
Austal (+15.8%): rallies as the market backs the Hanwha offer for its US operations at an indicative US$1.05-1.20bn enterprise value, with investors looking through the non-cash Austal USA provisions that swung group FY26 EBIT to a $(113)m loss
Helia Group (+8.1%): climbs despite H1 underlying NPAT falling 16%, with the 27c special dividend and further $75m buyback outweighing the 44% slump in gross premiums written
SGH Limited (-10.9%): sells off even after delivering FY26 earnings in line with guidance, as revenue and underlying NPAT came in modestly below ests and FY27 EBIT guidance of flat to low single-digit growth undershot the +3.7% consensus
Amotiv (-12.2%): falls despite an 11% underlying EBITA beat, with only modest FY27 revenue and EBITA growth guided and subdued ANZ conditions weighing on sentiment
Life360 (-13.4%): drops despite a Q2 revenue and EBITDA beat, as a further deceleration in MAU growth to 16% and a heavily Q4-skewed margin guide left analysts unconvinced the company can reaccelerate to its 20% MAU growth target
Life360 flags Q4-skewed second half as advertising seasonality and marketing spend shape margins
[10:33 am] Life360 is trading sharply lower after the earnings call flagged softer-than-expected Q3 margins and a big second half skew.
On the Q3 margin: "We expect Q3 adjusted EBITDA margin of approximately 18%, showing continued sequential improvement from Q2, while excluding the tariffs benefit."
On Q4 margin: "We expect Q4 2026 adjusted EBITDA margin to exceed the 22% margin we delivered in Q4 2025."
On why full-year guidance held: "While advertising is building as we expected, we do recognise that there is really elevated seasonality... and that does create a little bit of a higher risk, and that is why we are leaving revenue and adjusted EBITDA guidance unchanged."
On advertising seasonality: "We do look to Q4 as being this sort of seasonally high period in the advertising business. We have said before that we expect Q4 revenue to be approximately double that of Q1."
On the Q3 marketing step-up: "Q3 is typically our larger marketing period as we really support the back to school... We did lay off a little in Q2 and have pushed that into Q3."
On subscription margin stability: "The subscription revenue margins are very stable. In fact, we've managed to push them up a couple of points in the last couple of quarters, and they are very stable and not really subject to seasonality."
On the MAU trajectory into the second half: "We left it a wide range on purpose because we got a slow start to the year. We feel really good about our pace coming out of that. We feel like we are on track to get in that range."
Top ASX 200 gainers and losers
[10:25 am] Energy stocks open broadly higher, Helia rallies on a slightly better-than-expected dividend and narrowed 2026 guidance and Austal gaps up after receiving a US$1.2 billion takeover offer for its US shipbuilding business. Meanwhile, Life360 tanks on a poor Q3 margin guidance and SGH dips on a broadly weaker-than-expected FY26 result and FY27 guidance.
Ticker | Company | % Chg | Price |
|---|---|---|---|
HLI | Helia Group | 8.79% | $5.57 |
ASB | Austal | 7.03% | $4.11 |
KAR | Karoon Energy | 5.17% | $1.73 |
BPT | Beach Energy | 5.09% | $0.87 |
NEM | Newmont | 4.35% | $166.43 |
STO | Santos | 3.79% | $7.94 |
AAI | Alcoa Corporation | 3.45% | $74.00 |
CSC | Capstone Copper | 3.34% | $16.07 |
VEA | Viva Energy Group | 3.04% | $2.71 |
RMD | Resmed | 3.02% | $31.00 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
360 | Life360 | -14.69% | $25.15 |
SGH | SGH | -8.37% | $42.46 |
ARF | Arena Reit | -8.20% | $2.35 |
CAR | Car Group | -3.47% | $28.67 |
BOQ | Bank Of Queensland | -2.78% | $6.64 |
INA | Ingenia Communities Group | -2.48% | $4.32 |
DTL | Data#3 | -2.39% | $9.81 |
QAN | Qantas Airways | -2.30% | $10.21 |
4DX | 4DMedical | -2.05% | $4.31 |
SLX | Silex Systems | -1.97% | $4.97 |
Amotiv FY26 underlying EBITA beats on offshore growth and pricing
[9:45 am] FY26 underlying EBITA came in ahead of consensus on LPE offshore revenue and ANZ PTU growth, with statutory NPAT swinging back to profit after last year's impairment.
Revenue up 2.7% to $1.02bn vs. $1.03bn ests (in line)
Underlying EBITA up to $195.1m vs. $176.5m ests (11% beat), in line with guidance
Underlying NPAT of $120.3m versus $119.1m a year ago
Final DPS of 23 cents fully franked vs. 22 cents a year ago, with total cash returned to shareholders of $74.8m and leverage lower at 1.85x on 93.1% cash conversion
Gross margins of 42.8%, down 1ppt, with pricing actions improving margins through H2, and ROCE up 0.3ppt to 13.4%
FY27 guidance is for "modest" revenue and underlying EBITA growth, with offshore revenue, pricing and Amotiv Unified offsetting subdued ANZ conditions, versus ests of 2.6% revenue growth.
Company page: Amotiv (AOV)
Helia H1 underlying NPAT falls 16% as GWP slumps on structural headwinds
[9:43 am] First half underlying NPAT fell on a sharp drop in gross premiums written, with a lower claims ratio and a special dividend partly cushioning the result.
Underlying NPAT down 16% to $106.3m from $126.1m a year ago
Gross premiums written down 44% to $61.6m vs. $71.6m Macquarie ests (14% miss), hit by the Government 5% Deposit Scheme and lender self-insurance
Insurance revenue down to $170.6m, in line with $171.4m Macquarie ests
Total incurred claims ratio improved to (8.0%) from (14.8%) a year ago, aided by a favourable claims environment
Interim DPS of 16 cents fully franked plus a 27c unfranked special vs. Macquarie's ests of 16 cents plus 25 cents special
A further buyback of up to $75m
FY26 insurance revenue guidance narrowed to $330-360m from $320-370m, with the claims ratio reaffirmed well below the through-the-cycle average
Company page: Helia Group (HLI)
Charter Hall Social Infrastructure REIT confirms no FY27 guidance impact from Edge Early Learning
[9:39 am] CQE has confirmed limited exposure to troubled tenant Edge Early Learning and reaffirmed its FY27 earnings and distribution guidance. The stock
Three South Australian properties are leased to Edge, representing about 1% of CQE's total income, and continue to operate
CQE holds bank guarantees equivalent to six months' net rent on these properties, with management working towards a commercial outcome
FY27 earnings and distribution guidance provided on 4 August is unchanged
Active portfolio curation has upweighted income from non-early learning assets to 39% across the $2.3bn, 295-asset portfolio
The update follows an Arena REIT release noting Edge had requested rent deferral or abatement in late July as it pursues a corporate restructure
Company page: Charter Hall Social Infrastructure REIT (CQE)
Centuria Industrial REIT FY26 results
[9:29 am] FY26 Funds From Operations (FFO)landed just above the Morgans forecast on strong rental growth and premium divestments, with FY27 FFO guidance implying stronger-than-expected growth.
FFO up 3% to $114.1m
FFO of 18.2 cps vs. Morgans ests of 18.4 cps (1% miss) and towards the lower end of company guidance of 18.2-18.5 cps
Distribution of 16.8 cps, in-line with Morgans ests
NTA of $4.01 per unit vs. $3.95 Morgans ests and trading price ~25% discount to NTA
FY27 FFO/unit guidance of 18.8-19.2 cps
FY27 DPU guidance of 17.3 cps vs. 17.1 ests (1.1% beat)
Company page: Centuria Industrial REIT (CIP)
Austal receives Hanwha offer for US business as USA contract provisions swing group to a loss
[9:27 am] Austal has confirmed a non-binding offer from Hanwha for its US operations, alongside a trading update revealing a large non-cash provision at Austal USA that swings FY26 group EBIT to a loss.
Hanwha has offered an indicative enterprise value of US$1.05-1.20bn for Austal USA on a cash and debt-free basis, excluding Austal's listed shares and its Australasia operations
FY26 group EBIT now expected to be a loss of approximately ($113m), down from prior guidance of about $110m, driven solely by the Austal USA provisions
Austal USA expects an EBIT loss of approximately ($(175m) after booking all forecast losses on its T-ATS, AFDM and LCU programs through to completion, a non-cash accounting outcome
Australasia operations remain strong with expected FY26 EBIT of approximately $62m, and the sovereign shipbuilding mandate is unaffected by the proposal
Balance sheet remains robust with $366m cash at bank and a $240m net cash position at 31 July, plus $435m undrawn facilities, supporting a record $17bn order book
The Austal Board has granted Hanwha a four-week due diligence period to firm up a more certain proposal, with no certainty a deal will result.
Company page: Austal (ASB)
Macmahon wins $406m underground mining contract
[9:25 am] Macmahon has been awarded a five-year underground mining services contract worth an estimated $406.2 million at the Snowy River gold project near Reefton in New Zealand, operated by Endura Mining subsidiary Tasman Mining.
The contract commences October 2026, covers mine development, production and backfill operations, and marks Macmahon's return to mining in New Zealand ahead of the project's first gold slated for December 2026.
Company page: Macmahon Holdings (MAH)
SGH delivers FY26 growth and margin expansion in line with guidance
[9:19 am] FY26 earnings grew in line with guidance on margin expansion at Boral and WesTrac, with revenue and NPAT slightly below ests, plus a $500m buy-back announced.
Revenue down 2% to $10.56bn vs. $10.72bn ests (1% miss)
Underlying EBIT up 1% to $1.55bn vs. $1.58bn ests (2% miss), with margin up 40bp to 14.7%
EBITDA up 2% to $2.08bn vs. $2.10bn ests (1% miss)
Underlying NPAT flat at $920m vs. $949.4m ests (3% miss)
Final DPS of 32 cents fully franked, taking full-year dividends to 64 cents, up 3%
FY27 guidance is for flat to low single-digit EBIT growth, versus ests of 3.7%
Overall, this looks like a fairly soft FY26 result. The full-year dividend of 64 cents is just shy of Macquarie's 65 cents estimate, and FY27 EBIT guidance of flat to low single-digit growth is a miss vs. their ests of 5.8%.
Company page: SGH Limited (SGH)
Southern Cross FY26 NPAT misses on tough ad market
[9:17 am] FY26 revenue fell on a contracting TV and audio market, with underlying NPAT well short of ests, though cost discipline and merger synergies delivered EBITDA above revised guidance.
Gross revenue down 4.5% to $1.87bn, in line with ests
EBITDA (ex-items) down 15.8% to $191.9m vs. $187.6m ests (2% beat)
NPAT (ex-items) of $42.8m vs. $53.0m ests (19% miss)
Advertising revenue down 4.8% to $1,666.7m as the TV market contracted 9.9% and metro audio fell 6.8%, partly offset by share gains
Group digital revenue up 11% to $320m, with audio digital growth outpacing broadcast decline for the first time, and reported leverage at 1.8x
Merger synergies of $30m delivered a year early, with an expanded program now targeting $145-150m of annualised savings
Q1 FY27 has TV revenue tracking flat year-on-year, audio up low single digits and publishing stable, though conditions are expected to stay subdued
Company page: Southern Cross Media Group (SXL)
Life360 Q2 EBITDA smashes expectations on advertising surge
[9:12 am] Q2 revenue and adjusted EBITDA beat as the company crossed 100 million monthly active users, with advertising revenue up more than fourfold and FY26 guidance reaffirmed.
Revenue up 38% to US$159m vs. US$156.5m ests (2% beat)
Adjusted EBITDA up 53% to US$31.1m vs. US$25.5m ests (22% beat)
Adjusted EBITDA margin of 19.6% vs. 16.3% ests (330 bp beat)
Subscription revenue up 31% to US$115.6m, with advertising revenue up 315% to a record US$22.0m
Global MAU of 102.4m, up 16% year-on-year, in line with ests
FY26 guidance reaffirmed at US$650-685m revenue (midpoint 1% below US$671.8m ests) and US$130-140m adjusted EBITDA (midpoint in line with US$135.6m ests)
Interestingly, Nasdaq-listed Life360 shares are down 25.4% after hours despite all numbers reading ahead or in-line with market expectations.
Company page: Life360 (360)
Chrysos' PhotonAssay adoption drives 68% EBITDA growth
[9:07 am] FY26 revenue and EBITDA landed at the upper end of guidance on record sample volumes, though NPAT missed on higher costs, with FY27 guidance framing another year of strong growth.
Revenue up 33% to $88.1m, in line with ests of $89.2m and at the upper end of the $80-90m guidance range
EBITDA up 68% to $27.2m, just shy of ests of $27.7m and topping the $20-27m guidance range
NPAT of $1.8m, 31% below ests of $2.6m
24 new lease agreements signed in FY26 plus four post-period, taking total contracted units to 87, with sample volumes up 67% to a record 11.3 million
Operating cashflow positive with $17.9m net inflows, and funding strengthened to $25.9m cash plus $140m undrawn debt
FY27 guidance of $108-118m revenue and $35-42m EBITDA, vs. ests of $113.8m and $40.2m (1% and 4% miss respectively)
Company page: Chrysos Corporation (C79)
RBA set for hawkish hold with tightening bias intact
[9:05 am] The RBA is expected to hold the cash rate at 4.35% for a second straight meeting today, while keeping the door open to further hikes as core inflation stays sticky.
Economists and traders expect the cash rate held at 4.35%, with focus on updated quarterly forecasts for signs the board is done after 75 basis points of hikes this year
The trimmed mean gauge has stayed above the 2-3% target midpoint since late 2021, with Australia's core inflation among the highest in major developed economies
Money markets are pricing around a 60% chance of a hike by December, with AMP's Shane Oliver tipping one more move by year-end
Unemployment sits at 4.4% vs. the RBA's May forecast of 4.2%, though the past two reports showed strong hiring
Source: Bloomberg
Brent rallies, S&P 500 Energy sector posts best day of the year
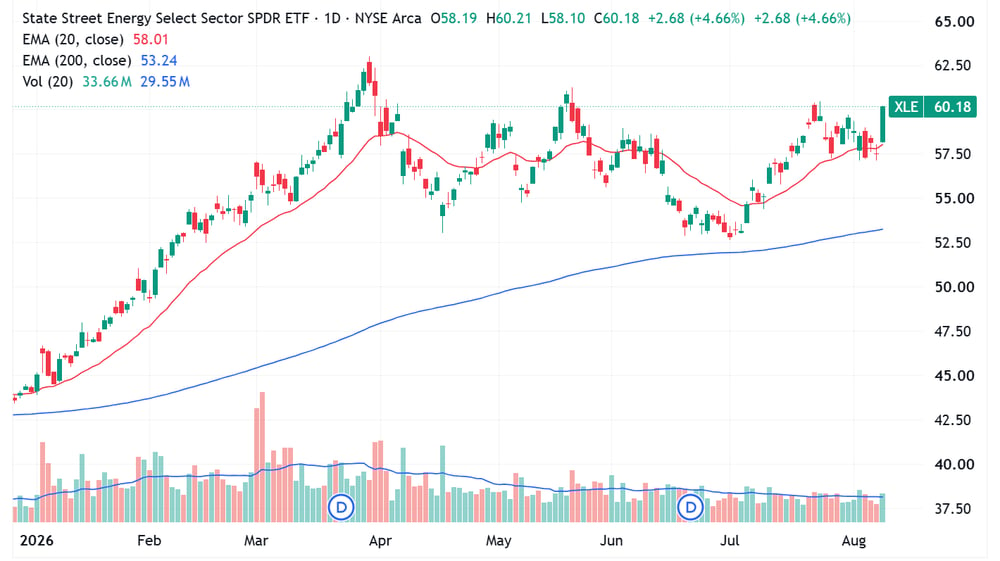
[8:58 am] Brent rallied 6.6% overnight to US$87.87 a barrel, now up 11.6% in the last four sessions, but still down 13.7% from the recent 23 July high (US$102).
The S&P 500 energy sector (+4.6%) posted its best day of the year. It's an interesting relationship here, where Energy equities have refused to underwrite the geopolitically-driven spike in oil prices, but even at US$80 a barrel plenty of these names are printing free cash flow yields into the mid-teens, which argues for a higher valuation. With no end in sight to the US-Iran negotiations, energy stocks are slowly but surely closing in on recent highs, even with oil trading well below its late-March peak of US$120.
S&P 500 Energy sector daily price chart (Source: TradingView)
US-Iran Hormuz talks stall on hardening demands
[8:54 am] Crude rallied after both sides piled on new conditions, with Trump now seeking compensation from Tehran and Iran tying any reopening of the strait to the US lifting its blockade, dimming hopes of a quick deal.
Iran demanded the US lift its naval blockade, withdraw forces from its vicinity and permanently end the war before reopening the strait
Trump demanded compensation from Iran for people killed by its roadside bombs and conflicts, later expanding it to Lebanon, Syria, Yemen and Gaza
Trump signalled a "low-key" approach, favouring economic pressure over fresh strikes, pointing to Iran's 77% inflation and a rial down more than 10% from prewar levels
Iran's oil exports have decelerated sharply, with Kpler estimating flows down roughly 40% this month versus July to about 500,000 barrels a day as the blockade keeps terminals idle
US Strategic Petroleum Reserve has fallen below 300 million barrels for the first time since 1983 as the conflict drags on
Supreme Leader Mojtaba Khamenei reshuffled military leadership with six senior appointments and decrees calling for readiness for offensive operations, seen as a shift to a more hawkish stance
Nvidia lines up US$500bn to make its AI chips a financeable asset class
[8:49 am] Nvidia has teamed with six Wall Street asset managers on a financing push designed to let customers borrow against compute the way they would against real estate or toll roads.
Nvidia signed MOUs with Apollo, Blackstone, BlackRock, Brookfield, Goldman Sachs and KKR to build financing platforms for its customers
The effort aims to mobilise more than US$500bn in third-party capital for hyperscalers, frontier AI labs and enterprises to build data centres and buy Nvidia hardware
The structure lets end users secure financing without tapping their own balance sheets, using institutional credit, insurance and private capital to underwrite GPUs
Huang called it the first time technology chips have become an investable asset class, arguing broad adoption and transferability let lenders treat compute as revenue-generating and long-lived
BlackRock's Fink likened it to the birth of mortgage-backed securities in the 1970s, while Blackstone's Gray said AI use across portfolio companies has surged sevenfold this year
EM stock valuations sink below half the S&P 500's for first time in decades
[8:48 am] Emerging-market equities are now valued at less than half US multiples, prompting some investors to hunt for value beyond the AI-heavy names, particularly in Latin America.
The MSCI EM Index trades at 9.9x forward earnings vs. more than 20x for the S&P 500, the first time in at least two decades the gap has been this wide
The record discount reflects the US AI bull market and deepening China and Hong Kong underperformance, with those two more than a fifth of the EM benchmark
MSCI EM has rallied 19% this year, mostly from SK Hynix, Samsung and TSMC, but has risen just 3% since late February vs. 13% for the S&P 500
Valuations are widely dispersed, with Taiwan, India and Hong Kong tech at 17-18x while Brazil sits at 8.2x, Argentina 8.6x, Philippines 9.5x, Egypt 8x and Turkey 4x
Source: Bloomberg
Goldman's Varadhan says stay invested, sees three tailwinds
[8:48 am] Goldman's co-head of global banking and markets is telling worried investors to stay in the market, pointing to steady rates, potential AI disinflation and lower oil.
Varadhan does not expect the Fed to hike in the latter half of this year, seeing rates staying on hold against market pricing that reflects some tightening risk
He sees oil settling well below US$70 a barrel, maybe lower, by late 2026, easing inflation pressure, though WTI climbed back above US$80 Monday on doubts over a US-Iran Hormuz deal
AI should eventually turn disinflationary as the infrastructure build-out gives way to productivity gains, even if the near-term capex strains resources
He stays constructive on credit, with economic strength keeping spreads contained and expected defaults fairly low despite heavy issuance
Source: CNBC
JPMorgan lifts S&P 500 target to 8,000 as AI capex pays off
[8:47 am] JPMorgan has raised its year-end forecast for a second time in two months, citing strong earnings and evidence that hyperscaler AI spending is being monetised.
The Lakos-Bujas team lifted its target to 8,000 from 7,800, implying about 3% upside from Friday's close and sitting slightly above the average of 20 strategists polled by Bloomberg
Q2 earnings showed AI hyperscaler capex is being monetised through customer demand, with stronger cloud growth and rising backlogs at Alphabet, Amazon and Microsoft easing return-on-capital worries
As backlogs convert to recognised revenue, cloud growth should stay supported and help validate rising AI capex, the team said
S&P 500 earnings surged 32%, one of the best increases on record, as the index reclaimed record highs
Source: Bloomberg
US high-grade bond issuance hits fastest pace since January
[8:45 am] Nineteen companies stormed the US investment-grade market on Monday, the most in seven months, as companies rushed to raise capital ahead of this week's inflation data.
19 issuers ranging from utilities to overseas banks to Tyson Foods offered a combined US$27.6bn of notes, the busiest session since 20 deals priced on January 5
Borrowers moved ahead of US inflation reports due this week, with rate-hike bets pared after Friday's weak jobs report sending yields lower and opening a hospitable window
Last week saw US$80bn of supply, the third-highest of 2026, with dealers tipping a further US$40bn this week, well above August's post-2019 monthly average of US$95bn
US$1.4tn of high-grade notes have priced so far this year as of Friday, 9% above the 2020 pace which ended at a record US$1.75tn
Global issuance hit US$5tn on Monday, reaching the mark more than a month faster than last year's record
AI-related spending and active government sellers are fuelling supply, with Amazon the only corporate among the five largest syndicated bond issuers alongside Germany, France, Italy and the EU
Source: Bloomberg
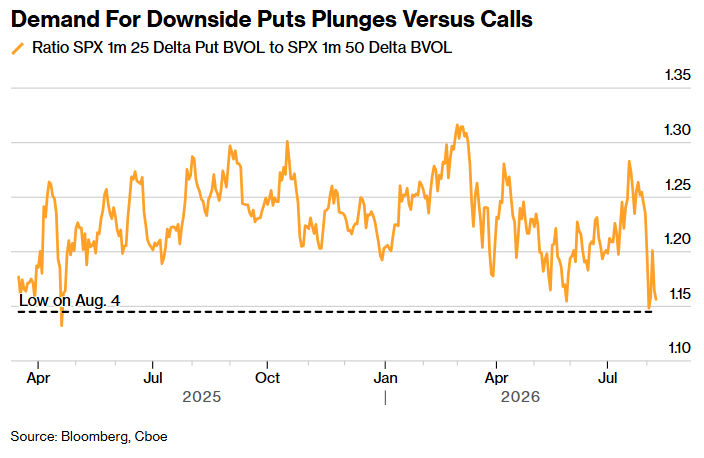
Downside protection dumped as traders chase the rally
[8:45 am] Demand for hedges against a stock market drop has slumped to its lowest since Trump's tariff backdown last year, as under-exposed investors rotate into upside calls to catch record highs.
FOMO takes over as Wall Street's rally driver
[8:41 am] Options-market signals are flashing their most bullish readings in years as under-exposed investors scramble for upside, prompting some to warn of overbought conditions.
The one-month average daily S&P 500 call-to-put ratio has risen to 0.9, among the most bullish readings in at least four years
Short-term S&P 500 call skew soared to a two-year high last week, reflecting investors paying up for bets on a fast, sharp rally, per Susquehanna
The Bullish Percent Index rose above 70%, pointing to overbought conditions, LPL Financial notes
Source: Reuters
Good morning!
[8:30 am] ASX 200 futures are down 3 pts (-0.03%). Here's what happened overnight:
Major US benchmarks stalled just under Friday's record, with the S&P 500 finishing flat as an oil-led energy rally offset weakness across AI infrastructure and mega-cap tech
S&P 500 (-0.06%), Nasdaq (-0.32%), Dow (-0.11%), Russell 2000 (-0.56%)
Nvidia signed agreements with six of the world's largest asset managers to mobilise more than US$500bn of third-party capital for AI infrastructure
Brent rallied ~6% to US$87 a barrel after Tehran said the Strait of Hormuz will not reopen until Washington meets its conditions, reviving inflation and Fed rate-hike concerns