ASX 200 Live Today - Thursday, 3rd September
The S&P/ASX 200 is on track to snap a three-day losing streak, though banks and miners are doing most of the heavy lifting.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Thursday, September 3. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 higher on bank and miner gains
[2:00 pm] The S&P/ASX 200 is trading 43 pts (+0.48%) higher, snapping a three-day losing streak, though it remains down ~0.8% for the week. It's not the most inspiring bounce, with banks and miners doing most of the heavy lifting. More encouragingly, yields are starting to pull back from multi-year highs. The Aussie 10-year is down 4 bps to 5.16% and the policy-sensitive 3-year is down 5 bps to 4.77%. That said, it's one of those slight pullbacks after a breakout, nice to have but hardly reassuring. Banks have lifted off recent lows and are now up 2.8% since 27 August, but still sit 7.5% below their 6 August record. Miners are trying to bounce too, though the past six sessions have been up-down-up-down, with the declines outpacing the gains. All up, things remain dicey at best against a backdrop of worrisome bond yields, high oil prices and weak seasonality.
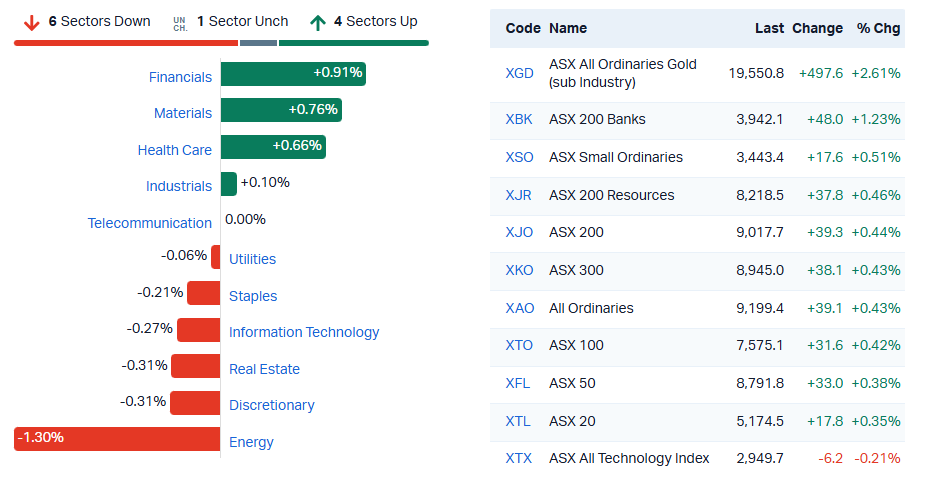
S&P/ASX 200 sectors and indices (Source: Market Index)
China's private services gauge rebounds against forecasts
[1:21 pm] The RatingDog survey pointed to a modest August recovery, though it sits at odds with the official reading and remains low by historical standards
The RatingDog China services PMI rose to 51.4 from 50.4 in July, comfortably above the 50 expansion line and ahead of the 50.6 median forecast
The official PMI showed services in contraction for a second month, with the two surveys differing on sample size, location and business type and the private survey focused on small and medium-sized firms
The reading remains low historically, having approached 57 earlier this year and averaged around 52 across 2024-2025
Employment expanded for a fourth straight month, the longest streak since 2023, and grew at one of the fastest paces in three years
Firms raised prices for a third consecutive month, the longest run in more than two years
Sample size limits the signal, with RatingDog polling 650 services firms against 4,300 non-manufacturing companies in the official survey, which has driven greater volatility in past readings
Source: Bloomberg
Base metals gain as Trump signals a short Iran campaign
[1:19 pm] All six main LME metals rose after the President said the new bombing campaign would not last long, unwinding some of Wednesday's risk-off move
Gold up 0.9% to US$4,426/oz, silver also up 0.9% to US$65.88/oz
Zinc added 0.9% to $3,880 a tonne and was among the leaders, having logged a fifth consecutive month of gains in August
Copper up 0.1% to US$6.61/lb, with a record high close notched last week
August strength was driven by signs of supply tightness, with aluminium and tin also rising in the latest session
Airstrikes on Iranian targets and Tehran's retaliation had triggered a rush from risk assets as crude spiked, before Trump said the campaign would not run "too long"
Banks and miners carry the ASX 200 higher
[11:59 am] The S&P/ASX 200 is up 25 pts (+0.28%) at noon, though a rather fragile bounce as banks and miners do most of the heavy lifting.
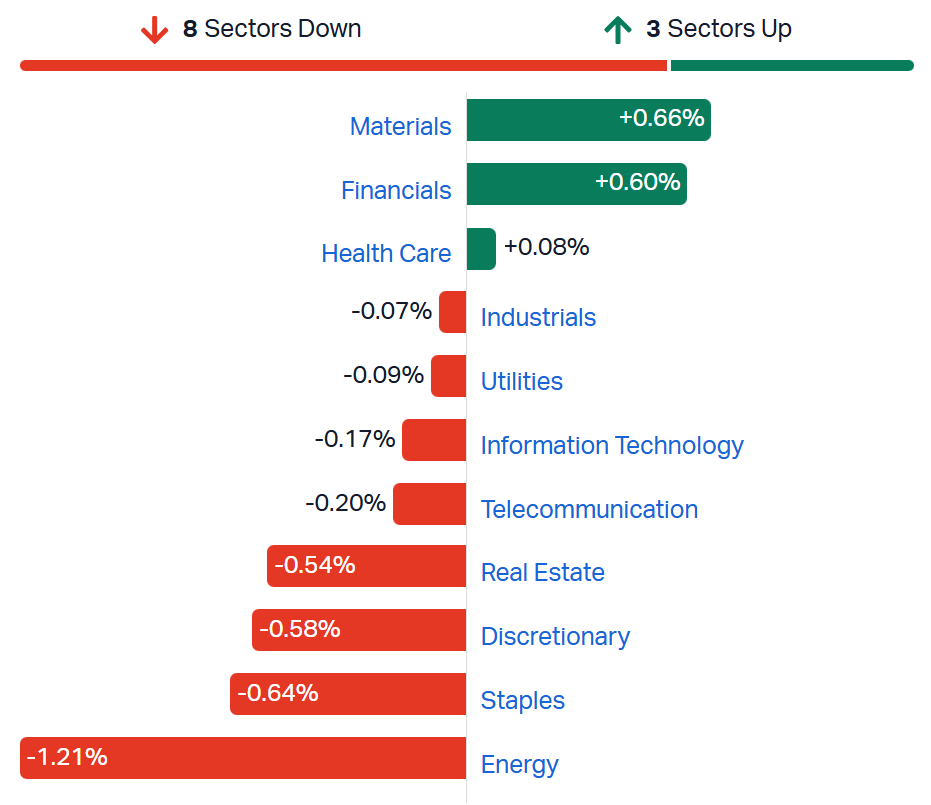
S&P/ASX 200 sectors (Source: Market Index)
BHP is trading lower, but most other major names across copper, gold, lithium and coal are higher. The All Ords Gold Index is up 2.6% after falling 6.6% across the prior three sessions.
Ticker | Company | % Chg | Price |
|---|---|---|---|
BHP | BHP Group | -1.13% | $63.92 |
CBA | Commonwealth Bank | 0.33% | $159.84 |
RIO | Rio Tinto | 1.80% | $178.03 |
NAB | National Australia Bank | 1.31% | $39.09 |
WBC | Westpac | 1.22% | $34.81 |
ANZ | ANZ Group | 1.49% | $38.07 |
MQG | Macquarie Group | 0.43% | $249.35 |
WES | Wesfarmers | -1.42% | $76.07 |
CSL | CSL | 0.01% | $173.87 |
WDS | Woodside Energy | -2.87% | $32.13 |
GMG | Goodman Group | 0.39% | $26.76 |
FMG | Fortescue | 2.83% | $17.08 |
Australia's July goods surplus narrows as coal and gold exports fall
[11:48 am] Bulk export volumes dropped sharply across the board in July, though coal and LNG unit values held up on a year-on-year basis, according to the ABS.
The seasonally adjusted goods balance decreased $418m in July, with exports down 3.3% or $1,576m and imports down 2.5% or $1,157m
Export weakness was driven by non-monetary gold and coal, while the import decline came from fuel and lubricants and non-monetary gold
Iron ore lump volumes down 21.5% month on month and fines down 9.5%, leaving lump down 9.5% through the year while fines were up 1.8%
Coal volumes fell across all grades, with hard coking down 19.5%, semi-soft down 20.6% and thermal down 15.8% in the month. Through the year, hard coking was up 8.8% while semi-soft and thermal were down 16.2% and 15.3%
LNG up 8.5% in the month and up 7.4% through the year, with unit values up 15.7% in July and 9.8% year on year
Unit values tell a different story to volumes, with hard coking coal up 21.9% and thermal up 23.7% through the year, while iron ore lump and fines fell 7.5% and 5.0%. Crude petroleum import unit values were up 33.3% year on year and diesel up 42.7%
Top ASX 200 gainers and losers
[10:26 am] Tech, copper, gold and lithium stocks are on the mend, while defence, staples and energy stocks retreat in early trade.
Ticker | Company | % Chg | Price |
|---|---|---|---|
XYZ | Block | 4.80% | $113.50 |
PRU | Perseus Mining | 3.58% | $6.66 |
RSG | Resolute Mining | 3.39% | $1.43 |
IGO | IGO | 3.37% | $8.60 |
GMD | Genesis Minerals | 3.21% | $8.35 |
360 | Life360 | 2.86% | $19.75 |
VAU | Vault Minerals | 2.79% | $6.82 |
FFM | Firefly Metals | 2.59% | $1.79 |
BSL | Bluescope Steel | 2.53% | $31.87 |
LYC | Lynas Rare Earths | 2.38% | $15.48 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
EOS | Electro Optic Systems | -4.79% | $8.95 |
NHF | Nib | -3.59% | $6.72 |
ASB | Austal | -2.86% | $4.07 |
WDS | Woodside Energy Group | -2.60% | $32.22 |
DRO | Droneshield | -2.33% | $1.68 |
COL | Coles Group | -2.22% | $23.36 |
LLC | Lendlease Group | -2.19% | $2.91 |
CNI | Centuria Capital Group | -2.05% | $1.20 |
GPT | Gpt Group | -1.93% | $4.57 |
LOV | Lovisa | -1.87% | $23.58 |
Japan's 30-year bond auction shapes as a test for global rates
[10:25 am] Thursday's sale lands with long-dated yields near two-decade highs and fiscal concerns building under Prime Minister Sanae Takaichi's expansionary agenda
The 30-year JGB yield has risen to 4.155%, near the highest since the tenor was introduced in 1999, while the benchmark 10-year hit 3% for the first time in three decades
Record budget requests from Japan's ministries for the next fiscal year have intensified scrutiny over financing and how much additional debt the government may need to sell
BOJ Governor Kazuo Ueda has hinted at a hike at this month's meeting, saying a decision will be made with upside price risks in mind, following comments from US Treasury Secretary Scott Bessent pointing to the need for action
Barclays expects a weakish-to-benign result, noting current levels are not far from fair value on long-term drivers but that fiscal concerns remain a drag. A 10-year sale earlier this week passed smoothly
The yield gap between Japanese and US long bonds risks slipping below 100bp, which would make Japanese debt more attractive on relative value and potentially add to selling pressure on Treasuries
Source: Bloomberg
Macquarie upgrades Paladin Energy to Outperform on PLS resource growth
[10:24 am] The analysts see Patterson Lake South as the bigger value driver now that Langer Heinrich has ramped, with recent Canadian drilling lifting confidence in resource growth
Upgrade from Neutral to Outperform, with the target price lifted 7% to $13.85, after the share price pulled back around 12% since the FY26 results presentation
PLS already screens larger than Langer Heinrich in Macquarie's valuation, with the gap expected to widen further on time passage and resource growth
Mining sequence clarified at PLS, initially targeting the higher-grade shallow R780E zone, with bulk freezing commencing in year four to mine those zones in year six
Resource upside flagged at Triple R, which remains open along strike and at depth, with historical drilling concentrated around 300m versus comparable regional deposits extending beyond 800m. RK1515W and RK1620E are not in the mine plan and could add 15+Mlbs to reserves over time
Atlas drilling has intersected high-grade mineralisation across all 25 holes, with step-out success pointing to a potential 20-40Mlb system, while Saloon East looks like a broad, lower-grade satellite
Earnings unchanged in FY27, down 0.1% in FY28 on a higher share count and up 2.2% in FY29 on lower interest expense, with the target incorporating a $500m equity raising late CY27
Company page: Paladin Energy (PDN)
Corporate Travel opens 81% lower
[10:22 am] Something touched my foot at the open. It might've been the candle from CTD's gap down. The stock opened 81.3% lower at $3.00 and is currently off its lows at $3.14. Here are few random observations:
The stock has shed almost $2bn in market cap (last traded at $2.35bn, now ~$460m)
The company said it had $106.9m cash at the end of FY26, plus a $175m committed funding package
Preliminary final report notes NTA of (-15) cents vs (-52) cents a year ago and $1.24 at Dec-24
We're 22 minutes into the session and volume sits at 4.48m (the highest since 21-Feb-24 when the stock tanked 20% on results)
Poll: How much does Corporate Travel fall today?
[9:36 am] Corporate Travel resumes trading this morning after a year-long suspension. Expect a wild and volatile session. Where do you think the stock closes today?
Fenix Resources delivers maiden Beebyn Hub Ore Reserve
[9:33 am] The combined reserve underpins the three-year production plan and gives more than five years of mine life at current rates
Maiden Beebyn Hub Ore Reserve of 26.9Mt at 60.0% Fe, comprising an updated Beebyn-W11 reserve of 13.1Mt at 61.2% Fe and a maiden Beebyn-W10 Stage 1 reserve of 13.8Mt at 58.9% Fe
The Hub combines the existing W11 mine with the fully approved W10 mine as a centralised mining and processing centre within the 290Mt Resource Weld Range Iron Ore Project
Supports the three-year plan to reach up to 6Mtpa from the Beebyn Hub by FY28, against a stated ambition to grow to 10Mtpa by 2031
W10 production on track to commence this quarter with first shipment expected in the December 2026 quarter, following receipt of all mining approvals in July
Separately reported resources of 19.7Mt at 61.0% Fe at W11 and 47.7Mt at 59.0% Fe at W10, both inclusive of Ore Reserves
Weld Range Definitive Feasibility Study is expected to materially boost Ore Reserves further, consistent with the December 2025 scoping study outlining a 10Mtpa profile out to 2042
Company page: Fenix Resources (FEX)
Vulcan Energy PFS shows better economics for second lithium phase
[9:32 am] Project Ludwig lands with lower capital intensity than Lionheart, supporting the case for a repeatable development platform in Germany's Upper Rhine Valley
Pre-tax NPV8 of €2.6bn and IRR of 25.0%, with post-tax NPV8 of €1.7bn and IRR of 20.2% across a 30-year planned operating life
Capital intensity cut 15% relative to Lionheart, with total capex of €1.26bn, reflecting Lionheart learnings and a simplified development concept
OPEX of €4,101/t LCE, placed in the lowest industry quartile on low-cost brine production and integrated heat generation
Base case production of 21,100tpa of battery-grade lithium carbonate, adding product flexibility alongside Lionheart's hydroxide, plus 3,125 GWh per annum of renewable heat for internal use and external sales
Indicated Mineral Resources up 91% to 1,251kt LCE at 155mg/l Li, with Inferred up 5% to 2,230kt LCE, and a maiden Geothermal Resource of 193 PJ Indicated and 295 PJ Inferred
Asset-level financing under way, with strategic partner selection commenced and FID targeted only after Lionheart starts up, part of a plan to add a new phase every two to three years
Company page: Vulcan Energy (VUL)
Welcome back Corporate Travel (goodbye share price)
[9:23 am] Corporate Travel is set to resume trading after a year-long suspension (last traded since 22-Aug-25). The ASX lifted its suspension last night after the company reported its FY26 result, which noted:
TTV up 2% to $9.8bn
Transaction volumes up 13% to 18.3m
Revenue and other income up 4% to $669.9m
Underlying EBITDA up 36% to $113.6m
NPAT of $17.7m against a $348.5m loss in FY25
Trading during the first month of FY27 remained broadly in-line with management expectations, TTV increased to 1.6m vs. 1.5m a year ago
Department of Finance review of CTD's management of the Whole of Australian Government Travel Arrangements, a coordinated procurement used by more than 150 Government entities, was released on 31 August 2026 and concluded there was no evidence of widespread or systemic overcharging
No broker research for CTD has crossed my desk this year. A slightly older note from Macquarie (28-Nov-25) was expecting FY26 underlying EBITDA of $199.6m and NPAT of $98.4m (might not be as relevant given all that's happened in the past few months). Given the governance issues, a year-long suspension and sector weakness (FLT and WEB down ~11% and ~18% respectively since last August), you'd expect an absolute purge in CTD shares this morning. The stock is currently down 50.2% in pre-market.
Explorer wrap: drilling results and target definitions across gold, silver and copper
[9:07 am] A run of exploration updates from ASX-listed juniors, spanning WA gold, Nevada silver-antimony, West African gold and Serbian copper.
Maritana Minerals (MRT): completed 119 holes for over 17,000m of RC drilling at Boorara, the first ore source for the Black Swan Processing Hub, with resource conversion drilling now underway at Coote and Crake and a fourth rig starting in September as it targets a mining restart mid-2027 and first processing in H2 CY2027
Sun Silver (SS1): returned 89m at 70g/t AgEq from 126.5m in MV0004 at Maverick Silver in Nevada, including 38.3m at 100g/t AgEq, with the same hole intercepting cumulative antimony mineralisation exceeding 100m starting roughly 60m above the current resource
Corazon Mining (CZN): defined a maiden Exploration Target of 9.7–12.3Mt at 1.9–2.1g/t Au for approximately 600,000–830,000oz at Chalice near Higginsville, inclusive of the existing 191,000oz resource, with an initial 7,500m RC program due to start in coming weeks
Many Peaks Minerals (MPK): hit 36.0m at 2.64g/t gold from 600m in FNDC135 at Ouarigue in Côte d'Ivoire, with assays pending from a further 27 diamond holes and 65 RC holes ahead of an MRE update using a drilling cut-off around the end of Q3 2026
Middle Island Resources (MDI): defined copper-in-soil anomalies of 900m x 400m at Jelaca and 600m x 400m at Oglavak in Serbia, with rock chips grading up to 3.21% Cu and 26.0g/t Ag as it tests the Priboj area for VMS-style copper
Company pages: Maritana Minerals (MRT), Sun Silver (SS1), Corazon Mining (CZN), Many Peaks Minerals (MPK), Middle Island Resources (MDI)
Australian earnings beat estimates for the first time in four years
[8:57 am] Beats outnumbered misses through August reporting season, though whether that revives the stalled rally now hinges on guidance
Almost half of ASX 200 companies reported better-than-expected profits, with beats outnumbering misses by 1.5 times, the first time in four years
The benchmark hit a record high in early August before paring gains to finish the month up 1.1%
Beaten-down names stood out, with residential developers and discretionary retailers including Super Retail Group posting earnings growth despite softer consumer conditions, and turnaround progress rewarded at CSL, Treasury Wine Estates and ASX
Sector split was clear, with banks, consumer discretionary and property pressured by softer housing conditions, while miners, energy producers and healthcare names with offshore exposure fared better
BHP and Rio Tinto benefited from surging copper prices tied to the AI buildout, while Woodside and Santos posted stronger earnings as the Middle East conflict lifted energy prices and LNG revenue
Source: Bloomberg
JPMorgan's Peters flags 5% yields as the key risk to equities
[8:56 am] JPMorgan's global head of investment strategy still sees upside for US and European stocks this year but expects a pullback into November's midterms
10-year Treasury yields at 4.8% on fears rising oil prices will fuel inflation, with the 30-year at a 19-year high and growing speculation policymakers will be forced to raise rates
A move to 5% could trigger a knee-jerk equity reaction, with Peters pointing to September seasonality, the midterms and the fact the Q2 earnings catalyst has passed
A 5-8% correction is possible, which Peters characterises as a healthy pullback rather than a structural breakdown
Q2 earnings growth of 30% in the US and around 15% in Europe is unsustainable and should taper, though breadth across financials, industrials and utilities points to a healthier market than one led by technology alone
Capex supercycle driving an earnings supercycle remains the core thesis, with the US the preferred equity region alongside emerging markets and Europe neither winning nor losing
Utilities preferred alongside financials and technology, with power constraints and memory chip shortages flagged as potential binding limits on AI expansion, and proving return on AI investment the medium-term test
Source: Bloomberg
Williams says yield surge reflects a strong economy, not dysfunction
[8:56 am] The New York Fed president is taking a wait-and-see approach to whether a rate hike is needed, with markets pricing roughly 66% odds of a move on 15-16 September
Treasury yields at multiyear highs, particularly at the long end where investors price inflation and growth expectations, which Williams attributes to economic strength rather than market dysfunction
AI and data centre investment is a large part of what is driving the move, with Williams framing it as the economy affecting financial conditions rather than the reverse
No commitment on a September hike, with Williams saying there are no clear signs on whether current policy is sufficient to return inflation to target within one to two years
Recent inflation data described as encouraging, though he cautioned against reading too much into a month or two
Inflation expectations remain well anchored in his view, despite this year's tariff and Iran war-linked price pressures
Source: CNBC
Lutnick flags fresh chip tariffs paired with relief for US builders
[8:55 am] Washington is weighing another round of semiconductor levies, structured to reward companies that commit to domestic manufacturing
New chip tariffs under consideration, likely paired with tariff relief for companies investing in US manufacturing, mirroring the approach already applied to pharmaceuticals
Existing levies sit at 25% on certain advanced semiconductors, imposed in January after a Commerce Department probe
A new round could extend beyond chips to products containing them, hitting imports of data centre servers and consumer electronics
$1.2 trillion in US semiconductor build commitments has already been pledged, including from TSMC and Micron, helped by the US-Taiwan trade pact under which Taiwan committed around $500bn in investments and credit guarantees
A further $20–30bn of Taiwanese commitments is due to be announced next week
Critics warn the additional tariffs could raise the cost of building US data centres, though Lutnick framed the relief mechanism as the offset
Broadcom targets 4x AI revenue by FY28, shares slip on Q4 guide
[8:50 am] The chipmaker beat on Q3 but laid out an AI roadmap that dwarfs the quarterly result, taking AI semiconductor revenue from $58bn in FY26 to $230bn in FY28. The stock is trading 1.6% lower after hours.
Revenue up 86% to $29.6bn vs $29.36bn ests (1% beat)
Adjusted EPS up 96% to $3.32 vs $3.24 ests (2% beat)
AI semiconductor revenue up 221% to $16.7bn, with XPU shipments up 3.5x and making up 73% of Q3 AI revenue
Non-GAAP operating income up 92% to $20.1bn vs $19.73bn ests (2% beat)
Q4 revenue guidance of around $34.8bn came in slightly below ests, sending shares lower, with Q4 AI revenue guided to $21.7bn, up 236%
FY27 AI revenue targeted at around $115bn and FY28 at around $230bn, with supply secured for both years and current demand already exceeding the 2027 outlook. Management is also targeting more than $30 EPS in FY28
Some interesting quotes from management:
On demand: "AI demand is simply hot, and we're just getting started"
On 2027 supply: "In 2027, we have secured the supply to double AI rev to about $115 bn"
On the $350bn shipment target: management has a "high degree of confidence" it will ship $350bn of AI semis over the next two years, even if all 30 GW of demand is not deployed due to land, power and data centre constraints
Snowflake beats on revenue and earnings, lifts FY27 guidance
[8:49 am] The cloud-based AI data company reported its third consecutive quarter of product revenue growth acceleration, with management pointing to a step-up in AI revenue. Snowflake shares are up 22.2% after hours.
Revenue up 35% to $1.55bn vs $1.48bn ests (5% beat)
Product revenue up 37% to $1.49bn, with remaining performance obligations up 30% to $9.0bn
Non-GAAP operating income of $237.0m vs $187m ests (27% beat), non-GAAP product gross margin of 75%
Adjusted EPS of $0.62 vs $0.45 ests (38% beat)
Free cash flow of $83.8m vs $104m ests (19% miss)
FY27 product revenue guidance lifted to $6.07bn from $5.84bn, implying 36% growth, with non-GAAP operating margin raised to 14.5% from 13.5%
Q3 product revenue guidance of $1.588–1.593bn and non-GAAP operating margin of 15.5%
et revenue retention
of 126%, with customers spending more than $1m up 27% to 828
Oil near US$90 as US-Iran strikes reignite over Hormuz
[8:45 am] A month-long lull in the Iran war has broken, with tanker attacks, a US naval blockade and fresh sanctions all bearing on the world's most important oil chokepoint
Brent finished flattish at US$95.37 after a +/-2% move intraday
Energy Secretary Chris Wright said more than 17m barrels of oil transited Hormuz on Monday, a wartime record, against roughly 20m bpd of crude and products before the 28 February attacks
Kpler data tells a different story, with six ships crossing the strait on Tuesday, down from 19 the previous Friday and 138 in a typical 24-hour period pre-war. The US government has consistently reported higher volumes than independent ship trackers
Shipping risk is rising, with two tankers halted after striking mines, a Saudi carrier attacked with two crew killed, and CENTCOM reporting 86 commercial vessels redirected, three disabled and two boarded as of 2 September
The US struck two Iranian government tankers on Tuesday under a new "tanker for tanker" policy, the first retaliatory strikes on Iranian vessels rather than blockade enforcement
Treasury Secretary Scott Bessent has launched "Operation Economic Outcast", targeting countries and entities still trading with Iran, with the UAE telling Washington any effective campaign must capture all major Iranian trade partners
Good morning!
[8:32 am] ASX 200 futures are up 38 pts (+0.42%). Here's what happened overnight:
Major US benchmarks snapped a three-day losing streak as the 10-year Treasury yield backed off a fresh post-2023 high, with Nvidia (+3.2%), Micron (+2.4%) and Meta (+2.4%) leading megacaps
S&P 500 (+0.46%), Equal-weight S&P 500 (+0.46%), Nasdaq (+0.45%), Dow (+0.56%), Russell 2000 (+1.13%)
Brent settled flattish after rallying ~10% in the prior five sessions. Trump floated renaming it after himself, while the IRGC said two tankers struck mines and the US hit Iranian government tankers under a new "tanker for tanker" doctrine
Snowflake lifted full-year product revenue guidance and jumped in extended trade, Dell drew a wave of target upgrades on its record AI server backlog, and Bloomberg reported Nvidia nearing a $12.9bn deal for Hugging Face