What happens if one of the ASX’s fastest-growing sectors starts to slow?
Data centre contractors rallied on booming earnings. Four setbacks in just two weeks have now wiped 20-30% off most names.
Source: iStock
Mentioned
KEY POINTS
- A withdrawn Firmus IPO, a delayed AirTrunk float, CoreWeave credit stress and a NextDC downgrade have wiped 20-30% off most data centre contractors like SKS Technologies and Southern Cross Electrical
- Data centre wins have supercharged earnings for these pick-and-shovel plays. But valuations have expanded even faster, leaving little room for disappointment
- SKS, Southern Cross and SRG are all building NextDC facilities, so Wednesday's earnings downgrade hits close to home
The ‘pick and shovel’ plays of the data centre boom have delivered some extraordinary returns in recent years. Now the industry is hitting a wall on several fronts, and the volatility has been brutal.
A long list of names including SKS Technologies, Southern Cross Electrical Engineering, NRW Holdings and GenusPlus have mostly rallied more than 150% since 2025.
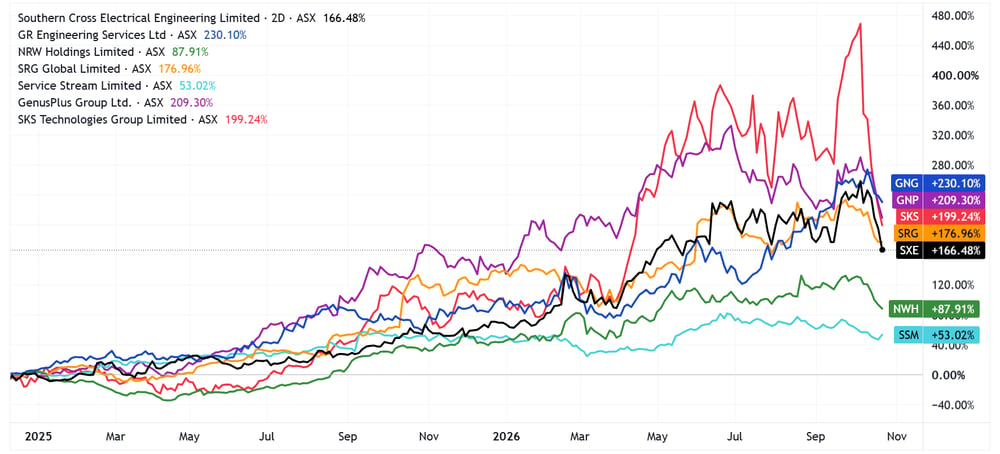
Data as at Wednesday, 21 October 2026 (Source: TradingView)
The gains have been backed by some serious earnings growth, much of it driven by data centre contract wins. This transformed the earnings profile for many companies, with the infrastructure segment for Southern Cross Electrical contributing to 50% of FY26 revenue, compared to just 18.8% in FY22.
The table below shows year-on-year growth in underlying NPAT across the group. Five of the seven grew earnings by more than 20% in FY26, and SKS has close to doubled its bottom line in each of the past two years.
Ticker | Company | FY24 growth % | FY25 growth % | FY26 growth % |
|---|---|---|---|---|
GNG | GR Engineering | 13.5 | 9.6 | 14 |
NWH | NWH | 18.6 | 2.7 | 43.6 |
SXE | Southern Cross Electrical Engineering | 9 | 44.7 | 24.3 |
SRG | SRG Global | 26.7 | 51.4 | 39.8 |
SSM | Service Stream | 36.4 | 36.7 | 18.4 |
GNP | GenusPlus | 38.7 | 76.7 | 44.5 |
SKS | SKS Technologies | 1145.3 | 112.1 | 93.2 |
Source: Company reports
But share price gains often run well ahead of earnings. While SKS has nearly doubled profit two years running, its price-to-earnings ratio has soared from around 25x at the start of this year, to around 47x in early October. That kind of multiple expansion comes down to froth, and the market pricing in structurally higher growth for years to come.
Four setbacks in a fortnight
Most of these names kept trending higher into early October, until a run of setbacks hit the sector.
Thursday, 8 Oct: Firmus withdrew its IPO
Tuesday, 13 Oct: AirTrunk delayed its Singapore IPO
Thursday, 15 October: Coreweave shares tumbled 15% after its credit default swap spreads surged over 1,000 bps, which indicates severe credit distress and a high probability of default
Wednesday, 21 October: NextDC slashes FY27 guidance due to power grid connection delays at its flagship M3 data centre in Melbourne
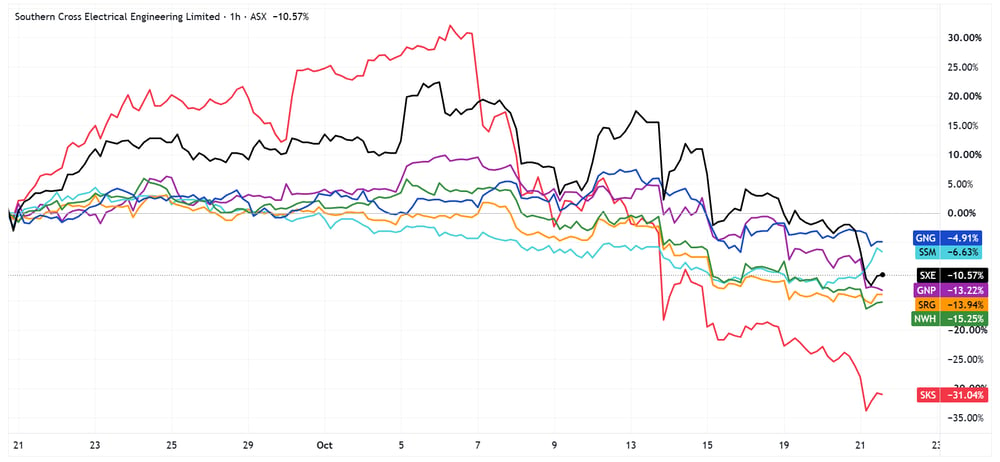
Data as at Wednesday, 21 October 2026 (Source: TradingView)
So the Firmus IPO flopped on its aggressive valuation and capital structure, AirTrunk has pushed its listing into early 2027 citing market conditions, and NextDC has now flagged a new bottleneck in the grid.
The NextDC downgrade is a big deal for several of these names, because they’re the ones building its facilities.
SKS Technologies: $60m in new contracts, including work on NextDC’s M3 facility
Southern Cross Electrical: a $150m suite of new awards, among them NextDC’s S4 data centre in NSW
SRG Global: working on NextDC’s Malaga data centre in Perth, part of a bundled $850m multi-sector contract booking announced in June 2025
Where to from here?
Most names in the group are now down 20–30% since early October. Sentiment has soured just as valuations re-rated on the belief the sector would deliver supercharged earnings for years to come. Either the house of cards is starting to fall and still-elevated valuations have further to drop, or the data centre buildout remains intact and investors are being handed a decent discount.
The problem is that most of these stocks haven’t managed a meaningful bounce since the selling began. Southern Cross has traded higher in just three of the last 15 sessions and is down 33% since 5 October. Anyone who thought it looked cheap and bought five days ago would already be down 16%, and what's to stop the same thing happening over the next five days? Trying to pick the bottom is an impossible task, so the better move may be to wait and see whether these stocks can carve out a low and start to turn.
As far as recent guidance is concerned, most of these companies pointed to more growth in FY27, at the latest August reporting season.
Code | Guided metric | FY26 actual (A$m) | FY27 guidance range (A$m) | Implied growth on midpoint % |
|---|---|---|---|---|
GNG | Revenue | 493.2 | 825-850 | 69.8 |
NWH | Underlying EBITA | 288.6 | 320-330 | 12.6 |
SXE | Underlying EBITDA | 77 | at least 100 | 29.9 |
SRG | EBITDA | 170.1 | 195-205 | 17.6 |
TEA | Underlying NPATA | 73.7 | 128-132 | 76.4 |
GNP | EBITDA | 100.8 | 200-205 | 100.9 |
SKS | PBT | 39.35 | circa 60 | 52.5 |
Source: Company reports
No company has changed its forecasts since the latest run of events. Although SKS did receive an ASX price query on 13 October over its recent share price volatility, and responded: "The Company's work in hand and pipeline remains consistent with the ASX announcement as disclosed on Tuesday 7 October. SKS continues to maintain a strong pipeline of opportunities and remains actively engaged in converting those opportunities into secured work".