RBA hikes interest rate to 4.85%, but a split vote hints the end may be near
A fifth rate hike for 2026 lands on Cup Day, but a third of the Board wasn't convinced it was needed.
Source: Shutterstock
KEY POINTS
- The RBA had already lifted the cash rate four times this year to 4.60%, and last week's hotter-than-expected September quarter inflation data all but locked in a fifth move at today's Melbourne Cup Day meeting.
- The Board lifted the cash rate 25 basis points to 4.85%, its highest level in 18 years, but three of its nine members voted to hold – a split suggesting the bar for a sixth rate hike is now considerably higher.
- We break down the RBA's reasoning for its latest interest rate hike, its updated forecasts for inflation, unemployment and growth, and what the market now views as the likely path of interest rates and mortgage repayments into 2027.
Going into today's meeting, the debate wasn't so much whether the RBA would hike, but whether it would be the last. RBA officials had spent weeks warning inflation was too high, and last week's data delivered the proof: underlying inflation of 3.7% p.a. in the September quarter, well above the RBA's own forecast path. Money markets had a hike about 80% priced, and all but one surveyed economist expected 4.85%.
They got it, but only just. The Monetary Policy Board lifted the cash rate 25 basis points to 4.85% in a 6–3 vote, with three members preferring to hold. The majority, though, was in no doubt, noting "the increasing risk that higher inflation expectations will become embedded" and judging "a further tightening in financial conditions is warranted to support the return of inflation to target".
Here's what the RBA said, what changed in its forecasts for the Australian economy, and what markets now expect for interest rates.
What the RBA said
The split matters. A divided Board suggests some members believe the 125 basis points of tightening delivered this year is already doing its job, and that the bar for a sixth hike is now higher. The statement gave little away on what comes next, saying only that the Board will remain attentive to the data and policy is well placed to respond.
In her post-meeting press conference, RBA Governor Michelle Bullock acknowledged the difficulties higher interest rates create for households, noting, “High inflation is particularly painful for those on low incomes… there is nowhere left to cut spending… and this is why getting inflation down matters so much – it affects everyone but the burden is not felt equally.”
But she defended the Board’s fifth consecutive rate hike, saying "I know this interest rate rise is tough news for many households, but this is the right thing for the Australian economy. It is critical that we stop inflation expectations from being embedded or the problem will only get worse. Some pain now will prevent even worse pain down the track.”
Bullock also conceded that previous increases were already having a negative impact on the economy, noting that spending had slowed, housing prices have come down and conditions in the labour market had eased. There will likely be further pain inflicted by the bank’s tightening, though, with the Governor warning that growth “will need to remain subdued” and the labour market “will need to ease further” to drag inflation back into its 2-3% target band.
New forecasts, worse numbers
The RBA's August forecasts had underlying inflation easing to 3.3% by December. Today's Statement on Monetary Policy revised that materially higher: headline and underlying inflation are now expected to stay above 3% until end-2027, reaching the target midpoint only in mid-2028.
Year-ended forecast | August SMP | November SMP | Change |
|---|---|---|---|
Trimmed mean – Dec 2026 | 3.30% | 3.60% | +0.3% |
Trimmed mean – Dec 2027 | 2.60% | 2.90% | +0.3% |
Headline CPI – Dec 2026 | 3.60% | 4.50% | +0.9% |
Unemployment – Dec 2026 | 4.50% | 4.70% | +0.2% |
GDP growth – Dec 2026 | 1.40% | 1.60% | +0.2% |
Source: RBA, Statement on Monetary Policy, August and November 2026
The RBA's own numbers also show how tight policy has become. It estimates the neutral cash rate – the level that neither stimulates nor restrains the economy – at between roughly 3% and 4.4%. Even before today's hike, the RBA was the only major central bank with a policy rate above its own neutral range, and market pricing has the cash rate still around 4.8% at the end of 2027.
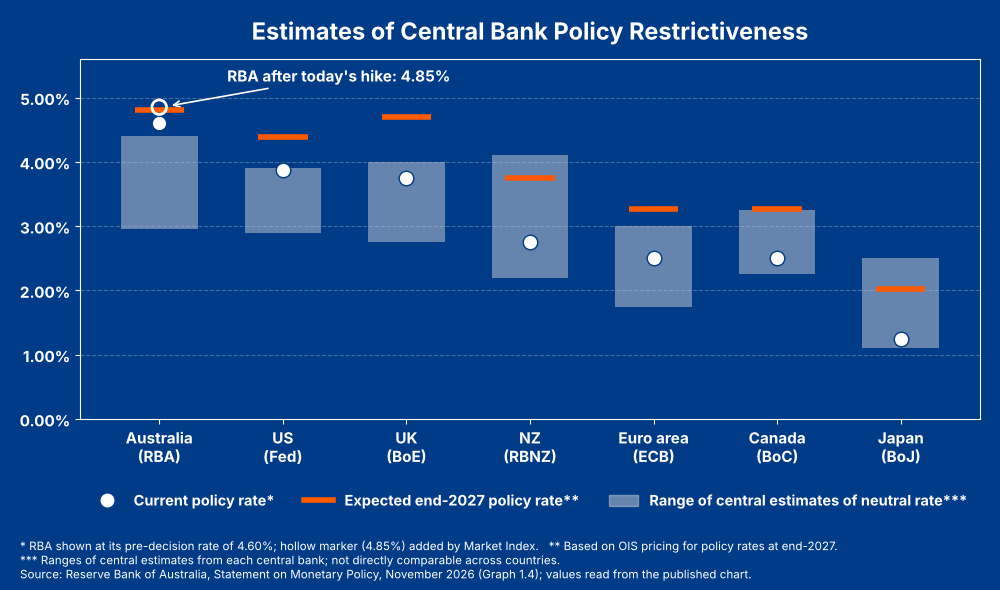
RBA Graph 1.4 neutral rate chart.png – caption: Estimates of central bank policy restrictiveness. Source: RBA, Statement on Monetary Policy, November 2026.
The case for holding is building, though. Unemployment has climbed from 4.1% in January to a five-year high of 4.7%, and the RBA now expects it to keep rising to 5.1% by the end of 2028. House prices are falling fast, with Sydney down more than 10% from its peak.
The bright spot is business investment, forecast to grow 12% this year on the data centre boom, which is why the RBA actually nudged its growth forecasts higher. The weakening jobs market is likely what weighed on the dissenters, and it's the data the Board will watch most closely from here.
What markets now expect
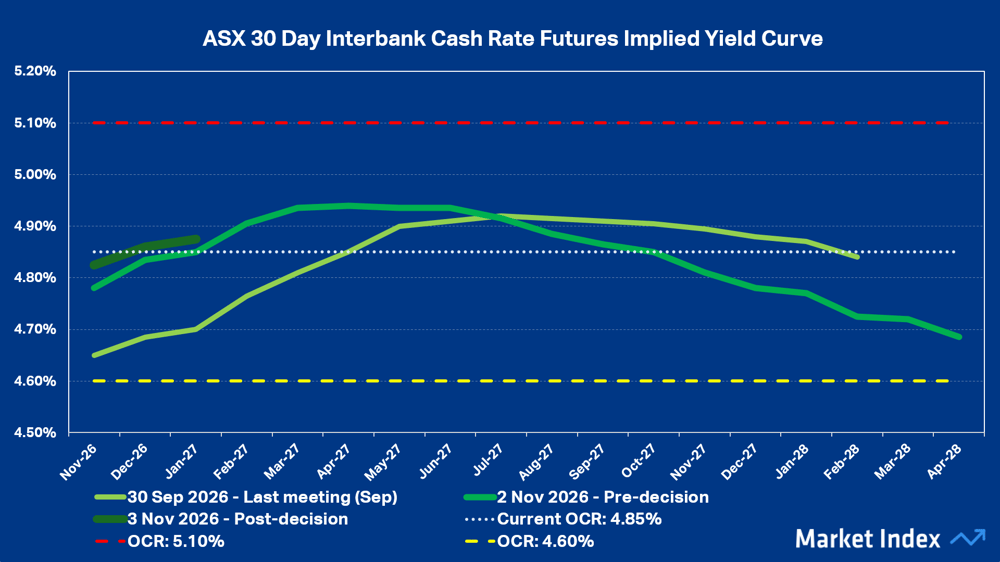
Each line shows where traders expect the RBA’s cash rate to be in each future month, based on ASX 30 Day Interbank Cash Rate Futures. Compare each yield curve line with today’s rate (the white dashed line at 4.85%) with a potential next hike (red dashed line at 5.10%) and a potential next cut (yellow dashed line at 4.60%). Where a yield curve line sits above the current rate, traders expect hikes, and below it, cuts.
In early trade after the decision, futures nudged the odds of a sixth hike at the RBA’s December meeting up to around 10%, from close to zero beforehand. But going into today, the curve priced roughly a one-in-three chance of a hike to 5.10% by May 2027 – down from about one-in-two a week earlier, as traders began betting today’s move would be the last. As for rate cuts, mortgage holders shouldn't expect one before April 2028.
The investment banks we covered last week were split on what comes next. UBS saw the risks skewed towards a further hike to 5.10%, most likely in February 2027, while Morgan Stanley expected the RBA to move to the sidelines as demand softens.
What comes next
The next test is the October monthly CPI and September quarter GDP, both due before the Board's final meeting of the year on 7–8 December. Fuel remains the swing factor, and overnight Brent crude fell about 7.6% on signs of progress in US–Iran talks.
The split vote suggests the peak may now be in, unless inflation surprises again. The Board's next forecast round in February is the key checkpoint.
The RBA is leaving no stone unturned to meet its inflation goals, even if this means maintaining a substantially restrictive stance for some time. If you want to make an omelette, you must break some eggs... only the eggs have jobs and mortgages.
References: Reserve Bank of Australia, Statement by the Monetary Policy Board: Monetary Policy Decision (Media Release 2026-30) and Statement on Monetary Policy, 3 November 2026; Australian Bureau of Statistics, Consumer Price Index, September quarter and September 2026, and Labour Force, September 2026; UBS Global Research, Australian Economic Comment, 28 October 2026; Morgan Stanley Research, Australia Macro+, 28 October 2026; ASX 30 Day Interbank Cash Rate Futures closing prices via TradingView, compiled by Market Index.