In a nutshell:
Relief rally to end an ugly week, with major US benchmarks broadly higher and snapping a four-day lose streak, but still lower for the week
A Fed hike is now the base case after in-line headline CPI masked a hotter core print, with traders moving to roughly 86% odds of a 25 bp increase on Thursday and two hikes priced by year-end
Energy is still the macro driver as Brent settled near US$104 on Friday after spiking toward US$110 on the Saudi pipeline shutdown, while US diesel hit a record and Hormuz diplomacy stalled over the weekend (although Brent is up ~3% to US$107 as of this morning)
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,657 | +0.86% |
Dow Jones | 52,573 | +0.98% |
NASDAQ Comp | 26,333 | +0.96% |
Russell 2000 | 2,904 | +0.45% |
Global Indices | ||
 S&P/TSX | 35,697 | +0.54% |
 Shanghai Composite | 3,888 | -1.18% |
 DAX | 25,569 | +0.82% |
 Hang Seng | 24,806 | -0.60% |
 Nifty 50 | 74,782 | -0.16% |
 Nikkei 225 | 64,011 | -1.93% |
 FTSE 100 | 10,650 | +0.39% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,350.36 | +0.76% |
 Copper | 6.43 | -0.56% |
 WTI Oil | 100.05 | -2.37% |
Currency | ||
 AUD/USD | 0.7165 | -0.02% |
Cryptocurrency | ||
 Bitcoin (USD) | 77,000 | -0.28% |
 Ethereum (AUD) | 3,483 | -1.08% |
Miscellaneous | ||
US 10 Yr T-bond | 4.975 | +0.63% |
VIX | 15.84 | -11.21% |
US Sectors
Sector | % Chg |
|---|---|
| Communication Services | +1.35% |
| Consumer Discretionary | +1.13% |
| Information Technology | +1.11% |
| Industrials | +1.07% |
| Real Estate | +0.88% |
| Financials | +0.62% |
Sector | % Chg |
|---|---|
| Consumer Staples | +0.56% |
| Materials | +0.50% |
| Energy | +0.34% |
| Health Care | -0.14% |
| Utilities | -0.34% |
S&P 500 Session Chart
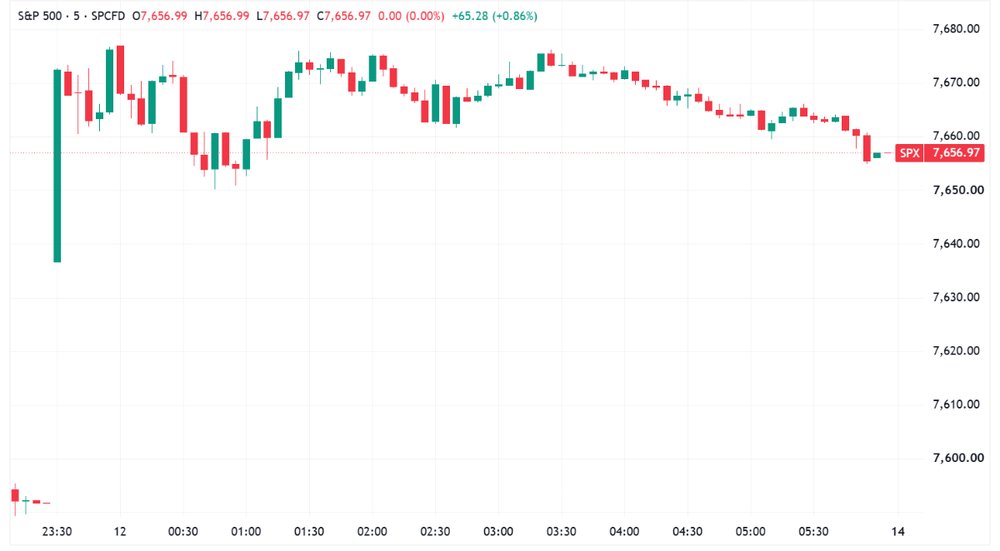
S&P 500 opens higher, off best levels (Source: TradingView)
Overnight Markets
Major US benchmarks closed higher, opening up and holding gains through the session to finish off best levels, snapping a four-day losing streak for the S&P 500, Dow and Nasdaq
US weekly recap: S&P 500 (-0.80%), Nasdaq (-0.66%), Dow (-1.57%), Russell 2000 (-2.41%)
Treasury yields stayed at multi-year highs with the 10-year around 4.97%, its highest since October 2023, and the 30-year holding near 5.36% as inflation and supply concerns persisted
US 2-year yield topped 4.6% and touched its highest level since July 2024, reflecting a sharp repricing toward a Federal Reserve rate increase at this week's meeting
Brent retreated after a volatile week, down 4.5% to US$104.31, snapping a four-day win streak but still up 8.8% for the week
Equity bulls are still hunting a catalyst to push the S&P 500 through 8,000, a level that has receded since the 7,816 intraday record on 13 August as yields and inflation weighed (BBG)
US convertible bond sales hit a record annual total of $131bn as companies turn to the market to fund AI spending, with $25bn raised in August alone (BBG)
Private credit is showing early tremors as government bond yields climb and rate-hike bets build, leaving direct lending exposures looking increasingly stretched (BBG)
Sam Altman told OpenAI staff the company is open to slowing development of its most cutting-edge AI and hopes rival frontier labs coordinate on a similar pace (BBG)
Stocks
Oracle Q1 FY27 revenue up 30% to $19.35bn, about 1% ahead of ests, cloud infrastructure up 121% to $7.4bn, adjusted EPS $1.92 beat by roughly 10%, RPO a record $664bn, shares whipsawed and closed nearly 2% lower (CNBC)
Adobe Q3 FY26 revenue up 13% to $6.76bn, about 1% ahead of ests, adjusted EPS $6.13 beat by roughly 1%, ending ARR $27.5bn, but Q4 revenue guidance midpoint of $6.83bn landed below ests and shares slid (YF)
Dell Technologies rallied more than 10% as part of a broad tech upswing and after RBC initiated coverage at outperform, taking the stock up nearly 350% in 2026 (CNBC)
GameStop climbed more than 3% after chief executive Ryan Cohen disclosed the purchase of 1 million shares at an average $20.375, lifting his stake to 39.347 million shares (CNBC)
Iran & Energy
Saudi Arabia shut its East-West crude pipeline as a precaution after multiple drone attacks, removing the kingdom's main alternative export route while the Strait of Hormuz remains effectively closed (BBG)
The conduit had been moving up to five million barrels a day from eastern fields to the Red Sea port of Yanbu, roughly 4% to 5% of global supply, with satellite imagery showing fires at pump stations (CNN)
Monday's Hormuz meeting between Iran and Gulf nations was postponed, Oman's foreign minister said, delaying the unveiling of a temporary shipping lane agreement negotiated with Tehran (BBG)
Trump said on Saturday the Iran war will likely end soon after November's midterm elections and predicted energy prices would then fall sharply, speaking to reporters during his trip to Ireland (CNBC)
Trump also said Iran was probably responsible for the attacks on Saudi Arabia's East-West pipeline, which Riyadh and Baghdad have both said originated from Iraqi territory (CNBC)
Iranian President Pezeshkian told an audience in New Delhi that Iran will not yield to what he called bullying, rejecting suggestions Tehran would surrender ahead of the BRICS summit (CNBC)
Trump called on Zelenskyy to halt strikes on Russian oil refineries and diesel infrastructure, saying the attacks are causing a global shortage after US diesel passed $6 a gallon (AP)
Tariffs & Trade
Trump said he will remove the tariff on Irish whiskey, announcing the concession at the Irish Open trophy ceremony at his Doonbeg course after lobbying from Irish officials and players (BBG)
BRICS leaders condemned unilateral trade measures in the New Delhi Declaration adopted on Saturday, including tariffs imposed contrary to WTO provisions, and backed restoring the WTO dispute mechanism (AJ)
Xi Jinping used the BRICS platform to push broader local-currency settlement, an open-source BRICS AI region and tighter supply-chain links in a thinly veiled response to US tariff and technology pressure (SCMP)
Central Banks
Bond traders lifted Fed hike bets sharply after hotter-than-expected core US inflation, pricing about a 86% chance of a move this week and two full increases by the end of the year (BBG)
Kevin Hassett said on Sunday the White House would support whatever the Fed decides this week, while maintaining that recent inflation data does not justify another rate increase (BBG)
Japan's August producer price index rose 7.6% year-on-year against a 7.4% median forecast, supporting the case for the Bank of Japan to keep tightening at its meeting this week (BBG)
Yen-based import prices surged 24.8% year-on-year in August after a revised 29.3% rise in July, underlining how currency weakness is still feeding directly into Japanese domestic cost pressures
Markets are near fully pricing a BoJ increase to 1.25% from 1%, with economists polled by Reuters now expecting a further move to 1.75% in the second quarter of 2027 (RT)
Economy
US headline CPI rose 0.4% month-on-month in August and 3.4% year-on-year, both in line with consensus, up from a 0.1% monthly increase in July (CNBC)
Core CPI rose 0.3% month-on-month, a tenth above the 0.2% forecast, while the annual core rate of 2.4% matched expectations and marked the lowest reading since March 2021 (CNBC)
University of Michigan consumer sentiment fell to 47.8 in the preliminary September reading, down 7.5% on the month and the second-lowest print on record behind May's all-time low (CNBC)
UK GDP grew 1.6% year-on-year in July, well ahead of the 1.2% expected, with monthly growth of 0.4% against a flat consensus, driven largely by the services sector (CNBC)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Gold Miners | 97.1 | +1.11% |
| Steel | 108.97 | +0.32% |
| Silver Miners | 96.36 | +0.17% |
| Copper Miners | 88.53 | -0.09% |
| Lithium & Battery Tech | 71.49 | -0.45% |
| Strategic Metals | 70.56 | -2.57% |
| Uranium | 43.53 | -3.27% |
Industrials | ||
| Construction | 94.841 | +1.99% |
| Global Jets | 28.17 | +1.19% |
| Aerospace & Defense | 219.01 | +0.32% |
| Agriculture | 28.93 | -1.33% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 202.93 | +0.14% |
Renewables | ||
| Hydrogen | 44.94 | +2.14% |
| Solar | 47.15 | +0.23% |
Technology | ||
| Data Center & Digital Infrastructure | 28.26 | +1.98% |
| Semiconductor | 527.07 | +1.86% |
| Robotics & AI | 35.28 | +1.50% |
| FinTech | 26.1494 | +1.16% |
| Electric Vehicles | 34.2127 | +0.91% |
| Cloud Computing | 27.13 | -0.15% |
| Cybersecurity | 40.04 | -1.50% |
ASX Today
For those reading on desktop or the website, our ETF table displayed the prior session's data in a few of last week's wraps. Thanks to everyone who flagged it (human error on our end) and apologies for any inconvenience.
Cleanaway Waste Management receives written confirmation from EQT that due diligence has turned up nothing to stop it proceeding, that it won't vary terms to shareholders' detriment, and that it will pay no less than the indicative price. Hard exclusivity has now lapsed, with confirmatory DD and implementation deed negotiations continuing (CWY)
FleetPartners loses Element Fleet Management from the $860m auction, the only suitor not to lodge a revised non-binding indicative bid. PEP's SG Fleet leads at $4.00 a share, ahead of Sumitomo at $3.85 and Orix at $3.80 (AFR)
Future Secure AI nears close of a US$75-85m pre-IPO convertible note round at a US$1.3bn valuation cap, backed by Macquarie Asset Management, Square Peg, Yarra Capital, Firetrail and Robin Khuda. ARR seen passing US$100m by Christmas from US$17m at end-2025, with an ASX listing targeted as early as H2 CY27 (AFR)
What To Watch Today
Calmness (ahead of more volatility): The US market is holding up remarkably well, all things considered (US 10-year on the cusp of 5%, oil tracking towards US$110 and the Fed overwhelmingly likely to hike twice by year end). After snapping the four-day lose streak, the S&P 500 is still within 2% of all-time highs. The ASX 200 is not. It's rolling over aggressively as miners tumble, BHP down ~9% since 25-Aug, with Staples, Real Estate, Healthcare, Discretionary and Tech all off at least 3% in the past week. Friday brought some calm to Wall Street and commodity markets, but this has the look of a classic bounce from no man's land. Even then, yields kept grinding higher and oil opened higher again this morning. Better to let this one prove it's more than a dead cat. What to look out for from here? Miners were at record highs in late August, you'd want to see that leadership return. Free-falling sectors like Discretionary and Real Estate have moved in a straight line down for the past few weeks, you want to see them mark a bottom and begin to turn. And of course, for yields and oil to stop their vertical ascent
Key Events
Stocks trading ex-dividend:
Mon 14 Sep: Chorus (CNU) – $0.256, Credit Corp Group (CCP) – $0.455, Glennon Small Companies (GC1) – $0.02, Kelsian Group (KLS) – $0.10, Saunders International (SND) – $0.01, Virgin Australia Holdings (VGN) – $0.076, WCM Global Growth (WQG) – $0.024
Tue 15 Sep: Data#3 (DTL) – $0.182, Duratec (DUR) – $0.025, Focus Minerals (FML) – $0.08, Guzman y Gomez (GYG) – $0.406, Lovisa Holdings (LOV) – $0.33, Neuren Pharmaceuticals (NEU) – $0.15, Plato Income Maximiser (PL8) – $0.006, Qantas Airways (QAN) – $0.198, Ramelius Resources (RMS) – $0.03, Red Hill Minerals (RHI) – $0.108, Spheria Emerging Companies (SEC) – $0.011, Westgold Resources (WGX) – $0.10, Whitefield Income (WHI) – $0.009
Wed 16 Sep: Auckland International Airport (AIA) – $0.056, Aurelia Metals (AMI) – $0.01, BKI Investment Company (BKI) – $0.02, Capricorn Metals (CMM) – $0.05, IMDEX (IMD) – $0.018, Inghams Group (ING) – $0.061, PWR Holdings (PWH) – $0.05, Servcorp (SRV) – $0.16, Service Stream (SSM) – $0.035
Thu 17 Sep: a2 Milk Company (A2M) – $0.067, EDU Holdings (EDU) – $0.03, Embelton (EMB) – $0.20, Flight Centre Travel Group (FLT) – $0.30, Lycopodium (LYL) – $0.37, SKS Technologies Group (SKS) – $0.065, Solaris Australian Equity Income Plus (SET) – $0.005, South32 (S32) – $0.075, Supply Network (SNL) – $0.44, Tourism Holdings Rentals (THL) – $0.063, WAM Income Maximiser (WMX) – $0.007, West African Resources (WAF) – $0.20
Fri 18 Sep: Adrad Holdings (AHL) – $0.026, Centrepoint Alliance (CAF) – $0.018, Macmahon Holdings (MAH) – $0.013, Vita Life Sciences (VLS) – $0.05
Other ASX corporate actions today:
Dividends paid: Accent Group (AX1), Computershare (CPU), Fiducian Group (FID), Shape Australia (SHA)
Earnings: Carnarvon Energy (CVN), PointsBet (PBH)
IPOs: None
AGMs: None
Economic calendar (AEST):
10:30 pm: Canada Inflation