In a nutshell:
Major US benchmarks finished higher, just off best levels in a day where equities rose, yields fell and commodities made gains
Bond yields eased after Fed hike, with the 10-year dipping below 5% and falling for the first time in nine sessions
Brent fell for a second day to US$104 a barrel as Saudi Arabia moved to restore its damaged East-West pipeline.
BoJ decides rates today with a lift to 1.25% near fully priced, and RBA Governor Michele Bullock speaks, keeping regional rates risk live for the local open
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,638 | +1.14% |
Dow Jones | 51,778 | +0.61% |
NASDAQ Comp | 26,418 | +1.69% |
Russell 2000 | 2,875 | +0.55% |
Global Indices | ||
 S&P/TSX | 35,874 | +1.08% |
 Shanghai Composite | 3,876 | -0.41% |
 DAX | 25,717 | +0.70% |
 Hang Seng | 24,604 | -0.44% |
 Nifty 50 | 74,315 | -0.03% |
 Nikkei 225 | 64,136 | +0.33% |
 FTSE 100 | 10,816 | +1.19% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,341.39 | +1.82% |
 Copper | 6.54 | +1.69% |
 WTI Oil | 101.09 | -1.31% |
Currency | ||
 AUD/USD | 0.7109 | -0.01% |
Cryptocurrency | ||
 Bitcoin (USD) | 76,388 | +1.02% |
 Ethereum (AUD) | 3,439 | +2.27% |
Miscellaneous | ||
US 10 Yr T-bond | 4.947 | -1.18% |
VIX | 15.44 | -12.82% |
US Sectors
Sector | % Chg |
|---|---|
| Information Technology | +2.20% |
| Consumer Discretionary | +1.43% |
| Utilities | +0.86% |
| Health Care | +0.64% |
| Materials | +0.62% |
| Communication Services | +0.60% |
Sector | % Chg |
|---|---|
| Energy | +0.55% |
| Real Estate | +0.33% |
| Industrials | +0.21% |
| Consumer Staples | -0.01% |
| Financials | -0.10% |
S&P 500 Session Chart
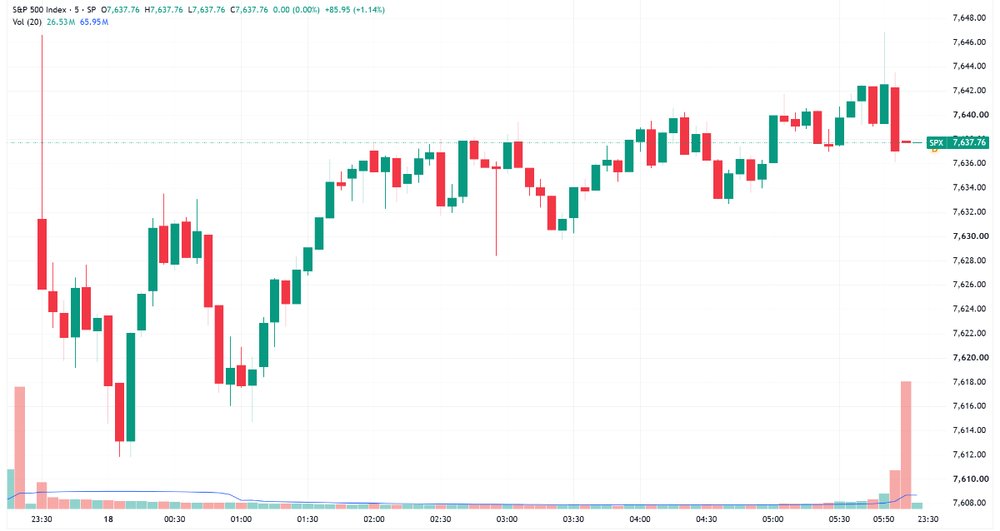
S&P 500 made early gains, trended slightly higher to finish near best levels (Source: Trading View)
Overnight Markets
Major US benchmarks finished higher and near their best levels
Nine of the 11 sectors on the S&P 500 made gains, with only Consumer Staples and Financials in the red
Treasury 10-year yields snapped an nine-day rising streak, retreating from the highest level since 2007 to 4.93%
A closely watched gauge of chipmakers climbed 3% as falling oil prices lent support to optimism that inflation can be contained, with the dollar wavering and gold advancing
As bonds yields fell gold rose 1.7% to US$4,341/oz, snapping a three day slide, silver up 3.5% to US$65.22/oz and copper made its largest daily gain since July, up 2.7% to US$6.63/lb
Volatility collapsed, with the VIX down roughly 12% to near 15.5 intraday as the Fed's first hike in three years was digested as a credibility restoration rather than a growth shock (YF)
Friday's triple witching is the quarter's largest expiry, with Citadel Securities estimating about $6.2 trillion of US options exposure rolling off, on track to top June's $7.7 trillion (EBC)
Barclays strategist Venu Krishna warned higher memory costs are a key 2027 earnings risk for chip buyers, noting Apple attributed its recent gross margin compression to memory (YF)
Yardeni Research president Ed Yardeni told Bloomberg the Fed could raise rates twice more this year, after cutting his year-end S&P 500 target to 7,900 from 8,400 (BBG)
The SEC issued an order creating a regulatory pathway for trading venues to list tokenised versions of US stocks, effective immediately, two days after the Clarity Act stalled in the Senate (CNBC)
Stocks
Generac jumped about 18% after agreeing to supply Amazon with industrial backup generators for its data centres, with initial deliveries of $2.4bn across 2027 and 2028 and payments of up to $8bn (TS)
Micron rose more than 5%, dragging Nvidia, Broadcom and SK Hynix higher, after Intel chief executive Lip-Bu Tan said memory demand is not slowing and capacity constraints will worsen next year (YF)
Oracle climbed about 5%, rebounding from post-earnings lows, as reports that OpenAI is in talks to raise capital at a $1.2tn valuation eased concerns over its AI infrastructure build-out (TMF)
Lucid jumped about 6% after signing a deal with European ride-hailing platform Bolt to deploy at least 25,000 autonomous vehicles built on Nvidia's Hyperion architecture (YF)
Moderna gained about 9% as investors continued to react to positive Phase 3 results with Merck for their personalised mRNA cancer vaccine (TS)
Iran & Energy
Trump said the US is hopefully nearing the end of its almost seven-month war with Iran and that he had spoken to Tehran directly, without providing further detail (CNBC)
Houthi spokesman Yahya Saree said the group launched fresh drone and missile strikes on the Saudi Red Sea oil port of Yanbu and the Khamis Mushait airbase, claiming Saudi Arabia ran 450 airstrikes on Yemen this week (RT)
Trump is expected to meet leaders from the six Gulf Cooperation Council states, with initial State Department invitations sent Wednesday and the guest list possibly widening (CNBC)
Tehran has not confirmed that direct negotiations have resumed, and a senior Iranian official publicly rejected talks a day earlier unless Iran's conditions are met (AJ)
Yemeni government forces are fighting to prevent further Houthi advances near the Kahbub mountains and Taiz, with Saudi air strikes supporting them around Taiz (AJ)
Tariffs
Trump threatened very serious tariffs on the European Union, or halting trade with the bloc in many areas, if he judges its offer to make Canada an associate member a hostile act (CNBC)
The threat sits on top of an existing 50% US tariff on Canadian goods and a plan to ban Canadian dairy, alcohol and auto imports later this month (CNBC)
Mark Carney told the European Parliament in Strasbourg that Canada and Europe are stronger together, saying economic integration is being weaponised and supply chains treated as weak points (CNBC)
China's Commerce Ministry said trade teams remain in close communication on a reciprocal framework covering $30bn of goods from each side, with further developments to be released in due course (PD)
Trump hosts Xi Jinping at the White House on 24 September with tariffs topping the agenda, after Treasury Secretary Scott Bessent said he would meet Vice Premier He Lifeng this weekend (AFP)
Central Banks
The Bank of England held rates at 3.75% with three of nine MPC members voting for a 25 basis point increase, and Governor Andrew Bailey warned the longer energy volatility persists the more likely a hike becomes (YF)
Chairman Kevin Warsh framed the Fed's first hike in three years as a good-news story tied to a strengthening economy, a marked shift from the crisis framing of the 2022 to 2023 tightening cycle (BBG)
SGH Macro Advisors chief US economist Tim Duy told clients Warsh revealed his inner hawk at the press conference and a willingness to keep raising rates until inflation is under control (CBS)
The dot plot showed 12 of 18 policymakers putting appropriate 2026 policy at an average of 4.125%, with four seeing 50 basis points more of tightening and only two seeing none (YF)
Traders now price three additional Fed increases by the middle of next year, threatening to keep the US-Japan rate gap wide even as the BoJ tightens (BBG)
Australian markets are pricing an 88% chance of an RBA increase in September after the Fed's move, with the ASX 200 closing 0.4% higher at 8,732 on Thursday (ABC)
The Bank of Japan is expected to lift its policy rate 25bps to 1.25% today, the highest in about three decades, with Japan's August national CPI landing within hours of the decision (IL)
Economy
US initial jobless claims fell 10,000 to 196,000 in the week ended 12 September, the lowest since mid-July and well below ests of 208,000 (RT)
Pantheon Macroeconomics chief said the depressed reading likely reflects Labor Day seasonal adjustment issues, leaving the Fed focused on inflation (RT)
US housing starts fell 2.6% to an annualised 1.275m in August against ests of a 1.32m pace, dragged down by a 22.5% plunge in multi-family starts (BBG)
The Bank of England held Bank Rate at 3.75% with three of nine MPC members voting for a 25 basis point increase, and Governor Andrew Bailey warned the longer energy volatility persists the more likely a hike becomes (YF)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Lithium & Battery Tech | 69.85 | -0.24% |
| Steel | 106.188 | -0.37% |
| Copper Miners | 84.19 | -0.47% |
| Uranium | 41.37 | -0.96% |
| Strategic Metals | 67.61 | -1.01% |
| Gold Miners | 92.8 | -1.41% |
| Silver Miners | 90.93 | -1.92% |
Industrials | ||
| Aerospace & Defense | 215.27 | +0.59% |
| Agriculture | 28.82 | -0.21% |
| Global Jets | 27.8 | -0.29% |
| Construction | 91.69 | -0.32% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 202.4 | +0.20% |
Renewables | ||
| Hydrogen | 43.863 | +0.81% |
| Solar | 44.62 | -1.04% |
Technology | ||
| Semiconductor | 502.06 | +0.64% |
| Data Center & Digital Infrastructure | 27.28 | +0.52% |
| Robotics & AI | 34.72 | +0.26% |
| Electric Vehicles | 33.035 | -0.57% |
| Cloud Computing | 28.02 | -0.60% |
| Cybersecurity | 44.95 | -0.77% |
| FinTech | 25.15 | -2.06% |
ASX Today
Forrestania Resources' takeover offer for Zenith Minerals remains open after the Takeovers Panel issued orders that do not prevent the bid from proceeding. Forrestania has acceptances from holders of about 49.23% of Zenith shares, giving it a relevant interest of roughly 58.33% (FRS)
What To Watch Today
A relief rally: Yesterday the Fed hiked, Warsh spoke and markets sold off. This morning gave us opposite, with equities recouping two days of declines in a single session. Yields eased, the all-important 10-year down 8 bps to 4.93%, and Brent edged lower. Everything starting to move in the right direction, but is the strength just off the back of hedges rolling off post-FOMC?
Triple witching day: It's September triple witching in the US, where the quarterly expiries of stock index futures, index options and single-stock options all land in the same session, with most of the action in the final hour. These are routinely among the heaviest-traded sessions of the year, with billions in notional value to settle. According to Bluekurtic Market Insights, the S&P 500 has fallen 12 times out of 14 since 2012. Since 2000, the following five days have averaged a 1.0% decline and finished positive just 26.9% of the time.
Commodities bounce: Copper rallied 2.7% to US$6.63/lb, clawing back roughly half of last week's losses from the stalled US tariff talks and general weakness, while gold added 1.8% to US$4,341/oz. That drove broad-based strength across our overnight ETF watchlist, with nickel, gold miners, uranium, copper miners and rare earths/strategic metals all up 2-4%. Most have now recovered the past two days of declines, though they sit 10-15% below late August levels. So a bit of a bounce from oversold levels, for now.
Key Events
Stocks trading ex-dividend:
Fri 18 Sep: Adrad (AHL) – $0.026, Centrepoint Alliance (CAF) – $0.018, Macmahon (MAH) – $0.013, Vita Life Sciences (VLS) – $0.05
Mon 21 Sep: Cochlear (COH) – $1.30, New Hope Corporation (NHC) – $0.30
Tue 22 Sep: Fleetwood (FWD) – $0.095, Latitude Group Holdings (LFS) – $0.055, Southern Cross Electrical Engineering (SXE) – $0.075
Wed 23 Sep: Genesis Energy (GNE) – $0.063, IPD Group (IPG) – $0.079, St Barbara (SBM) – $0.05
Thu 24 Sep: Bisalloy Steel Group (BIS) – $0.13, Briscoe Group Australasia (BGP) – $0.081, PRL Global (PRG) – $0.03, Salter Brothers Emerging Companies (SB2) – $0.02, Wiseway Group (WWG) – $0.006
Other ASX corporate actions today:
Dividends paid: Australian Ethical Investment (AEF), Beacon Lighting Group (BLX), Clinuvel Pharmaceuticals (CUV), Cuscal (CCL), Eagers Automotive (APE), Ebos Group (EBO), Euroz Hartleys Group (EZL), Hansen Technologies (HSN), Jupiter Mines (JMS), Qualitas (QAL), Resimac Group (RMC), Schaffer Corp (SFC), Venus Metals Corp (VMC), Yancoal Australia (YAL)
IPOs: None
AGMs: None
Economic calendar (AEDT):
9:30 am: Bank of Japan rate decision
4:00 pm: UK retail sales